Yesterday's Wall Street Journal featured yet another piece on inept long-term management. This time, we were treated to an in-depth explanation of how major airlines have apparently chosen to manage ineptly for years.
According to the Journal's article,
"The improving financial results posted by seven of the nation's 10 big airlines in recent months reflect a fundamental shift in strategy....The big carriers, which for decades have doggedly pursued market share at any cost, now are focusing just as aggressively on the profitability of each route and flight."
Imagine that. Actually measuring profitability on a flight and route basis, then choosing to stop flying the unprofitable ones. What kind of management were shareholders of these '10 big airlines' paying for all those years- dart throwing? ouija boards?
It isn't really necessary to reiterate in detail what the well-written article states. Airline after airline has finally gotten serious about operating on profitable routes, and adjusting their size to fit. Load factors are now expected to reach 85% this summer.
Isn't it about time, for an industry that has frequently been described as having lost money, on a cumulative basis, since the Wright brothers flew at Kitty Hawk at the dawn of the last century? According to the article, part of the profitability turnaround comes from a new generation of revenue management systems which allow for pricing decisions to take into account whether passengers are flying just one segment of a flight, or are a more lucrative passenger on a longer trip, of which the segment is but one part.
I'm reminded of the legendary Bob Crandall's comment that he wished he could have spun off American Airlines and kept the reservation system. Knowledge is power, and it looks like, in the airline industry, some rational managers, with better knowledge management tools, are finally gaining the upper hand.
Will this result in higher non-business fares and fuller airplanes? Doubtless. Of course, if that bothers you, why not wait til there's only one airline left on many routes, and pay their uncontested fare? Because the way things have been going, it's only a matter of time until something like that scenario was bound to occur.
I don't keep track, but so many airlines have been in, then out, then maybe back in, then out again, of Chapter 11, it's hard to recall the ones that have not filed for bankruptcy at some point.
That's no way to run a company, much less a sector. Business behavior like that signals too much capital committed to earn too few profits, and, thus, excess capacity. As if on cue, the article in the Journal notes that, these days, airlines are not chasing every expansion opportunity that occurs with a failed airline. Rather, they are focusing on development of added routes providing they are quickly and routinely profitable. What a concept!
Perhaps, in a backward-looking sort of way, airline executives have finally learned about consumer behavior in their business. Most non-business flyers appear to value price over brand, so that brand ubiquity added no value in that segment. Add in the ever-increasing pressure to avoid travel using email, instant messaging, and desktop- and laptop-based videoconferencing on inexpensive cameras, and you have a recipe for the disaster that occurred in the airline industry. Demand became hyper-price sensitive, and the internet contributed to the "discovery" of low prices, squeezing airline margins.
Apparently, empty feeder flights didn't deliver profitable customers and higher load factors when all routes are under pricing pressure.The eventual reaction, for airlines to survive, is to reduce capacity to the solidly profitable routes. It appears that in airline management, glamour is out, and sensibility is in.
Schumpeterian dynamics are alive and well in yet another part of our economy. And that, as usual, is a long term good thing for consumers and our economy.
Tuesday, June 06, 2006


Monday, June 05, 2006
More On Management Mediocrity: Time Warner's Example
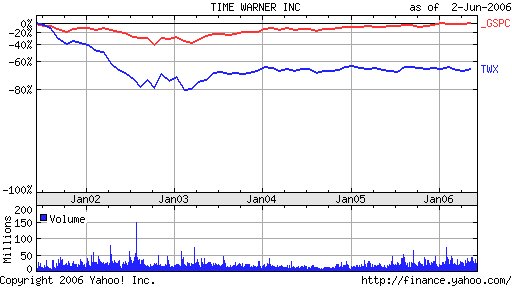
Friday's Wall Street Journal featured an article on Time Warner that provided, a very revealing look into the troubled media conglomerate's strategic difficulties stretching back all the way to the 1990 merger of Time and Warner Brothers.
Rather than focus exclusively on Time Warner's many missteps throughout the years since 1990, I'd like to treat it as an excellent example of how companies which people believe are run by deep ranks of talented, intelligent senior executives are, in fact, mismanaged by the confused bungling of mostly mediocre, turf-protecting senior executives.
As the article discusses some of the changes in the media sector over the past decade, it quotes Sumner Redstone of Viacom saying,
"We had a lot of clout from size. Look at where it got us- nowhere. The world has changed a lot. Success depends to a large extent on your ability to adapt."
It seems a little late for Redstone to be now realizing these truths. Size hasn't counted for as much as it used to since, oh, when IBM lost its early lead in PCs in the late-1980s. And when has the ability to adapt ever not been useful? It would appear that, like Redstone and Viacom, the Ross-Levin-Parsons regime of Time Warner also failed to appreciate the necessities of successful adaptation to changing environments.
Apparently, Time Warner's history is full of various warring groups from Time, Warner, HBO, and AOL, depending upon the era, protecting their own, or trying to grab another internal group's turf, for internal financial advantage. This type of multi-divisional energy expenditure is a sure way for a large company to be come a smaller company, if not simply never become larger, over time. Time Warner seems to have done just fine on this measure of "success."
While current TW President Jeff Bewkes is pushing each unit to be unsubsidized, he still manages a conglomerate, each of whose acquisitions were partially sold on the benefits of integration and expense sharing. So, what he is essentially doing, by running TW as a group of independent units, is admitting that more than a decade of mergers and acquisitions were sold to investors for ultimately indefensible reasons.
I don't think I read in the piece that any of the ex-senior executives, such as Gerald Levin, Nick Nicholas, Steve Case, or Dick Parsons are giving any of their easily-won compensation back as recompense to misled investors.
And, yet, after years of lackluster shareholder return performance, Parsons still maintains, "if you have the sum of the parts under your control, you can sometimes get to the market faster."
Yes, and that is reflected where, in the firm's stock price performance, Dick?
For background, I've pasted a Yahoo-sourced stock price chart for Time Warner, in comparsion with the S&P500, for the past five years. Prior to that, it is not clear whether the stock price used was AOL's, or Time Warner's, but it seemed to have been the former's, which would be moot for this post.
Viewing the chart, it's easy to see that TWX lost most of the 80% of value to the index by early 2003, and then slid a little bit more in the ensuing three years.
The WSJ piece further attributes to TW's 'executives' the belief that "...its breadth gives management a birds-eye view of the industry's shifting landscape and a better understanding of key issues."
Again, Time Warner seems to be able to do nothing for its shareholders with that 'birds-eye view and the 'better understanding of key issues.' My suspicion is that this is one of those cases in which a company would be better off dumping the unprofitably growing, or nongrowing divisions, and hire a tightly-controlled team of outside consultants to provide a cheaper 'birds-eye' view of the sector, from a truly objective perspective.
Media has surely been hit, and hit hard, by the incursion of digital technology over the last decade. It would be a pretty narrow-minded, dull management group indeed to believe that such dynamic value destruction and change in source of value creation, would lend itself to maintaining a large, slow-moving, bureaucratically-infighting-plagued conglomerate.
(Actually, as I write that, I'm reminded of Microsoft and Google, but that's for another post....)
As I wrote at the beginning of this piece, I don't wish to single out Time Warner, per se, for inept management, although they certainly have displayed it over the past five years. And, it appears from the WSJ article, if we could find the original Time Warner stock price history for 1990-2000, probably for that period as well.
Rather, I'd like to note how simply following the serial, failed expansions and merger integrations of more than a decade, alone, should have convinced a reasonable person that something was terribly amiss in the management of this company, or any company behaving in this fashion.
To continually destroy value via mergers, while simultaneously extolling the value of them, is ludicrous behavior. Why did anyone think the TW-AOL merger would ever work, with Time Warner's own checkered history of expansion?
Large firms often do have inept management. Track records of failure to consistently outperform the S&P500's total return do mean something. It's a shame that Time Warner has been able to reward senior management for fifteen years, while serially botching merger after merger, at their shareholder's expense.
My advice is, when you observe consistently mediocre, or worse, performance of a firm over several years time, take it seriously. Don't assume a turnaround is in the works any day soon. Don't assume the management responsible for the ongoing mediocre performance will wake up tomorrow, see reality, and change strategies on a dime. Rather, expect what you have heard from Dick Parsons of Time Warner for five years- continued justification for failed strategies and execution thereof. Then, sell the stock if you own it, and buy something with a better track record.
Saturday, June 03, 2006
Chicago Fed's Michael Moskow on CNBC
Last week, Chicago Federal Reserve Bank President Michael Moskow sat for an interview with CNBC. Sadly, the time was wasted by the network's "senior economics reporter," Steve Leisman, serving up what he thought were clever or tricky questions.
Nevertheless, Moskow's calm intellect and wisdom shone through. The Fed officer easily ignored Leisman's attempt to get him to divulge either Fed discussion details, or his own particular views on the coming meeting's decision for another rate hike.
What clearly emerged from Mr. Moskow's comments is a very confident, cautious, and experienced senior civil servant. He appears to be the type of experienced business person who makes you feel fortunate and more at ease, knowing he is on the job in his present position.
Ever mindful of the weight of his slightest remark, he simply reiterated that the recent data showing inflation running near 2% is at the high end of the Fed's announced comfort zone, and that the Fed is using developing data to guide its rate policies. Despite Leisman's efforts to pump him for "confidential" information, Moskow simply chuckled and ignored the questions.
The rest of the CNBC staffers on the show that morning had nothing better to ask of Moskow, either. Except for Becky Quick, whose question, I confess, I can't recall. It was inventive, but not really very informative.
It looks to me like the Fed really has its act together. Moskow's appearance sent a clear message that evolving economic data will continue to guide the group's interest rate moves, and that they will move to keep inflation from rising above the current level, which is at the upper range of their target zone.
It's helpful to keep this simple information in mind, because the business media will be trying relentlessly to concoct a news "story" about the impending Fed meeting's actions every day between now and that next meeting. Leisman was already busy, within an hour of the interview's end, with his "instant analysis" of the discussion. He apparently did not see the comical oxymoron in that phrase, in this instance.
Yes, there will be a lot more headlines to come. Fed-watching seems to be the topic that CNBC and other business media feel will sell the most airtime and print ads for the forseeable future.
Nevertheless, Moskow's calm intellect and wisdom shone through. The Fed officer easily ignored Leisman's attempt to get him to divulge either Fed discussion details, or his own particular views on the coming meeting's decision for another rate hike.
What clearly emerged from Mr. Moskow's comments is a very confident, cautious, and experienced senior civil servant. He appears to be the type of experienced business person who makes you feel fortunate and more at ease, knowing he is on the job in his present position.
Ever mindful of the weight of his slightest remark, he simply reiterated that the recent data showing inflation running near 2% is at the high end of the Fed's announced comfort zone, and that the Fed is using developing data to guide its rate policies. Despite Leisman's efforts to pump him for "confidential" information, Moskow simply chuckled and ignored the questions.
The rest of the CNBC staffers on the show that morning had nothing better to ask of Moskow, either. Except for Becky Quick, whose question, I confess, I can't recall. It was inventive, but not really very informative.
It looks to me like the Fed really has its act together. Moskow's appearance sent a clear message that evolving economic data will continue to guide the group's interest rate moves, and that they will move to keep inflation from rising above the current level, which is at the upper range of their target zone.
It's helpful to keep this simple information in mind, because the business media will be trying relentlessly to concoct a news "story" about the impending Fed meeting's actions every day between now and that next meeting. Leisman was already busy, within an hour of the interview's end, with his "instant analysis" of the discussion. He apparently did not see the comical oxymoron in that phrase, in this instance.
Yes, there will be a lot more headlines to come. Fed-watching seems to be the topic that CNBC and other business media feel will sell the most airtime and print ads for the forseeable future.
Friday, June 02, 2006
Kinder Morgan's Private Buyout: Some Thoughts on the Larger Trend
This week saw the well-regarded energy firm Kinder Morgan become the object of a private equity buyout by its senior managers. The last information I saw had them offering something like a 16% premium to the firm's current market value.
Rather than discuss the pros and cons of this particular buyout, and the ethics of internal management, who know more about a company's prospects than anyone else, "offering to buy" a firm from other shareholders, I'd like to discuss the larger phenomenon of which this is the most recent example.
What may be the long term effects of a continuing series of private equity buyouts of publicly-held large-cap US firms? What does this mean for equity strategy managers, and investors in general?
First, consider why some firms are doing these buyouts. Sarbanes-Oxley has been mentioned as being both a source of the movement offshore of significant amounts of new business capital formation. A variant of that is to move business capital beyond the reach of the law by remaining in America, but going private.
If this continues, it's possible that one result is a near-term decline in the average return of indices of publicly-held companies, such as the S&P500. As the index replaces firms going private, one has to wonder if the replacements represent a pool of lesser-performing firms.
For an equity strategy like mine, the dynamic of outperforming the index doesn't really change. No matter what the average of the index, there will always be "above average" firms. Whether many of them are consistently superior is another question, but my expectation is that there will still be some which fit that criteria.
However, if the overall rates of returns available to public shareholders falls, it does nothing good for investors in general.
On the other hand, one has to wonder for how long private equity stays private. Isn't the ultimate goal to buy undervalued assets, improve their value, and spin them back out? If so, one would expect that these firms will begin to come out "the other end" of the buyout process, and release higher-valued firms into the publicly-held universe.
As higher-valued firms, one might expect their future returns to be less, since the value was built and taken out by the private equity groups. If this happens with sufficient frequency, perhaps buyout premiums will rise to clear the market of these deals in the first place.
If not, there is another phenomenon which may occur. I believe KKR was rumored, or is, structuring a sort of derivative cash-flow security based upon some of their gone-private entities. It seems that they are planning to slice up value of some of their private deals much like the way in which collateralized mortgage obligations slice the income streams from mortgage pools into differently performing tranches.
If this happens, we would see some elements of the publicly-held sector transformed into a sort of non-voting, non-operational claim on cash flows, and perhaps, value of businesses, without "shareholder" votes.
It's an interesting new development in long-term finance. It would also settle, in those cases, the issue of so-called "shareholder democracy" and "corporate governance." In a sense, it would be a modern twist on the "B shares" approach used by family companies gone public, such as Wrigley, Murdoch/Newscorp, and Dow Jones.
Rather than discuss the pros and cons of this particular buyout, and the ethics of internal management, who know more about a company's prospects than anyone else, "offering to buy" a firm from other shareholders, I'd like to discuss the larger phenomenon of which this is the most recent example.
What may be the long term effects of a continuing series of private equity buyouts of publicly-held large-cap US firms? What does this mean for equity strategy managers, and investors in general?
First, consider why some firms are doing these buyouts. Sarbanes-Oxley has been mentioned as being both a source of the movement offshore of significant amounts of new business capital formation. A variant of that is to move business capital beyond the reach of the law by remaining in America, but going private.
If this continues, it's possible that one result is a near-term decline in the average return of indices of publicly-held companies, such as the S&P500. As the index replaces firms going private, one has to wonder if the replacements represent a pool of lesser-performing firms.
For an equity strategy like mine, the dynamic of outperforming the index doesn't really change. No matter what the average of the index, there will always be "above average" firms. Whether many of them are consistently superior is another question, but my expectation is that there will still be some which fit that criteria.
However, if the overall rates of returns available to public shareholders falls, it does nothing good for investors in general.
On the other hand, one has to wonder for how long private equity stays private. Isn't the ultimate goal to buy undervalued assets, improve their value, and spin them back out? If so, one would expect that these firms will begin to come out "the other end" of the buyout process, and release higher-valued firms into the publicly-held universe.
As higher-valued firms, one might expect their future returns to be less, since the value was built and taken out by the private equity groups. If this happens with sufficient frequency, perhaps buyout premiums will rise to clear the market of these deals in the first place.
If not, there is another phenomenon which may occur. I believe KKR was rumored, or is, structuring a sort of derivative cash-flow security based upon some of their gone-private entities. It seems that they are planning to slice up value of some of their private deals much like the way in which collateralized mortgage obligations slice the income streams from mortgage pools into differently performing tranches.
If this happens, we would see some elements of the publicly-held sector transformed into a sort of non-voting, non-operational claim on cash flows, and perhaps, value of businesses, without "shareholder" votes.
It's an interesting new development in long-term finance. It would also settle, in those cases, the issue of so-called "shareholder democracy" and "corporate governance." In a sense, it would be a modern twist on the "B shares" approach used by family companies gone public, such as Wrigley, Murdoch/Newscorp, and Dow Jones.
Thursday, June 01, 2006
Steve Ballmer Doesn't Get It
Steve Ballmer was quoted this week as saying that Microsoft's $34.8B cash position "is a high class problem to have."
How stupid can you be? Really, for a guy this wealthy, having so much power at Microsoft, to say something so inane, makes you wonder why anyone would hold the firm's stock, doesn't it?
Having that much cash means the firm can't find risk-adjusted, profitable ways to spend it. They've run out of ideas that will add to shareholder value. Forget building truly better, more secure operating systems or application software. Or browsers. Instead, Bill and Steve are going windmill-tilting over near Google.
Am I the only one who sees it this way? Hasn't the issue of excess liquidity on balance sheets been resolved decades ago? And especially in this era of incredible liquidity from hedge funds and private equity firms? Excess cash on a firm's balance sheet is of no incremental value. Except to waste it, a la GM and Ford.
"Having" cash is no big deal. Putting it to value-creating work is. That's what Ballmer and Gates haven't done for the last five years.
Microsoft's salad days are over. Period. This type of senseless chest-beating on Ballmer's part, 'we have more cash than you do, and it is not a problem,' is further evidence of their failure to accept reality.
You want to talk about corporate governance? Where's the board of Microsoft on this one? Why haven't they stripped Chairman/Chief Software Architect Bill and CEO Steve of their jobs on behalf of the shareholders who have suffered below-market returns for the past five years? Why haven't they forced the use, or dividending of, the bulk of the $34.8B cash on the firm's balance sheet?
Now, that would take some fortitude. Does the lead outside director of Microsoft have it? The "official" Microsoft website does not reveal who that would be. But here are a few of the "winners" currently on the firm's board: Dina Dublon, former CFO of the mediocre JPMorganChase; Ray Gilmartin, recently deposed...err..retired CEO of Merck; Charles Noski, former Vice-Chairman of AT&T, a firm which self-destructed through incompetent senior executive leadership and mismanagement. I don't think this crew will be challenging Chairman Bill anytime soon about which way to steer the foundering S.S. Microsoft.
How stupid can you be? Really, for a guy this wealthy, having so much power at Microsoft, to say something so inane, makes you wonder why anyone would hold the firm's stock, doesn't it?
Having that much cash means the firm can't find risk-adjusted, profitable ways to spend it. They've run out of ideas that will add to shareholder value. Forget building truly better, more secure operating systems or application software. Or browsers. Instead, Bill and Steve are going windmill-tilting over near Google.
Am I the only one who sees it this way? Hasn't the issue of excess liquidity on balance sheets been resolved decades ago? And especially in this era of incredible liquidity from hedge funds and private equity firms? Excess cash on a firm's balance sheet is of no incremental value. Except to waste it, a la GM and Ford.
"Having" cash is no big deal. Putting it to value-creating work is. That's what Ballmer and Gates haven't done for the last five years.
Microsoft's salad days are over. Period. This type of senseless chest-beating on Ballmer's part, 'we have more cash than you do, and it is not a problem,' is further evidence of their failure to accept reality.
You want to talk about corporate governance? Where's the board of Microsoft on this one? Why haven't they stripped Chairman/Chief Software Architect Bill and CEO Steve of their jobs on behalf of the shareholders who have suffered below-market returns for the past five years? Why haven't they forced the use, or dividending of, the bulk of the $34.8B cash on the firm's balance sheet?
Now, that would take some fortitude. Does the lead outside director of Microsoft have it? The "official" Microsoft website does not reveal who that would be. But here are a few of the "winners" currently on the firm's board: Dina Dublon, former CFO of the mediocre JPMorganChase; Ray Gilmartin, recently deposed...err..retired CEO of Merck; Charles Noski, former Vice-Chairman of AT&T, a firm which self-destructed through incompetent senior executive leadership and mismanagement. I don't think this crew will be challenging Chairman Bill anytime soon about which way to steer the foundering S.S. Microsoft.
Enron Lessons From Jim Chanos
Jim Chanos, one of the shorts whom Ken Lay fingered as having destroyed Enron, wrote a magnificent piece on the op-ed page of Tuesday's Wall Street Journal. I found three of his ten lessons from the Enron to fit with my own philosophies. They range from corporate governance to sell-side analysts, to CEO character. I'd like to share them in this piece.
Chanos' first point is one I've believed for many years. It is that we need something other than rule-based, SEC-required accounting systems and audits.
Today's audits are a joke. They are the minimum effort required to pass SEC muster and keep everyone's insurance premiums for malpractice within reason. If you've ever read the actual statement by the auditing firm on the average 10K, then you know it's virtually worthless to investors.
I suggested, post-Enron and Tyco, that the SEC repeal the requirement for auditing. Then encourage auditing and insurance firms to team up and offer "platinum standard" audits which truly protect and inform shareholders. The implication would be, were an S&P500 firm to decline to purchase such and audit, that the firm's management was concerned it would not be given the seal of approval.
However, on the "carrot" side, imagine how much shareholder value would be created by paying for and passing a really tough audit. An audit that came with meaningful insurance covering the financial statements' accuracy and authenticity?
Sadly, in our current regulatory climate, we have over-regulation of the wrong kind, which only serves to drive new listings and capital formation activity overseas. If the Chinese get this right, while we continue to "enforce" current processes, be very afraid.
The second point I liked in Jim Chanos' piece is about sell-side analysts. He says that they "...don't "do" complex."
So true. Actually, they don't do very much at all that isn't sales-related, Elliot Spitzer notwithstanding. Chanos focuses on the weakness of the system, whereby senior analysts defer to the junior ones for technical replies to their understanding of companies which they cover.
I should be careful what I wish for here, because the existence of such narrowly-focused, junior analyst corps, really makes my own job easier. Sector-focused analysts help reduce the chances that others will observe what I have about the actual performance of consistently superior companies.
However, so long as people actually listen to these sell-side Street analysts, Enron-like situations will occur.
Finally, Chanos speaks to character. This is so crucial. Look around at some of the sitting CEOs of America's large-cap companies: Jeff Immelt, Jamie Diamond and Bob Nardelli, to name a few. What are we to think of executives who gladly take excessive compensation for mediocre performance? Do you think that someone who does that is magically going to try harder in order to continue to be lavishly paid? Not likely.
CEO compensation has to be dramatically rethought. But it starts with boards of directors who actually have a stake in the company's performance. It's a character issue all the way around.
In any case, I found Chanos' comments to be a delightful read, and very shrewd.
Chanos' first point is one I've believed for many years. It is that we need something other than rule-based, SEC-required accounting systems and audits.
Today's audits are a joke. They are the minimum effort required to pass SEC muster and keep everyone's insurance premiums for malpractice within reason. If you've ever read the actual statement by the auditing firm on the average 10K, then you know it's virtually worthless to investors.
I suggested, post-Enron and Tyco, that the SEC repeal the requirement for auditing. Then encourage auditing and insurance firms to team up and offer "platinum standard" audits which truly protect and inform shareholders. The implication would be, were an S&P500 firm to decline to purchase such and audit, that the firm's management was concerned it would not be given the seal of approval.
However, on the "carrot" side, imagine how much shareholder value would be created by paying for and passing a really tough audit. An audit that came with meaningful insurance covering the financial statements' accuracy and authenticity?
Sadly, in our current regulatory climate, we have over-regulation of the wrong kind, which only serves to drive new listings and capital formation activity overseas. If the Chinese get this right, while we continue to "enforce" current processes, be very afraid.
The second point I liked in Jim Chanos' piece is about sell-side analysts. He says that they "...don't "do" complex."
So true. Actually, they don't do very much at all that isn't sales-related, Elliot Spitzer notwithstanding. Chanos focuses on the weakness of the system, whereby senior analysts defer to the junior ones for technical replies to their understanding of companies which they cover.
I should be careful what I wish for here, because the existence of such narrowly-focused, junior analyst corps, really makes my own job easier. Sector-focused analysts help reduce the chances that others will observe what I have about the actual performance of consistently superior companies.
However, so long as people actually listen to these sell-side Street analysts, Enron-like situations will occur.
Finally, Chanos speaks to character. This is so crucial. Look around at some of the sitting CEOs of America's large-cap companies: Jeff Immelt, Jamie Diamond and Bob Nardelli, to name a few. What are we to think of executives who gladly take excessive compensation for mediocre performance? Do you think that someone who does that is magically going to try harder in order to continue to be lavishly paid? Not likely.
CEO compensation has to be dramatically rethought. But it starts with boards of directors who actually have a stake in the company's performance. It's a character issue all the way around.
In any case, I found Chanos' comments to be a delightful read, and very shrewd.
Wednesday, May 31, 2006
New Tech Alliances- The Usual Suspects
Last Friday's Wall Street Journal's Section B featured the headline piece, "New Tech Alliances Signal More Scrambling Ahead." Indeed.
It seems to me that it pretty much reinforces the various shifts in momentum and strength that have been evident for the last few years. To wit, Google is attacking Microsoft by pressing its advantage with a weakened Dell. Dell will now ship Google software pre-loaded on the computers it sells.
Yahoo will sell ads on eBay pages in the US, and correspondingly promote the latter's PayPal service on its own site. On this one, I'd say two troubled non-competitors are allying to maintain strength while not heading in the other's direction. Yahoo doesn't do auctions, and eBay doesn't do broad-spectrum information services, email, ads, nor groups.
The most predictable one, of course, is Microsoft. It is buying MotionBridge, a company involved in search software for mobile phones. Ballmer and Gates, you've got to love them. Financial indicators, market share data, no empirical evidence will stop these two from having fun at their shareholders' expense, will it?
Of all the linkups mentioned in the WSJ piece, the only one that doesn't make sense is Microsoft's. It doesn't remove a major competitor. It doesn't strengthen an existing product/market position. It's a "hail Mary" pass reminiscent of the firm's acquisition of WebTV. Does anyone else recall that one? I think it sank out of sight about three years ago. It was supposed to be Microsoft's easy pole vault into the living room, via a wireless keyboard and your TV screen.
Overall, the usual suspects have behaved as expected. The smarties at Google have exploited someone else's weakness and made further inroads onto desktops. Yahoo and eBay, perennial second-tier tech giants, keep out of each other's way, perhaps mutually fend off Google a bit, and don't give away anything valuable for nothing. Only Microsoft continues to be the Lone Ranger, straying ever further from its simple core strengths of desktop operating systems, applications, and browsers.
I doubt that any of these deals will markedly change current trajectories for the companies involved. They may avert slower growth, in the case of Google. Or even, in the case of Yahoo and eBay, protect each a bit more from competitive threats by Google. For Microsoft, it's just another expensive step on the way downhill- business as usual.
It seems to me that it pretty much reinforces the various shifts in momentum and strength that have been evident for the last few years. To wit, Google is attacking Microsoft by pressing its advantage with a weakened Dell. Dell will now ship Google software pre-loaded on the computers it sells.
Yahoo will sell ads on eBay pages in the US, and correspondingly promote the latter's PayPal service on its own site. On this one, I'd say two troubled non-competitors are allying to maintain strength while not heading in the other's direction. Yahoo doesn't do auctions, and eBay doesn't do broad-spectrum information services, email, ads, nor groups.
The most predictable one, of course, is Microsoft. It is buying MotionBridge, a company involved in search software for mobile phones. Ballmer and Gates, you've got to love them. Financial indicators, market share data, no empirical evidence will stop these two from having fun at their shareholders' expense, will it?
Of all the linkups mentioned in the WSJ piece, the only one that doesn't make sense is Microsoft's. It doesn't remove a major competitor. It doesn't strengthen an existing product/market position. It's a "hail Mary" pass reminiscent of the firm's acquisition of WebTV. Does anyone else recall that one? I think it sank out of sight about three years ago. It was supposed to be Microsoft's easy pole vault into the living room, via a wireless keyboard and your TV screen.
Overall, the usual suspects have behaved as expected. The smarties at Google have exploited someone else's weakness and made further inroads onto desktops. Yahoo and eBay, perennial second-tier tech giants, keep out of each other's way, perhaps mutually fend off Google a bit, and don't give away anything valuable for nothing. Only Microsoft continues to be the Lone Ranger, straying ever further from its simple core strengths of desktop operating systems, applications, and browsers.
I doubt that any of these deals will markedly change current trajectories for the companies involved. They may avert slower growth, in the case of Google. Or even, in the case of Yahoo and eBay, protect each a bit more from competitive threats by Google. For Microsoft, it's just another expensive step on the way downhill- business as usual.
Lee Raymond's Exxon: Then and Now

Today's Exxon Mobil annual shareholder's meeting is providing a forum for the venting of anger regarding recently-retired CEO Lee Raymond's $400MM farewell compensation package.
My overall conclusion, based upon Exxon's failure to demonstrate consistently superior return performance over the period of Raymond's tenure as CEO, either as a high-growth, or low-growth company, is that he is being overpaid with this retirement package. As I've stated in several prior posts, I would simply sell the stock, if this really bothered me. In my case, though, I've already made an even stronger statement, by never buying Exxon stock in the first place.
Those who believe in "shareholder democracy," and that their withheld votes will change anything (as some state treasurer is reportedly doing today), are living in dreamland. Unless they can get some private equity firm to join them in controlling Exxon by way of a buyout, I don't think they are going to change the company all that much in the near future, from the outside. Perhaps their energy would be better spent finding other suitable companies in which to invest their capital, and depart the community of Exxon shareholders with their recent gains intact?
Or, they could heed my prior post regarding corporate governance reform, and attempt to change Exxon's board of directors, placing only those persons who hold millions of dollars of the stock bought with their own money in a position to oversee the CEO.
On the occasion of today's Exxon meeting, and the furor surrounding Raymond's payout, I did a little research on Exxon's performance, and the environment in which it has operated, going back some 25 years.
When I began working at AT&T in 1979, Exxon was still wrestling with its foray into telecommunications. The thinking back then was that oil was a business with limited future growth potential, so the firm should diversify into more promising businesses. I don't recall how many hundreds of millions of dollars Exxon poured into Exxon Enterprises, but suffice to say, the entire effort was shuttered within a decade. Even the alternative energy unit.
To say then, that Exxon has simply benefited from higher oil prices over the past 25 years is to misunderstand the number of business options available to the firm since the early 1980s, none of which they pursued, after the disastrous "diversification" program of the 1970s.
Rather, under Clifton Garvin, and then, Larry Rawl, the firm pared expenses, refocused on petroleum, and managed to survive in a world of $15/bbl oil. In fact, in articles I read this morning from that era, the firm was touted as very well managed simply for maintaining its income stream in the face of a very dismal market outlook for the forseeable future.
Following Rawl's departure, Lee Raymond took the helm, and merged with Mobil. Since then, the company has operated according to Raymond's signature style of tight expense management and cautious investment in refining and exploration.
However, looking at the Yahoo-sourced chart of Exxon's share price since 1970 shown above, you can see that most of the gains in the company's stock, versus the S&P500, are in brief bursts. Of course, there's a dividend payout that would increase the implied total return for Exxon. But assuming that's been relatively steady, the chart looks more like two ships tacking with each other in a race, than it does like some consistently outperforming company pulling ahead of the S&P over many years. The gap between the "ships" slowly narrows and widens over the years, but neither ever pulls decisively away from the other for very long.
I'm not disputing that Exxon has outperformed the index over a 35 year period. It has even clearly risen by much more than the index since 2000. However, it's not so much a consistent recent total return superiority as it is a few years of high returns.
From this perspective, nobody who has been CEO of Exxon since 1970 deserves a $400MM payout for a consistently superior job well done.
And, more to the point, would Lee Raymond have left early, or declined the CEO position, if he knew he would only receive, say, $50MM upon retirement?
Doubtful. It's not about the money for people who hold these positions. They'd do the job for far less, just to have that kind of power over an asset base of that size.
To me, the real culprits here, once again, are the board members, not the CEO. Exxon's board has unwisely squandered its shareholders' money when it almost certainly could have bought similar total return performance since 1993 for far less, even from Lee Raymond.
Tuesday, May 30, 2006
Fannie Mae's Financial Fraud
You have to hand it to Congress when it comes to finger-pointing.
Here we have Fannie Mae's erstwhile CEO, Franklin Raines, apparently guilty of brazen financial records manipulation to trigger massive senior executive bonus payments over several years, and Congress is livid over Lee Raymond's retirement package from ExxonMobil.
I find it troubling that we have the Federal government causing its own massive failure of "corporate governance," as well as "CEO compensation" reasonability, yet managing to turn a blind eye to the whole matter.
My friend B emailed me the 6-page abstract of the regulators' report concerning Raines & Co.'s financial chicanery. It was sickening to read. Fannie has extensive regulatory oversight, and with its access to our Federal government's implicit credit guarantees, should be much more tightly supervised. Instead, we have senior executive behavior that compares handsomely with Lay, Skilling and Fastow at Enron.
It's really a shame that the average US equity investor does not realize what went on at Fannie. Nor how complicit Congress is in not shining a bright light on the mess, and appropriately punishing those involved. Once again, we are treated to the sight of Federal government entities taking it easier on themselves and their colleagues than on the taxpaying public, whether individually or as corporations.
Raines was appointed by Clinton, a Democratic president. So it's not something the media and the House and/or Senate Democratic minority leadership can accuse Bush of arranging. Rather, it seems to continue to point up the basic weakness of allowing Fannie Mae and Freddie Mac access to the Treasury on such favorable terms. Then turning around and using that massive financial power to influence Congress, district by district, to continue to support the housing institutions, or explain the presumed dearth of home mortgage funding availability to their constituents.
The whole mess should be ripped out by the roots, while allowing the substantial private mortgage lending sector to step up to replace Fannie Mae with competitive products at competitive prices, breaking the link between individual housing finance and Congressional largesse.
Here we have Fannie Mae's erstwhile CEO, Franklin Raines, apparently guilty of brazen financial records manipulation to trigger massive senior executive bonus payments over several years, and Congress is livid over Lee Raymond's retirement package from ExxonMobil.
I find it troubling that we have the Federal government causing its own massive failure of "corporate governance," as well as "CEO compensation" reasonability, yet managing to turn a blind eye to the whole matter.
My friend B emailed me the 6-page abstract of the regulators' report concerning Raines & Co.'s financial chicanery. It was sickening to read. Fannie has extensive regulatory oversight, and with its access to our Federal government's implicit credit guarantees, should be much more tightly supervised. Instead, we have senior executive behavior that compares handsomely with Lay, Skilling and Fastow at Enron.
It's really a shame that the average US equity investor does not realize what went on at Fannie. Nor how complicit Congress is in not shining a bright light on the mess, and appropriately punishing those involved. Once again, we are treated to the sight of Federal government entities taking it easier on themselves and their colleagues than on the taxpaying public, whether individually or as corporations.
Raines was appointed by Clinton, a Democratic president. So it's not something the media and the House and/or Senate Democratic minority leadership can accuse Bush of arranging. Rather, it seems to continue to point up the basic weakness of allowing Fannie Mae and Freddie Mac access to the Treasury on such favorable terms. Then turning around and using that massive financial power to influence Congress, district by district, to continue to support the housing institutions, or explain the presumed dearth of home mortgage funding availability to their constituents.
The whole mess should be ripped out by the roots, while allowing the substantial private mortgage lending sector to step up to replace Fannie Mae with competitive products at competitive prices, breaking the link between individual housing finance and Congressional largesse.
Monday, May 29, 2006
Jack Welch's Spawn: Nardelli's and Immelt's Pay & Performances
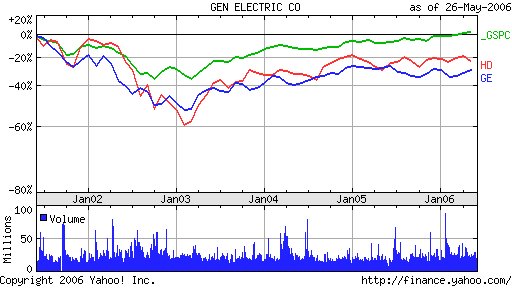
Last week saw a shareholder furor over the combination of Bob Nardelli's recent compensation as CEO of Home Depot with the stock's performance since he assumed the helm.
According to the Wall Street Journal, Nardelli "has received more than $100MM in salary, bonuses and stock awards, plus millions of dollars more in stock options, while the share price of Home Depot has declined by 12% during the same period." On Thursday of last week, every company director, except Nardelli, skipped the Home Depot annual shareholder's meeting. And Nardelli declined to answer questions regarding his compensation, ending the meeting after only 30 minutes.
What struck me, though, is how similar Nardelli is to the other famous spawn of Jack Welch's GE tenure- current GE CEO Jeff Immelt.
I've pasted a Yahoo chart of the two companies' stock price performances over the last five years, compared with the S&P500. For more details about Immelt's compensation, see my post here, entitled "Rewarding Losers- GE," written this past March.
Look at how similar the Home Depot and GE stock price paths are. It's almost like they are in the same industry. But they're not. Their two shared attributes are that each is headed by a former candidate for CEO of GE, and each company has paid it's former GE senior exec (in Immelt's case, now GE CEO and Chairman) handsomely to underperform the S&P500.
Not a single long-serving, large-cap US CEO who was a senior executive at Welch's side at GE comes to my mind as successful at delivering consistently superior total returns for his shareholders.
What gives? Is this perhaps the real legacy of "Neutron Jack" Welch? To teach his lieutenants how to run mediocre companies while being egregiously overpaid relative to the value built...err..make that destroyed?
Friday, May 26, 2006
Frank Talk: Barney Frank's Scary Comments on CEO Compensation
Barney Frank, US Representative from Massachusetts, appeared on CNBC the other day to discuss his views on CEO compensation.
Being the extremely liberal Democrat that he is, it's difficult to enumerate all of the nonsense that he spouted in a ten minute interview. However, a few examples serve to illustrate what we are in for if the Democrats regain the House later this year.
Bob Nardelli's pay package as CEO of Home Depot touched off this past week's firestorm over CEO compensation. The company's stock has struggled recently, after plunging during Nardelli's early years as CEO. If I recall correctly, he joined Home Depot some five years ago, when it became clear he would not be replacing Jack Welch as CEO of General Electric.
Frank is so ill-informed regarding performance metrics that he voiced the opinion that perhaps CEOs should be compensated on the basis of 'net revenues or market share.' Apparently his staff is as clueless as Frank is, because neither measure of corporate performance makes sense. Market share is notoriously difficult to calculate effectively, since it can vary by market segment, and makes no sense whatsoever for a multi-product company. Paying a CEO for increasing revenues is simply idiocy. If you think we've seen fraud recently, you haven't seen anything yet if Frank's suggestion becomes law.
What I found most interesting, however, was his diametrically opposing view to mine of what realistic options are available to minority shareholders of public companies. Frank expounded on the lack of "shareholder democracy" implicit in the advice that shareholders who don't like the performance or CEO pay policies of a company sell their shares. I remain unable to understand this.
Why do so many people, Frank included, believe that any minority shareholder with as little as one share of stock, should have the right to set corporate policies? The ability to easily and inexpensively sell your stock when you don't like what a company is doing is a benefit of our capitalist system in the US, not a weakness. In addition, it is not as if most shareholders founded the company, then lost control. No, they typically buy into a company whose prospects they deem attractive. But they know going in that they do not control anything.
Perhaps the most fear-inspiring comments from Frank were about the need for federal government interference in the affairs of publicly-traded companies in the US. He seems to feel that their "rights" need protecting, because selling shares in a company with whose policies a shareholder disagrees is viewed by the Congressman as "undemocratic." Nevermind that liquidity in most publicly-traded shares is more than adequate to allow a shareholder to exit an unwanted stock.
It seems that Frank, along many other critics, have the mistaken notion that minority shareholders control the policies of corporations in which they own shares. In reality, in our system, minority shareholders get the benefit of the performance of companies whose shares they hold. And they may vote on candidates for the board of directors. But that's it. They don't own controlling interests, and most of them did not found the company. They know the limitations of their position going into the stock purchase. And, most importantly, there are many other companies whose stock they may buy if they become disenchanted with the shares they own.
How much worse it would be if there were no liquid, inexpensive markets in which to simply sell unwanted positions and be rid of corporate situations with which one disagrees.
From his comments the other day on CNBC, my sense is that if Frank ever becomes chairman of the House committee on which he serves (I believe it is Finance), Sarbanes-Oxley will become the lesser of our worries regarding unwanted Federal intrusion into private enterprise.
Being the extremely liberal Democrat that he is, it's difficult to enumerate all of the nonsense that he spouted in a ten minute interview. However, a few examples serve to illustrate what we are in for if the Democrats regain the House later this year.
Bob Nardelli's pay package as CEO of Home Depot touched off this past week's firestorm over CEO compensation. The company's stock has struggled recently, after plunging during Nardelli's early years as CEO. If I recall correctly, he joined Home Depot some five years ago, when it became clear he would not be replacing Jack Welch as CEO of General Electric.
Frank is so ill-informed regarding performance metrics that he voiced the opinion that perhaps CEOs should be compensated on the basis of 'net revenues or market share.' Apparently his staff is as clueless as Frank is, because neither measure of corporate performance makes sense. Market share is notoriously difficult to calculate effectively, since it can vary by market segment, and makes no sense whatsoever for a multi-product company. Paying a CEO for increasing revenues is simply idiocy. If you think we've seen fraud recently, you haven't seen anything yet if Frank's suggestion becomes law.
What I found most interesting, however, was his diametrically opposing view to mine of what realistic options are available to minority shareholders of public companies. Frank expounded on the lack of "shareholder democracy" implicit in the advice that shareholders who don't like the performance or CEO pay policies of a company sell their shares. I remain unable to understand this.
Why do so many people, Frank included, believe that any minority shareholder with as little as one share of stock, should have the right to set corporate policies? The ability to easily and inexpensively sell your stock when you don't like what a company is doing is a benefit of our capitalist system in the US, not a weakness. In addition, it is not as if most shareholders founded the company, then lost control. No, they typically buy into a company whose prospects they deem attractive. But they know going in that they do not control anything.
Perhaps the most fear-inspiring comments from Frank were about the need for federal government interference in the affairs of publicly-traded companies in the US. He seems to feel that their "rights" need protecting, because selling shares in a company with whose policies a shareholder disagrees is viewed by the Congressman as "undemocratic." Nevermind that liquidity in most publicly-traded shares is more than adequate to allow a shareholder to exit an unwanted stock.
It seems that Frank, along many other critics, have the mistaken notion that minority shareholders control the policies of corporations in which they own shares. In reality, in our system, minority shareholders get the benefit of the performance of companies whose shares they hold. And they may vote on candidates for the board of directors. But that's it. They don't own controlling interests, and most of them did not found the company. They know the limitations of their position going into the stock purchase. And, most importantly, there are many other companies whose stock they may buy if they become disenchanted with the shares they own.
How much worse it would be if there were no liquid, inexpensive markets in which to simply sell unwanted positions and be rid of corporate situations with which one disagrees.
From his comments the other day on CNBC, my sense is that if Frank ever becomes chairman of the House committee on which he serves (I believe it is Finance), Sarbanes-Oxley will become the lesser of our worries regarding unwanted Federal intrusion into private enterprise.
Enron, Worldcom, et al: Innovation vs. Total Prevention of White-Collar Crime
I suppose I have to write something about the biggest business news story on the planet yesterday- the convictions of Jeff Skilling and Ken Lay for their Enron crimes.
Here's what I find noteworthy on this "morning after."
Watching Sharon Watkins appear on CNBC this morning, I found myself wondering what the cost to our economy will be, in terms of future dynamism and creative growth, from Sarbanes-Oxley?
Several commentators yesterday solemnly intoned how the Enron verdicts provided the matching "bookend" to the decade of greed and excess that was the 1990s. Then, some other pundits, in response to questions from the talking (air)heads on CNBC's afternoon programs about "is this finally the end of corporate wrongdoing and scandals?" noted that all periods of explosive economic activity and growth beget some excesses. Excesses which are typically found, later, to be illegal.
What concerns me is this. Do we know, empirically, that the illegal "excesses" of the 1990s were above-average in the damage they caused? Can anyone really legislate a priori the total proscription of illegal behavior?
Doesn't it really boil down to the ethical values of the CEOs in charge of public companies? Sharon Watkins spoke about being a "whistleblower" with real passion and angst. I've never worked in a company which commited fraud while I was there. But I can attest to the general climate of which Watkins spoke. She told of being pulled aside by Andy Fastow, Enron's CFO, and told to keep her nose out of accounting business that was not her job. She thereupon transferred to another division. Charlie Gasparino then chastised Watkins by asking something like, 'shouldn't you have really done more, gone public, instead of transferring at that point?'
How presumptuous and pompous of Gasparino to be so judgmental. Anyone who's put serious time in with a large company knows that it is far harder to explicitly and vocally tack away from the corporate course and risk dismissal and loss of income, than it is to just find another place to hang out and do something for a paycheck. Nobody who is not independently wealthy, and does not actually commit a crime, deserves to be questioned and judged like Gasparino and a few of his colleagues did with Sharon Watkins this morning on CNBC. I hate to put it this way, but watching her this morning, it was hard not to compare CNBC's treatment of her to a rape victim being asked if she didn't conspire in the crime.
Drawing these themes together, I simply wonder if we are not making Enron, Worldcom, et al, into mountains of larger size than they actually were. Are we sure that, given the business activity and benefits of the 1990s, the consequent damage done by these corporate frauds is historically "excessive?" Their faults were, at bottom, unethical CEOs and sleepy boards. Now, several CEOs will be in jail for a very long time. If this doesn't give pause to sitting CEOs, will Sarbanes-Oxley? Which, as we all know, was not in existence when the crimes for which Ebbers, Skilling and Lay have been convicted were commited.
Our dynamic economy creates explosive, creative growth. Sometimes, things get out of hand. Nobody can stop white-collar crime before it even gets started. Even whistleblowers like Sharon Watkins are sceptically treated after the fact. It's just not philosophically compatible with our American system to presume people guilty of unethical or criminal behavior before the fact. We punish when we find the crime- not before it's commited. And who among us believes you can somehow legislate a person to have better ethics than they already have as they become a CEO?
Let's hope the effect of Sarbanes-Oxley is not to starve our better new ventures of capital in the public markets. Let's hope it doesn't drive creative enterprise into private equity forever, damping publicly-accessible returns for the average American investor. And, most of all, let's hope Sarbanes-Oxley doesn't have a long term dampening effect upon American entrepreneurship, creativity, and economic value creation. Because if it does, we've just handed the rest of the world our heretofore economic leadership on a silver platter.
Here's what I find noteworthy on this "morning after."
Watching Sharon Watkins appear on CNBC this morning, I found myself wondering what the cost to our economy will be, in terms of future dynamism and creative growth, from Sarbanes-Oxley?
Several commentators yesterday solemnly intoned how the Enron verdicts provided the matching "bookend" to the decade of greed and excess that was the 1990s. Then, some other pundits, in response to questions from the talking (air)heads on CNBC's afternoon programs about "is this finally the end of corporate wrongdoing and scandals?" noted that all periods of explosive economic activity and growth beget some excesses. Excesses which are typically found, later, to be illegal.
What concerns me is this. Do we know, empirically, that the illegal "excesses" of the 1990s were above-average in the damage they caused? Can anyone really legislate a priori the total proscription of illegal behavior?
Doesn't it really boil down to the ethical values of the CEOs in charge of public companies? Sharon Watkins spoke about being a "whistleblower" with real passion and angst. I've never worked in a company which commited fraud while I was there. But I can attest to the general climate of which Watkins spoke. She told of being pulled aside by Andy Fastow, Enron's CFO, and told to keep her nose out of accounting business that was not her job. She thereupon transferred to another division. Charlie Gasparino then chastised Watkins by asking something like, 'shouldn't you have really done more, gone public, instead of transferring at that point?'
How presumptuous and pompous of Gasparino to be so judgmental. Anyone who's put serious time in with a large company knows that it is far harder to explicitly and vocally tack away from the corporate course and risk dismissal and loss of income, than it is to just find another place to hang out and do something for a paycheck. Nobody who is not independently wealthy, and does not actually commit a crime, deserves to be questioned and judged like Gasparino and a few of his colleagues did with Sharon Watkins this morning on CNBC. I hate to put it this way, but watching her this morning, it was hard not to compare CNBC's treatment of her to a rape victim being asked if she didn't conspire in the crime.
Drawing these themes together, I simply wonder if we are not making Enron, Worldcom, et al, into mountains of larger size than they actually were. Are we sure that, given the business activity and benefits of the 1990s, the consequent damage done by these corporate frauds is historically "excessive?" Their faults were, at bottom, unethical CEOs and sleepy boards. Now, several CEOs will be in jail for a very long time. If this doesn't give pause to sitting CEOs, will Sarbanes-Oxley? Which, as we all know, was not in existence when the crimes for which Ebbers, Skilling and Lay have been convicted were commited.
Our dynamic economy creates explosive, creative growth. Sometimes, things get out of hand. Nobody can stop white-collar crime before it even gets started. Even whistleblowers like Sharon Watkins are sceptically treated after the fact. It's just not philosophically compatible with our American system to presume people guilty of unethical or criminal behavior before the fact. We punish when we find the crime- not before it's commited. And who among us believes you can somehow legislate a person to have better ethics than they already have as they become a CEO?
Let's hope the effect of Sarbanes-Oxley is not to starve our better new ventures of capital in the public markets. Let's hope it doesn't drive creative enterprise into private equity forever, damping publicly-accessible returns for the average American investor. And, most of all, let's hope Sarbanes-Oxley doesn't have a long term dampening effect upon American entrepreneurship, creativity, and economic value creation. Because if it does, we've just handed the rest of the world our heretofore economic leadership on a silver platter.
Actual Volatility in Equity Markets
I saw an interesting exchange the other day on CNBC. Dylan Ratigan was cross-examining some poor analyst or CEO in connection with avian flu worries and pharma or food stocks. I really don't recall which it was.
What I do recall, however, was Ratigan's comment that flustered his poor guest. It was something very close to this, "....c'mon, the stock moved 6% in one day! Stocks don't usually do that!...what's going on there?"
Well, actually, yes, I think they do "do that," Dylan. Maybe you need to watch individual stock volatilities more often, to stay in touch with how wild the equity markets have become lately.
For example, I have a portfolio of twenty-one equities. Looking at yesterday's results, one rose over 4%, and another over 5%. Neither had particularly significant news that day. Another stock was within a hair of a 4% gain.
I've seen 6% daily moves, too. Recently. Especially with the large market moves of the past few weeks. I don't keep daily change records, but my point is this. Daily price volatility can actually be pretty large now. Remember Microsoft's loss of 11% of its value in just one day, for reporting higher-than-expected expenses?
I find it rather ironic that an anchor for a business entertainment network, CNBC, which stressed daily reporting, if not hourly reporting, would be so insensitive to the realities of daily stock price volatility in this environment.
What I do recall, however, was Ratigan's comment that flustered his poor guest. It was something very close to this, "....c'mon, the stock moved 6% in one day! Stocks don't usually do that!...what's going on there?"
Well, actually, yes, I think they do "do that," Dylan. Maybe you need to watch individual stock volatilities more often, to stay in touch with how wild the equity markets have become lately.
For example, I have a portfolio of twenty-one equities. Looking at yesterday's results, one rose over 4%, and another over 5%. Neither had particularly significant news that day. Another stock was within a hair of a 4% gain.
I've seen 6% daily moves, too. Recently. Especially with the large market moves of the past few weeks. I don't keep daily change records, but my point is this. Daily price volatility can actually be pretty large now. Remember Microsoft's loss of 11% of its value in just one day, for reporting higher-than-expected expenses?
I find it rather ironic that an anchor for a business entertainment network, CNBC, which stressed daily reporting, if not hourly reporting, would be so insensitive to the realities of daily stock price volatility in this environment.
Thursday, May 25, 2006
Toyota's & GM's Texas Plants
Wednesday's Wall Street Journal featured an article comparing the Texas production plants of GM and Toyota. The overall conclusion was that, although GM's facility is its most "efficient" one, it is still running behind Toyota's newer one.
I have a couple of observations.
The first one involves barriers to entry. If you don't already see auto production and marketing as a low barrier-to-entry business, and, thus, a business tending toward commoditization, this piece ought to be your wake-up call.
It reminds me of a business in which I was engaged to troubleshoot at Chase Manhattan Bank years ago. The master trust and custody business was primarily an IT activity. It involved electronic record-keeping of pension funds and the associated assets, as well as handling the interfaces for trustees (the companies with the pension plans) with their designated asset managers (the money management funds actually managing the pension assets). What we found back in the 1980s was that any bank could, if it so chose, invest sufficiently to develop a newer, more feature-laden system, and begin to take share from existing providers with older, more antiquated capabilities. At the time, Bankers Trust was doing just that, and taking share from the weaker players in the marketplace.
This awareness informed us, the corporate planning strategic troubleshooters for the bank, that the pension trust and custody business was going to have some natural limits to ROI, due to the need for ongoing investment. Thus, any value-adding edge we hoped to create and sustain was going to have to be from growth. Margins were always going to be under pressure due to significant ongoing systems developments and upgrades.
The WSJ piece on the auto plants reminded me of this. If all it took to best GM's best plant was a slightly more forward-looking perspective by Toyota, then GM investors crowing about this week's temporary stock price reprieve should take a really good look at this story about the Texas facilities.
Legacy issues are fact. I've written about this in connection with technology companies last fall. Now, we see it in something as mundane as auto production.
A related topic mentioned in the article is how the writers chose to treat the "productivity" of the two plants. For my views, see this post, and this one as well.
In one paragraph, they discuss the labor hours per vehicle at the GM plant. Later, they note that, when actual labor rates, meaning unionized wages and substantial GM overhead, are applied, Toyota's newer plant wins, hands down.
My question is, why even bother with hours/vehicle? That's "efficiency," not "productivity." Productivity implies value, and even adding labor costs doesn't totally reflect the "productivity" in terms of value-added to the vehicle, and its salability. For arguments' sake, let's agree that the GM vehicles in question are very salable, for now.
My overall impression is that the article provides a rather useful anecdote as to just how much continuing trouble GM has on its hands. Like it or not, being the one-time share leader in a business that benefits from at least one entrant's continuing drive for improvements- in product, production processes, etc- can cause existing market leaders to simply crumple from inertia.
So, for what it's worth.....that GM stock price rise this week? Well, I don't hold the stock to begin with. If I did, after reading this WSJ piece, I'd be thinking profit taking. There are plenty of better opportunities for less-risky investment gains than GM right now.
But maybe that's just me....
I have a couple of observations.
The first one involves barriers to entry. If you don't already see auto production and marketing as a low barrier-to-entry business, and, thus, a business tending toward commoditization, this piece ought to be your wake-up call.
It reminds me of a business in which I was engaged to troubleshoot at Chase Manhattan Bank years ago. The master trust and custody business was primarily an IT activity. It involved electronic record-keeping of pension funds and the associated assets, as well as handling the interfaces for trustees (the companies with the pension plans) with their designated asset managers (the money management funds actually managing the pension assets). What we found back in the 1980s was that any bank could, if it so chose, invest sufficiently to develop a newer, more feature-laden system, and begin to take share from existing providers with older, more antiquated capabilities. At the time, Bankers Trust was doing just that, and taking share from the weaker players in the marketplace.
This awareness informed us, the corporate planning strategic troubleshooters for the bank, that the pension trust and custody business was going to have some natural limits to ROI, due to the need for ongoing investment. Thus, any value-adding edge we hoped to create and sustain was going to have to be from growth. Margins were always going to be under pressure due to significant ongoing systems developments and upgrades.
The WSJ piece on the auto plants reminded me of this. If all it took to best GM's best plant was a slightly more forward-looking perspective by Toyota, then GM investors crowing about this week's temporary stock price reprieve should take a really good look at this story about the Texas facilities.
Legacy issues are fact. I've written about this in connection with technology companies last fall. Now, we see it in something as mundane as auto production.
A related topic mentioned in the article is how the writers chose to treat the "productivity" of the two plants. For my views, see this post, and this one as well.
In one paragraph, they discuss the labor hours per vehicle at the GM plant. Later, they note that, when actual labor rates, meaning unionized wages and substantial GM overhead, are applied, Toyota's newer plant wins, hands down.
My question is, why even bother with hours/vehicle? That's "efficiency," not "productivity." Productivity implies value, and even adding labor costs doesn't totally reflect the "productivity" in terms of value-added to the vehicle, and its salability. For arguments' sake, let's agree that the GM vehicles in question are very salable, for now.
My overall impression is that the article provides a rather useful anecdote as to just how much continuing trouble GM has on its hands. Like it or not, being the one-time share leader in a business that benefits from at least one entrant's continuing drive for improvements- in product, production processes, etc- can cause existing market leaders to simply crumple from inertia.
So, for what it's worth.....that GM stock price rise this week? Well, I don't hold the stock to begin with. If I did, after reading this WSJ piece, I'd be thinking profit taking. There are plenty of better opportunities for less-risky investment gains than GM right now.
But maybe that's just me....
Wednesday, May 24, 2006
More Confusion from the WSJ: Creativity vs. Management
Yesterday's Wall Street Journal was a motherlode of interesting articles on which to comment.
The first is Lee Gomes' follow up to the Gates-Otellini op-ed letter in the Journal last week. That letter was their "reply" to comments by Journal technology reviewer Walt Mossberg's comments on the relative merits and status of Apple's "closed" design system vs. WinTel's "open" system. I wrote some thoughts about the Gatellini letter here.
Gomes stated that he would "like to play the peacemaker in a debate kicking around in these pages over the past few weeks." He then goes on to describe the prior written pieces, and their positions.
I don't like to seem to be harsh on any one person, but I have to say, this is the second article in a row from Gomes, whom I usually enjoy reading, that simply contains shallow thinking.
Consider the title of his piece yesterday, "Above All Else, Rivals of Apple Mostly Need Some Design Mojo."
Really? Indeed! How wonderfully simple to fix. Just call a few industrial designers, and Microsoft is back on track to consistently superior return performance for the rest of this decade. Same for intel, eh?
I don't think so. No, it runs far deeper. Like product strategy, choice of arenas in which to compete, and corporate sizes so large as to insulate the senior executives from a meaningful appreciation of the amount of value destruction that continued mediocrity will cause.
I found Gomes' last paragraph to be the most telling evidence of his misunderstanding of what has been going on in this situation. He writes,
"Apple has worked hard in recent years to adopt some of the business-process efficiencies that the Wintel companies have long taken for granted. Its rivals, then, ought to be able to make themselves a little more creative."
Again, it's not that simple. I have undertaken proprietary research on the occurences and sources of consistently superior total return performance among large-cap companies. My findings have shown that innovation and creativity are the most unique, important attribute of such companies. Whereas expense and process management are fairly easy to hire and implement, true innovation and creative product development, which drive consistently superior revenue growth, appear to be the rare talents.
Therefore, it's not going to be very easy for Microsoft and Intel, at their size, and with their bloated bureaucracies, to simply "make themselves a little more creative." Not when Chairman Bill is the self-ordained "chief software architect" of his software empire. As I have written prior to this, if Microsoft is to break historic patterns, it probably has to seed entirely new companies. For more on this, see my piece on new style corporate governance.
To close, I remain disappointed that the WSJ continues to pump out such shallow and badly-conceived ideas about business strategy. I doubt it would have taken more than a few phone calls to business colleagues for Lee Gomes to be disabused of his notion that, just like process efficiency improvements, creativity can be easily hired or "managed" on demand.
It cannot. And that, dear readers, is why Steve Jobs' Apple is running (profitably) loose among product/markets no other PC software or hardware providers can even begin to consider. He has a natural flair and appreciation for design and usage that Bill Gates has never displayed. And in the current environment, that now matters.
The first is Lee Gomes' follow up to the Gates-Otellini op-ed letter in the Journal last week. That letter was their "reply" to comments by Journal technology reviewer Walt Mossberg's comments on the relative merits and status of Apple's "closed" design system vs. WinTel's "open" system. I wrote some thoughts about the Gatellini letter here.
Gomes stated that he would "like to play the peacemaker in a debate kicking around in these pages over the past few weeks." He then goes on to describe the prior written pieces, and their positions.
I don't like to seem to be harsh on any one person, but I have to say, this is the second article in a row from Gomes, whom I usually enjoy reading, that simply contains shallow thinking.
Consider the title of his piece yesterday, "Above All Else, Rivals of Apple Mostly Need Some Design Mojo."
Really? Indeed! How wonderfully simple to fix. Just call a few industrial designers, and Microsoft is back on track to consistently superior return performance for the rest of this decade. Same for intel, eh?
I don't think so. No, it runs far deeper. Like product strategy, choice of arenas in which to compete, and corporate sizes so large as to insulate the senior executives from a meaningful appreciation of the amount of value destruction that continued mediocrity will cause.
I found Gomes' last paragraph to be the most telling evidence of his misunderstanding of what has been going on in this situation. He writes,
"Apple has worked hard in recent years to adopt some of the business-process efficiencies that the Wintel companies have long taken for granted. Its rivals, then, ought to be able to make themselves a little more creative."
Again, it's not that simple. I have undertaken proprietary research on the occurences and sources of consistently superior total return performance among large-cap companies. My findings have shown that innovation and creativity are the most unique, important attribute of such companies. Whereas expense and process management are fairly easy to hire and implement, true innovation and creative product development, which drive consistently superior revenue growth, appear to be the rare talents.
Therefore, it's not going to be very easy for Microsoft and Intel, at their size, and with their bloated bureaucracies, to simply "make themselves a little more creative." Not when Chairman Bill is the self-ordained "chief software architect" of his software empire. As I have written prior to this, if Microsoft is to break historic patterns, it probably has to seed entirely new companies. For more on this, see my piece on new style corporate governance.
To close, I remain disappointed that the WSJ continues to pump out such shallow and badly-conceived ideas about business strategy. I doubt it would have taken more than a few phone calls to business colleagues for Lee Gomes to be disabused of his notion that, just like process efficiency improvements, creativity can be easily hired or "managed" on demand.
It cannot. And that, dear readers, is why Steve Jobs' Apple is running (profitably) loose among product/markets no other PC software or hardware providers can even begin to consider. He has a natural flair and appreciation for design and usage that Bill Gates has never displayed. And in the current environment, that now matters.
Carly Fiorina, H-P & Corporate Governance
Alan Murray of the Wall Street Journal wrote an excellent piece this morning about H-P's recent performance, and how it relates to the firm's ex-CEO.
In further comments on CNBC this morning, as Alan usually does to follow-up on his weekly column, he aptly fended off inquiries from the guest-host, Herb Greenberg, regarding the wisdom of the Compaq-H-P merger. What Alan pointed out is that, while sales may not have increased by more than simple addition because of the merger, expenses clearly fell from scale economies.
My ears perked at this, because it dovetails with my own research. In slower-growth companies, ROI matters a lot for achieving consistently superior total returns. And a big part of that comes from expense base management, since, by definition in a slower-growth company, it won't be coming from revenue growth.
Alan further pointed out that the board members backed the merger, but not, ultimately, Carly's personal and professional management style.
I again perked at this. What Alan Murray is really saying, without naming it, is that H-P's board did the unheralded right thing of dumping a problematic CEO and replacing her with one who focused on what they felt was critical for H-P at this time. That's a rare thing, despite the recent years of lackluster total returns at H-P.
So, for once, we have actually witnessed some effective "corporate governance" by a board that took action to benefit shareholders, without some scandal forcing them to do it. Maybe the system can work- it just takes the right board.
In further comments on CNBC this morning, as Alan usually does to follow-up on his weekly column, he aptly fended off inquiries from the guest-host, Herb Greenberg, regarding the wisdom of the Compaq-H-P merger. What Alan pointed out is that, while sales may not have increased by more than simple addition because of the merger, expenses clearly fell from scale economies.
My ears perked at this, because it dovetails with my own research. In slower-growth companies, ROI matters a lot for achieving consistently superior total returns. And a big part of that comes from expense base management, since, by definition in a slower-growth company, it won't be coming from revenue growth.
Alan further pointed out that the board members backed the merger, but not, ultimately, Carly's personal and professional management style.
I again perked at this. What Alan Murray is really saying, without naming it, is that H-P's board did the unheralded right thing of dumping a problematic CEO and replacing her with one who focused on what they felt was critical for H-P at this time. That's a rare thing, despite the recent years of lackluster total returns at H-P.
So, for once, we have actually witnessed some effective "corporate governance" by a board that took action to benefit shareholders, without some scandal forcing them to do it. Maybe the system can work- it just takes the right board.
Maria Bartiromo's Fed Appointment Reversed
It's official. In testimony before a Senate committee earlier this week, Ben Bernanke retracted his remarks to Maria Bartiromo, upon specific questioning of the incident by Senator (former perfect game hurler) Jim Bunning of Kentucky.
In a rather muted moment, Bernanke muttered that he had a lapse of judgment concerning speaking to the CNBC talking head about his and the Fed's true intentions with respect to rate hikes.
Thank goodness! Sanity prevails, and Maria's not un unofficial member of the Open Market Committee after all.
In a rather muted moment, Bernanke muttered that he had a lapse of judgment concerning speaking to the CNBC talking head about his and the Fed's true intentions with respect to rate hikes.
Thank goodness! Sanity prevails, and Maria's not un unofficial member of the Open Market Committee after all.
Monday, May 22, 2006
Some Common Sense About Interest Rates & Current Market Conditions
Rick Santelli, CNBC's Chicago reporter on the commodities and options markets there, has been in its New Jersey studios recently. What a breath of fresh air! I swear, this guy should be anchored there all the time.
I periodically castigate the network for focusing on the "action" on the floor of the NYSE, when the real decisions regarding equities are made in institutional money management offices across the country and globe. However, with fixed income, it's slightly different.
Bonds, particularly Treasuries, are a mathematical play. Pure and simple. In fact, one business partner of mine, my friend Bob, has opined that equities are the wild west, where any valuation can happen, without a clear cause. Fixed income, on the other hand, which is where Bob spent much of his productive career, are all math, and very understandable.
Santelli does a really wonderful job explaining the market forces at work while the camera shows the trading pits of Chicago in the background. Unlike, say, Bob Pisani, who looks up at some market stats board on the floor of the NYSE, then makes up his own story about why "the market" is doing something, Santelli calmly explains how the math of interest rates and inflation are pushing bond prices around, and affecting the term structure of the yield curve.
Thus, his remarks over the past few days have been calming, albeit delivered from a desk on CNBC's New Jersey set. He essentially said that a rise in rates from 5% to 5 1/2% was hardly enough to justify all the carnage recently seen as a result of inflation expectations. I think he is right. His calm explanation of the recent moves, and probably long term affects, seemed very reasoned and sensible.
Later that same day, CNBC had Gail Dudak, one-time frequent guest of the late Lou Rukeyser, on as an equity markets commentator. She made a number of clear and reasonable points as well. In particular, when asked if we are now seeing the beginning of a bear market, she said, "no." She likened these past few weeks to last Spring and October, when there were temporary market drops due to unfounded worries over various economic problems. I recall October's roiled markets clearly, as they came as a partial result of Katrina's then-uncertain effect on the US economy.
Overall, these two people, Santelli and Dudak, provided with clear, reasoned and believable analysis. Admittedly, it reinforced my own beliefs, but they had different perspectives, which was important.
I think that, once again, we are witnessing a market which is in the throes of misinterpretation of economic data by a lot of inept seat-warmers in the money management sector.
I periodically castigate the network for focusing on the "action" on the floor of the NYSE, when the real decisions regarding equities are made in institutional money management offices across the country and globe. However, with fixed income, it's slightly different.
Bonds, particularly Treasuries, are a mathematical play. Pure and simple. In fact, one business partner of mine, my friend Bob, has opined that equities are the wild west, where any valuation can happen, without a clear cause. Fixed income, on the other hand, which is where Bob spent much of his productive career, are all math, and very understandable.
Santelli does a really wonderful job explaining the market forces at work while the camera shows the trading pits of Chicago in the background. Unlike, say, Bob Pisani, who looks up at some market stats board on the floor of the NYSE, then makes up his own story about why "the market" is doing something, Santelli calmly explains how the math of interest rates and inflation are pushing bond prices around, and affecting the term structure of the yield curve.
Thus, his remarks over the past few days have been calming, albeit delivered from a desk on CNBC's New Jersey set. He essentially said that a rise in rates from 5% to 5 1/2% was hardly enough to justify all the carnage recently seen as a result of inflation expectations. I think he is right. His calm explanation of the recent moves, and probably long term affects, seemed very reasoned and sensible.
Later that same day, CNBC had Gail Dudak, one-time frequent guest of the late Lou Rukeyser, on as an equity markets commentator. She made a number of clear and reasonable points as well. In particular, when asked if we are now seeing the beginning of a bear market, she said, "no." She likened these past few weeks to last Spring and October, when there were temporary market drops due to unfounded worries over various economic problems. I recall October's roiled markets clearly, as they came as a partial result of Katrina's then-uncertain effect on the US economy.
Overall, these two people, Santelli and Dudak, provided with clear, reasoned and believable analysis. Admittedly, it reinforced my own beliefs, but they had different perspectives, which was important.
I think that, once again, we are witnessing a market which is in the throes of misinterpretation of economic data by a lot of inept seat-warmers in the money management sector.
What An Analyst Does
Today's Wall Street Journal features a section on "star" equity analysts.
As I read the first page of the section, seeking to understand the bases on which analysts were evaluated, I learned the following. Analysts are apparently judged on their ability to produce a best "buy" or "sell" recommendation, in terms of total return.
At first glance, this might seem appropriate. But it seems to me to run counter to what I have been led to believe analysts are supposed to do.
First, measuring an analyst on their one best recommendation seems akin to awarding a batting title in baseball to the hitter with the single longest home run. It doesn't count the other recommendations, or the average performance of all recommendations, etc. Or adjust the best recommendation for some sort of riskiness of the analyst's worst recommendation. How anyone is supposed to make use of such information stymies me. Which one, of many recommendations, should I have followed from each analyst?
Wouldn't it make more sense to reward the analyst with the best overall average return on recommendations? But, wait....that would make the analyst sort of like a portfolio manager, wouldn't it?
So, maybe the notion of rewarding analysts for something investment managers are paid to do is rather awkward.
My understanding, from years in the financial services industry, was that analysts were supposed to be uniquely able to understand specific companies in depth. And that the hallmark of this was to have the least error in predicting things like earnings, or earnings per share, for companies the analysts covered. What happened to this criterion? Has it just vanished, as we admit analysts are really just junior money managers?
Of course, there's the question of how one would weight a single best recommendation from an analyst. At the same time the WSJ features articles which counsel risk management for individual and institutional portfolios, they devote an entire section to lauding analysts who made a single "best" equity buy/sell call.
Confusing, isn't it? How our largest daily business newspaper, the Wall Street Journal, can be so schizophrenic with respect to what it seems to value as good financial advice to its readers.
As I read the first page of the section, seeking to understand the bases on which analysts were evaluated, I learned the following. Analysts are apparently judged on their ability to produce a best "buy" or "sell" recommendation, in terms of total return.
At first glance, this might seem appropriate. But it seems to me to run counter to what I have been led to believe analysts are supposed to do.
First, measuring an analyst on their one best recommendation seems akin to awarding a batting title in baseball to the hitter with the single longest home run. It doesn't count the other recommendations, or the average performance of all recommendations, etc. Or adjust the best recommendation for some sort of riskiness of the analyst's worst recommendation. How anyone is supposed to make use of such information stymies me. Which one, of many recommendations, should I have followed from each analyst?
Wouldn't it make more sense to reward the analyst with the best overall average return on recommendations? But, wait....that would make the analyst sort of like a portfolio manager, wouldn't it?
So, maybe the notion of rewarding analysts for something investment managers are paid to do is rather awkward.
My understanding, from years in the financial services industry, was that analysts were supposed to be uniquely able to understand specific companies in depth. And that the hallmark of this was to have the least error in predicting things like earnings, or earnings per share, for companies the analysts covered. What happened to this criterion? Has it just vanished, as we admit analysts are really just junior money managers?
Of course, there's the question of how one would weight a single best recommendation from an analyst. At the same time the WSJ features articles which counsel risk management for individual and institutional portfolios, they devote an entire section to lauding analysts who made a single "best" equity buy/sell call.
Confusing, isn't it? How our largest daily business newspaper, the Wall Street Journal, can be so schizophrenic with respect to what it seems to value as good financial advice to its readers.
Sunday, May 21, 2006
What About The Mediocre Companies?
My friend S, a consultant, was discussing corporate performance with me recently. While debating the recent fortunes of tech companies such as Google, Intel, and Microsoft, she challenged me to articulate what I would to fix what ails the last one. I had opined that Microsoft is, essentially, finished as a company capable of generating consistently superior returns, in part, as I have written recently, because of its chairman's excessive wealth. By the way, according to S, my estimate of Gates' net worth may have been light by as much as 50% or so. He apparently was worth some $50B as recently as 6 months ago, not the $25B I thought.
In any case, I said that the first, and, for a while, only thing I would do at Microsoft would be to essentially execute the threatened anti-trust remedy of the Netscape case- split the company into three: an applications software company, an operating systems company, and an internet-related company.
I'd like to explore my friend's next major remark. She assailed me, in a friendly way, for essentially ignoring the existence of less-than-consistently-superior return-generating companies, as if they should all perish. As a consultant, I believe her tendencies and motivations lean toward fixing mediocre companies, rather than simply tossing in the towel on them. It's a laudable goal, and no doubt a profitable one for the consulting sector.
However, I approach these issues as, I believe, most of my readers do- a passive investor. Mind you, I do opine on situations which I believe can be rescued. I say whether or not I believe a company can be put back on a path to consistently superior returns, or not. For example, GM, Intel, Dell and Microsoft- almost certainly not. HP and AMD- quite possibly.
But, what is a passive investor to do now? What does a passive investor desire now?
The obvious answer to these questions is that a passive investor desires to earn total returns which exceed the market average. S/he wants, ideally, consistently superior returns, on some risk-adjusted basis. Therefore, owning the stocks of mediocre firms is probably not high on such an investor's list of things to do.
Furthermore, the investor does not have to "settle" for shares of a mediocre, below-average-return company. Because of inexpensively-marketed, passively-managed index funds from complexes such as Vanguard, an investor may easily and cheaply buy an index which represents the S&P500, or virtually any sector. There are many ways an investor may take positions in companies through these vehicles, with expectations of returns that benefit from diversification, without ever needing to actively select a single company, much less voluntarily buy a lackluster one.
However, an investor may wish to attempt to outperform the market with part of her/his funds. It so happens that my large-cap investment strategy is based upon proprietary research which has shown that the best way to increase the odds of owning consistently superior total return-generating companies is to select those who have already been doing so. Then hold them a little longer, to reap the benefits of their continuing ability to surprise other investors with their consistently superior fundamental performance. That's why I have no interest in mediocre companies.
Mediocre companies have shareholders, and employees, and produce things. They exist in our economy, and no doubt provide valuable products and services, without which you and I would probably have lives which are different as a result. These opinions of my friend S are all true.
However, that doesn't mean you, or I, should want to own stock in these mediocre purveyors of economic necessities. But someone does. And, frankly, unless they decide to take a loss, these owners may not be able to sell their shares. Of course, it's easy to see that, should they believe they have better return expectations with some other investment, they should sell. But people are not always rational about these things, by any means. For more evidence of this, just Google "behavioral finance" and sample some of the literature from this field.
So, what happens to them- the underperforming, mediocre companies? There are several possible outcomes for these companies.
For some, their stock price declines, as a result of their increasing ineptitude, until it is so low that someone actively buys up a lot of it, believing that they can modestly improve the firm, and reap the attendant total returns. An example of this in the market now is Kirk Kerkorian's long-running bet on GM's return from near-death to just "pretty sick." Eddie Lampert has gone one better at Sears, buying a controling interest in the firm, and betting on wringing some excess returns out of it, one way or another.
However, both of these are active solutions unavailable to the typical investor- even most institutional ones.
Another path for a mediocre firm is for the CEO and senior management to take the firm private, using private equity backing, in order to reap the rewards of significant restructuring away from prying eyes and quarterly demands of the investing public. In these cases, the inside management takes advantage of their better knowledge of possible outcomes for the firm, and buys it cheaply, relative to potential returns, from a lesser-informed group of shareholders. However, this removes the firm from the public markets, so, again, a passive investor won't be seeing this option until later, after the anticipated turnaround.
This leaves mediocre firms who attempt turnarounds on their own. Firms whose stock price has sunk so low that, with a modicum of better-than-average performance, their share prices may spurt up in surprised response to the unexpected results. However, by definition, this is essentially betting on aberrant behavior. It requires a lot of in-depth analysis of just the "right" opportunities. It is an exlicit timing play. The investor has to get it just right, and that usually means taking significant risks.
I actually explored these situations in my proprietary research, as one type of strategy to pursue in the equity markets. My findings were, essentially, that the likelihood of turnarounds, among all possible situations of declining performance, multiplied by the average resultant total return, provided an unfavorable expected return. It simply is not a statistically viable approach for those on the "outside" of such situations, having no special knowledge of the ensuing turnaround.
Finally, let's consider why one invests in equities. Ideally, you are in equities for their growth potential. That means valuing them for their future growth, rather than fixed-income-like steadiness of cashflows. Thus, discounted cash flow valuations are inappropriate for equities which are bought and held for, well, the potential that equities uniquely offer. This being the case, and, again, my research has supported this analytically, one would not want to buy the equities of mediocre, low-growth, or low-earnings-growth firms. It just makes no sense, when there are plenty of better alternatives out there.
So, in the final analysis, this is my reply to my friend S, as to why I ignore mediocre companies, or those formerly superior companies now lapsing into their dotage. I ignore them because, relative to currently consistently superior total return firms with the fundamental performances to sustain those returns, the mediocre companies are simply not attractive for providing the passive investor with consistently market-beating total returns.
I know someone will continue to hold the equity of mediocre companies. Some may be turned around. Others may be acquired, merged, or simply stripped and closed. But for passive investors, getting involved in mediocre firms is a high risk, low return proposition. I don't see that changing anytime soon.
In any case, I said that the first, and, for a while, only thing I would do at Microsoft would be to essentially execute the threatened anti-trust remedy of the Netscape case- split the company into three: an applications software company, an operating systems company, and an internet-related company.
I'd like to explore my friend's next major remark. She assailed me, in a friendly way, for essentially ignoring the existence of less-than-consistently-superior return-generating companies, as if they should all perish. As a consultant, I believe her tendencies and motivations lean toward fixing mediocre companies, rather than simply tossing in the towel on them. It's a laudable goal, and no doubt a profitable one for the consulting sector.
However, I approach these issues as, I believe, most of my readers do- a passive investor. Mind you, I do opine on situations which I believe can be rescued. I say whether or not I believe a company can be put back on a path to consistently superior returns, or not. For example, GM, Intel, Dell and Microsoft- almost certainly not. HP and AMD- quite possibly.
But, what is a passive investor to do now? What does a passive investor desire now?
The obvious answer to these questions is that a passive investor desires to earn total returns which exceed the market average. S/he wants, ideally, consistently superior returns, on some risk-adjusted basis. Therefore, owning the stocks of mediocre firms is probably not high on such an investor's list of things to do.
Furthermore, the investor does not have to "settle" for shares of a mediocre, below-average-return company. Because of inexpensively-marketed, passively-managed index funds from complexes such as Vanguard, an investor may easily and cheaply buy an index which represents the S&P500, or virtually any sector. There are many ways an investor may take positions in companies through these vehicles, with expectations of returns that benefit from diversification, without ever needing to actively select a single company, much less voluntarily buy a lackluster one.
However, an investor may wish to attempt to outperform the market with part of her/his funds. It so happens that my large-cap investment strategy is based upon proprietary research which has shown that the best way to increase the odds of owning consistently superior total return-generating companies is to select those who have already been doing so. Then hold them a little longer, to reap the benefits of their continuing ability to surprise other investors with their consistently superior fundamental performance. That's why I have no interest in mediocre companies.
Mediocre companies have shareholders, and employees, and produce things. They exist in our economy, and no doubt provide valuable products and services, without which you and I would probably have lives which are different as a result. These opinions of my friend S are all true.
However, that doesn't mean you, or I, should want to own stock in these mediocre purveyors of economic necessities. But someone does. And, frankly, unless they decide to take a loss, these owners may not be able to sell their shares. Of course, it's easy to see that, should they believe they have better return expectations with some other investment, they should sell. But people are not always rational about these things, by any means. For more evidence of this, just Google "behavioral finance" and sample some of the literature from this field.
So, what happens to them- the underperforming, mediocre companies? There are several possible outcomes for these companies.
For some, their stock price declines, as a result of their increasing ineptitude, until it is so low that someone actively buys up a lot of it, believing that they can modestly improve the firm, and reap the attendant total returns. An example of this in the market now is Kirk Kerkorian's long-running bet on GM's return from near-death to just "pretty sick." Eddie Lampert has gone one better at Sears, buying a controling interest in the firm, and betting on wringing some excess returns out of it, one way or another.
However, both of these are active solutions unavailable to the typical investor- even most institutional ones.
Another path for a mediocre firm is for the CEO and senior management to take the firm private, using private equity backing, in order to reap the rewards of significant restructuring away from prying eyes and quarterly demands of the investing public. In these cases, the inside management takes advantage of their better knowledge of possible outcomes for the firm, and buys it cheaply, relative to potential returns, from a lesser-informed group of shareholders. However, this removes the firm from the public markets, so, again, a passive investor won't be seeing this option until later, after the anticipated turnaround.
This leaves mediocre firms who attempt turnarounds on their own. Firms whose stock price has sunk so low that, with a modicum of better-than-average performance, their share prices may spurt up in surprised response to the unexpected results. However, by definition, this is essentially betting on aberrant behavior. It requires a lot of in-depth analysis of just the "right" opportunities. It is an exlicit timing play. The investor has to get it just right, and that usually means taking significant risks.
I actually explored these situations in my proprietary research, as one type of strategy to pursue in the equity markets. My findings were, essentially, that the likelihood of turnarounds, among all possible situations of declining performance, multiplied by the average resultant total return, provided an unfavorable expected return. It simply is not a statistically viable approach for those on the "outside" of such situations, having no special knowledge of the ensuing turnaround.
Finally, let's consider why one invests in equities. Ideally, you are in equities for their growth potential. That means valuing them for their future growth, rather than fixed-income-like steadiness of cashflows. Thus, discounted cash flow valuations are inappropriate for equities which are bought and held for, well, the potential that equities uniquely offer. This being the case, and, again, my research has supported this analytically, one would not want to buy the equities of mediocre, low-growth, or low-earnings-growth firms. It just makes no sense, when there are plenty of better alternatives out there.
So, in the final analysis, this is my reply to my friend S, as to why I ignore mediocre companies, or those formerly superior companies now lapsing into their dotage. I ignore them because, relative to currently consistently superior total return firms with the fundamental performances to sustain those returns, the mediocre companies are simply not attractive for providing the passive investor with consistently market-beating total returns.
I know someone will continue to hold the equity of mediocre companies. Some may be turned around. Others may be acquired, merged, or simply stripped and closed. But for passive investors, getting involved in mediocre firms is a high risk, low return proposition. I don't see that changing anytime soon.
Thursday, May 18, 2006
Another Example of the "Efficient Market" at Work?
If you still had any belief in an "efficient" market, Wednesday and Thursday ought to have cured you.
As I've written here in a prior post, there are two ways markets can be inefficient. I believe this week demonstrated both.
On Wednesday, some data was reported which showed a small rise in core inflation. This had even been commented on, a priori, by no less a person than Bernanke, as expected. So much for 'new information.' Never the less, it caused a market sell off.
If the information was not all that unexpected, how can one explain an "efficient" market dropping by 1.7% ? With individual stocks declining far more just on principle. Hardly very "efficient," eh?
Then, on Thursday, the continued confusion resulted in a flat market. Until Fed official Poole remarked that, at their next meeting, the Fed might raise rats half a point, or maybe, not at all.
This caused an immediate panic of selling. The market sold off to end the session roughly another .7% down.
Mind you, Poole only voiced what most pundits believed, and even Bernanke has said. That the Fed is looking at evolving data, and will make its decision at the appropriate time, on the relevant data at that time. Nothing new here.
No, this further drop was the result of a lot of mediocre, poorly-reasoning investors dumping shares on fear. Nothing more.
There's no sign yet that healthy global growth has lapsed. Any inflation is demand pull, not cost push. If global demand ebbs a little to cool the commodities price froth, so be it. That won't bring construction in Chindia to a standstill anytime soon.
Simply put, nothing "happened" this week to cause the equities of well-managed, profitable, growing large-cap US firms to drop in value by 10%. Temporary perception may be that these companies are now worth much less. But the available information on the environment, and the companies themselves, suggest otherwise.
So much, again, for "efficient" markets. How efficient can they be, if little, or no, information, can bring changes of the scale seen in just two days this week. And how "equal" can all the investors be in processing this "information," if such a stampeded is caused? And then reversed again today, by almost half a percentage point in the opposite direction?
As I've written here in a prior post, there are two ways markets can be inefficient. I believe this week demonstrated both.
On Wednesday, some data was reported which showed a small rise in core inflation. This had even been commented on, a priori, by no less a person than Bernanke, as expected. So much for 'new information.' Never the less, it caused a market sell off.
If the information was not all that unexpected, how can one explain an "efficient" market dropping by 1.7% ? With individual stocks declining far more just on principle. Hardly very "efficient," eh?
Then, on Thursday, the continued confusion resulted in a flat market. Until Fed official Poole remarked that, at their next meeting, the Fed might raise rats half a point, or maybe, not at all.
This caused an immediate panic of selling. The market sold off to end the session roughly another .7% down.
Mind you, Poole only voiced what most pundits believed, and even Bernanke has said. That the Fed is looking at evolving data, and will make its decision at the appropriate time, on the relevant data at that time. Nothing new here.
No, this further drop was the result of a lot of mediocre, poorly-reasoning investors dumping shares on fear. Nothing more.
There's no sign yet that healthy global growth has lapsed. Any inflation is demand pull, not cost push. If global demand ebbs a little to cool the commodities price froth, so be it. That won't bring construction in Chindia to a standstill anytime soon.
Simply put, nothing "happened" this week to cause the equities of well-managed, profitable, growing large-cap US firms to drop in value by 10%. Temporary perception may be that these companies are now worth much less. But the available information on the environment, and the companies themselves, suggest otherwise.
So much, again, for "efficient" markets. How efficient can they be, if little, or no, information, can bring changes of the scale seen in just two days this week. And how "equal" can all the investors be in processing this "information," if such a stampeded is caused? And then reversed again today, by almost half a percentage point in the opposite direction?
Wednesday, May 17, 2006
Dell Again: The WSJ Almost Gets It Right
Suffice to say, I feel prescient regarding my comments about Dell's performance, both recently, and beginning in the 1990s. Yesterday's Wall Street Journal "Portals" column by Lee Gomes echoed my points exactly.
What was particularly nice was his mention at the end of his piece of three pairs of companies whom I, too, have discussed recently: AMD & Intel, Google & Microsoft, HP & Dell.
However, whereas I attribute the performances to Schumpeterian dynamics, Gomes, who is primarily a technology writer, merely writes, "something seems to be in the air: Formerly bulletproof business models are fissuring under the pressure of new and unexpected competition."
Well, unexpected if you don't read Schumpeter, and/or have the benefit of my proprietary performance research using thousands of large-cap equity observations over many years. Or haven't bothered even a cursory look at the fate of top technology companies going back to even just the 1960s.
Too, Gomes only references a very short timeframe when he writes, "If you chart the stock performance of Dell vs. H-P over the past year, you get a sideways V, with the trend lines moving in opposite directions, and Dell on the bottom heading lower." He mentions the other pairs, listed above, as having similar relationships of charted performance. I've included a Yahoo-sourced chart of all pairs on the left. The S&P500, by the way, bisects the pairs, three above, three below, for the one-year view.
Now, look at a much longer term chart of the same companies, again, with the S&P500 for reference.
What was particularly nice was his mention at the end of his piece of three pairs of companies whom I, too, have discussed recently: AMD & Intel, Google & Microsoft, HP & Dell.
However, whereas I attribute the performances to Schumpeterian dynamics, Gomes, who is primarily a technology writer, merely writes, "something seems to be in the air: Formerly bulletproof business models are fissuring under the pressure of new and unexpected competition."
Well, unexpected if you don't read Schumpeter, and/or have the benefit of my proprietary performance research using thousands of large-cap equity observations over many years. Or haven't bothered even a cursory look at the fate of top technology companies going back to even just the 1960s.

Too, Gomes only references a very short timeframe when he writes, "If you chart the stock performance of Dell vs. H-P over the past year, you get a sideways V, with the trend lines moving in opposite directions, and Dell on the bottom heading lower." He mentions the other pairs, listed above, as having similar relationships of charted performance. I've included a Yahoo-sourced chart of all pairs on the left. The S&P500, by the way, bisects the pairs, three above, three below, for the one-year view.
Now, look at a much longer term chart of the same companies, again, with the S&P500 for reference.
The slopes of the lines approximate the total returns for these stocks, as their dividends tend to be minimal. While it is clear that things never returned to pre-bubble levels for Dell, Intel, and Microsoft after 2000, the stories for the other three are by no means all alike.
What this view demonstrates is that Dell, Intel and Microsoft have taken their shareholders to places AMD and H-P have yet to go, and Google has been for a still-brief time. You have to give the former triumvirate their due for wringing tremendous shareholder returns out of a decade of dominance of the PC market.
To look at just the last year and pronounce them failures, and that 'something seems to be in the air,' is to misunderstand the fundamental nature of company and product lifecycles in technology sectors. Dell, Intel and Microsoft steamrolled their competitors in their heydays. But those days are over. And what is occurring now is by no means "unexpected."
Further, it's not like all three better performers have blunted the older business models of the now-worse-performing three firms. HP has only managed to regain traction in its markets, and to quote an old song, "been down so long, it looks like up to me." AMD has taken advantage of Intel's inability to now manage further technological hegemony in chip making with its resultant size and diversity of product/markets. But AMD languished for decades as a poor performer prior to this.
Google is the one company which represents a greenfield entry which has piggybacked on the environment created by Microsoft, Intel and Dell. But it is also the shortest-lived case of the six. I would say the jury is still out regarding the long term path Google will actually take.
In conclusion, Gomes does a nice job highlighting the recent, resulting total returns and business situations of these pairs of competitors. However, in expressing surprise, he unfortunately displays a shallow grasp of fundamental business dynamics discovered 80 years ago by Joseph Schumpeter. I think we can expect more from a featured columnist of the country's best business daily.
Don't you?
"Forget the S&P" as a Benchmark ?
My partner recently called my attention to Jonathan Clement's piece in the Wall Street Journal which decried the use of the S&P500 as a performance benchmark for portfolios. Actually, it's not quite that simple. Clements seemed to both lampoon the use of, and then use, anyway, the S&P500 as a performance benchmark for various fund styles, and whole portfolios of multiple instruments.
My partner lamented, and I agree, the piece was so obtusely written as to almost defy analysis, let alone understanding.
Mr. Clements begins by stating that many readers of his column have contacted him to crow about their investments having beaten the S&P recently. Clements goes on to state that,
"... I don't believe they're investment geniuses. Here's why beating the S&P 500 is no great accomplishment......In fact, if you haven't outpaced the S&P 500 over the past five or six years, something is likely seriously wrong with your investment strategy. After all, as part of a well-diversified portfolio, you ought to spread your money across large stocks, smaller companies, foreign markets and bonds. Any mix of that kind should have handily beaten the S&P 500."
Well, yes. Let's just forget about risk, and timing. And while we're at it, lets compare the return of various asset classes as if they are all equal. And the brief time period over which the observations are taken.
Clements bounces between lecturing on using the proper benchmark for each type of investment and mutual fund style, and then saying you should compare your entire investment return, across all instruments, to the S&P500. On that basis, he dismisses outperforming the S&P as child's play.
Later, in the article, he talks about how is IRA account has handily beaten the S&P, but then admits its is in "small stocks and foreign markets, both of which have easily outpaced the S&P 500."
Again, let's forget about how much more risk is typically found in foreign markets, or small stocks, too, for that matter. It's not a fair comparison by any means, and certainly not significant over very short timeframes.
Professional portfolio managers undrestand that the S&P500 is an appropriate benchmark for large-cap equity portfolios. Period. For hedged funds, it's cash. For bond funds, I would guess it's some variant on a popularly tracked bond index. Why Clements thinks anyone has implied more than this is beyond me.
What dismays and disappoints me about this muddled, wrong-headed piece by Clements about investment performance, is that it's in a large, broadly distributed, reputable business daily- the Wall Street Journal. And Clements writes a weekly column on investing.
With "help" like this, you wonder if most individuals can just preserved their capital over time, let alone actually make money. We see now just how sadly missed Lou Rukeyser will be.
My partner lamented, and I agree, the piece was so obtusely written as to almost defy analysis, let alone understanding.
Mr. Clements begins by stating that many readers of his column have contacted him to crow about their investments having beaten the S&P recently. Clements goes on to state that,
"... I don't believe they're investment geniuses. Here's why beating the S&P 500 is no great accomplishment......In fact, if you haven't outpaced the S&P 500 over the past five or six years, something is likely seriously wrong with your investment strategy. After all, as part of a well-diversified portfolio, you ought to spread your money across large stocks, smaller companies, foreign markets and bonds. Any mix of that kind should have handily beaten the S&P 500."
Well, yes. Let's just forget about risk, and timing. And while we're at it, lets compare the return of various asset classes as if they are all equal. And the brief time period over which the observations are taken.
Clements bounces between lecturing on using the proper benchmark for each type of investment and mutual fund style, and then saying you should compare your entire investment return, across all instruments, to the S&P500. On that basis, he dismisses outperforming the S&P as child's play.
Later, in the article, he talks about how is IRA account has handily beaten the S&P, but then admits its is in "small stocks and foreign markets, both of which have easily outpaced the S&P 500."
Again, let's forget about how much more risk is typically found in foreign markets, or small stocks, too, for that matter. It's not a fair comparison by any means, and certainly not significant over very short timeframes.
Professional portfolio managers undrestand that the S&P500 is an appropriate benchmark for large-cap equity portfolios. Period. For hedged funds, it's cash. For bond funds, I would guess it's some variant on a popularly tracked bond index. Why Clements thinks anyone has implied more than this is beyond me.
What dismays and disappoints me about this muddled, wrong-headed piece by Clements about investment performance, is that it's in a large, broadly distributed, reputable business daily- the Wall Street Journal. And Clements writes a weekly column on investing.
With "help" like this, you wonder if most individuals can just preserved their capital over time, let alone actually make money. We see now just how sadly missed Lou Rukeyser will be.
Tuesday, May 16, 2006
Gates' and Otelilini's WSJ Op-Ed Piece
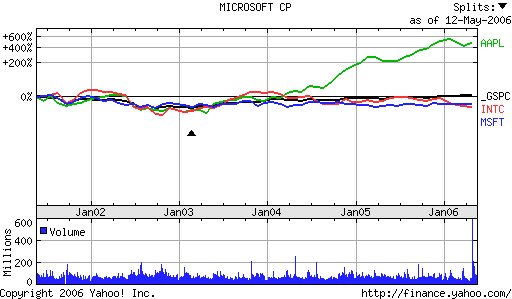
Yesterday's Wall Street Journal featured an op-ed piece jointly written by Bill Gates, "chairman and "chief software architect of Microsoft," and Paul Otellini, president and CEO of Intel.
Their letter was apparently a rejoinder to a piece in the WSJ's technology column, written by Walt Mossberg, extolling Apple's 'closed system' approach as now edging out the older, Wintel 'open system' in terms of popularity.
What I find very telling is the authors' confusion between the continued usage of PCs, and their ability to command premium value anymore. It's not so much the "end of the PC era," anymore than the influx of Japanese imports marked the "end of the automobile" era.
As I've written previously in my blog, both Microsoft and Intel are at the end of long periods of having dominanted their respective product spaces. By virtue of their dominances, they have changed the environment within which their firms, and their products, operate.
I don't think anyone seriously believes PCs and laptops are going away anytime soon. However, just like modern automobiles, though, they will probably last longer, offer more features for less money, and, in general, work better with other devices than they have in the past. The pace of replacement of boxes and operating systems is certainly slowing now, in comparison to the past.
If these trends were not occurring, then the PC probably would become obsolete, due to its having walled itself off from the need for customers to connect various devices and media across the internet and their own systems. As it is, the value-adding damage has already been done to PC systems and their software and hardware components.
See the chart at the top of this piece for the visual confirmation. It shows Apple pulling away from Microsoft, Intel and the S&P500 beginning in 2004.
It would be fun to speculate on the discussions leading up to the WSJ letter by Gates and Otellini. Better still, to listen in on their conversations and see the drafts. Clearly, they felt a gauntlet had been thrown down, challenging their companies' relevance as being at the heart of today's digitalization trends. It's noteworthy that all it took was a guy who writes a weekly technology column in a business newspaper to spark this reaction from the two company leaders.
Gates' and Otellini's protestations notwithstanding, there is far more activity in application-specific digital devices (digital music players, cellphones, PDAs, etc) and internet connectivity than there is in necessary, but basic, PC systems. Rather than, as their piece asserted, it being the "end of the beginning" for the PC, it may simply now mark the arrival of the device as a low-priced electronic appliance with little more capacity for functionality growth that is not due to some other devices produced by other companies.
Monday, May 15, 2006
HP "vs" Dell
Last week, CNBC made much of Hewlett-Packard's recent short-term revival, and contrasted it with Dell's recent weakness. The latter's revenues have been falling short of expectations, and its total returns are no longer consistently market-beating. I even wrote recently of the positive signs in the nature of the way Mark Hurd seems to be changing HP.

As the five-year price chart from Yahoo above clearly shows, HP has been on a consistently superior total return path for nearly 5 years, and from a serious trough for the last 3-4 years. In contrast, Dell has been flat or declining, both absolutely and relatively, for about 2 1/2 years.
Yes, for the recent period, Dell has seemed played out. Exhausted in the sense of a business model with little headroom for profitably surprising the market.However, as I observed about Intel recently, let me do so for Dell now. Take a look at the Yahoo-sourced long term performance chart below.
For an entire decade, Dell out-performed HP, the S&P500, and not a few other tech companies with its solid business concept and nearly-flawless execution thereof. Isn't a decade enough? This company has excelled, in what should have been, and was, a very tough product/market segment, for much longer than should have been expected. Than is the norm.
To look at just the last 5 years is to seriously misunderstand both business history, and Schumpterian dynamics. Dell is probably not "coming back," anymore than Microsoft or Intel are. That is, it's unlikely that any of the three will soon post a consistently superior total return record, versus the S&P500, on the back of consistently superior revenue growth.
But this in no way diminishes their prior accomplishments. In fact, it is those accomplishments which have brought them to this point. Microsoft has played out its "technology," for the most part. Intel is stretched amongst separating customer segments, while its once-weaker rival, AMD, focuses on profitable opportunities with laser-like precision. Dell simply has little room left to exploit its vaunted direct-sales model, amidst the increasing commoditization of its main products, desktop and laptop PCs.
The funny thing about the second chart, to me, at least, is that, if not for Dell, you'd think HP had done very well. And never really "in trouble" until these last few years. It just shows how moderated our expectations can get, and how we sometimes forget what "really" excellent performance looks like.In fact, in hindsight, you would have been happy holding both for a decade.But who knew in advance? And, of course, it's always easier in hindsight to see the end of a holding period than it is when you're actually doing it.
Subscribe to:
Posts (Atom)


