Time Warner's latest plans for its AOL subsidiary are curious for their abandonment of marketing management principles. As I understand the plan, they are considering giving the entire AOL package, including email, free, to anyone with a high speed connection, just like yahoo, msn, and google.
On one hand, this may seem like a recognition that AOL really offers little of value for which people will pay, when the aforementioned alternatives are available.
However, AOL does earn revenue from users, despite the alternatives. Some people probably have both- an AOL account for which they pay, and use as an ISP, as well as free email accounts with one or more of the other providers.
Is it really smart to paint all of your customers with the same brush, and offer any of them who have their own access a 100% discount on the service? Are there not any user segments who will remain with AOL on a paying basis? Since they have that $2B of annual revenue already, why prematurely and voluntarily refund much of it? Why not raise prices on the most primitive, dial-up users, and maintain prices on those who, for whatever reason, still don't move their high-speed accessed accounts elsewhere?
Thinking back to my prior post, about Wal-Mart's foray into financial services, it seems that Time Warner is taking the opposite tack. Whereas Wal-Mart focuses on how to segment its customers, and better serve them through that understanding, Time Warner seems to be going the opposite way. They just lump most of their customer base into one bucket, and give their service to those people. Whomever they are. AOL isn't even talking about, say, developing customer profiles to use in making offers of reduced priced services to those most likely to leave AOL.
I think this reinforces the view that AOL is mismanaged, and Time Warner is compounding the problem with another layer of inept management on top of the online unit.
Carl Icahn, please call home......
Thursday, July 06, 2006


Wal-Mart's Big Financial Services Dreams
Today's Wall Street Journal contains a story about Wal-Mart's planned big push into low-end financial services. We are talking here about payroll check cashing, wiring money, and bill paying.
From reading the article, it looks like Wal-Mart, with its size and diversified business lines, will be able to offer these services at a significant discount to the prices typically charged by those vendors who prey on low-income financial services customers. Perhaps the best example is payroll check cashing. Your typical local 'service' provider will charge a user 2-3% of the face value of the check. Wal-Mart charges a maximum of $3/check. Do the math, and for a blue-collar worker who earns $20,000/year and is paid something like $650, net, every two weeks, the average current check-cashing fee is nearly $16. So Wal-Mart will be providing enormous value to low-income consumers, who also happen to be its major target market. The company noted that it also currently processes 1.5-2MM money-services transactions per week.
On first glance, I thought Wal-Mart might get tarred for this business expansion. You can just imagine some consumer advocates picketing the big-box giant, charging that it is merely jumping in to get its share of vigorish from its financially struggling customer base.
But that doesn't seem to be the case at all here. Wal-Mart's money orders cost $.46, compared with $1.30 at the US post office. The company appears to be delivering substantial value to its customers with this suite of services.
However, that said, I don't think it's going to do an awfully lot of good for Wal-Mart over the long haul. In response to charges by a spokesman for the Massachusetts Bankers Association that "Wal-Mart wants people to cash their checks in their stores so they can then make impulse purchases in the store," the company replied that only 'about 14% of people who cash checks at the store make purchases at the same time,' according to the WSJ article. That would work out to about one collateral purchase trip for every 7-8 financial service visits. In effect, 6 times per year.
And, by the way, kudos to the bankers in Massachusetts for managing to come off explicitly as a group of bloodsuckers. By saying it's ok to charge egregious fees on check cashing for poor people, but heaven forbid those people save on the fees and spend some of that extra money on real goods they can take home with them, this group appears to want a monopoly on taking advantage of the least-well off in our society. At least Wal-Mart has demonstrated that, by intervening, they will actually give these poor people real benefits that they can't get from today's banking sector.
So, essentially, what we have is the Schumpterian phenomenon of Wal-Mart weighing in to gut value-added dollars in the low-end financial services sector, in order to transfer some of that value to its customers, thereby strengthening the company's position in that segment. I don't think Wal-Mart will profit, per se, from this move. It is mostly defensive.
In fact, it kind of makes you wonder what happened to Wal-Mart's purported move, last year, upmarket. Isn't this financial service expansion at the low end going to blur that repositioning?
It seems kind of ironic to me, by the way, how things have come full circle. Back in 1974, in my very first marketing class, I learned that Sears was then earning more gross dollars of revenue on the interest in charged on customer credit card balances, than it earned on merchandise margins. Of course, in the intervening 32 years, that has been radically changed. Retailers lost the entire captive financial services business to GE and the banking sector. Now, a large, cost-effective retailer comes back in to underprice the financial service sector on low-end services, in order to build more customer loyalty and, probably, gain some extra margin/square foot of floor space.
From reading the article, it looks like Wal-Mart, with its size and diversified business lines, will be able to offer these services at a significant discount to the prices typically charged by those vendors who prey on low-income financial services customers. Perhaps the best example is payroll check cashing. Your typical local 'service' provider will charge a user 2-3% of the face value of the check. Wal-Mart charges a maximum of $3/check. Do the math, and for a blue-collar worker who earns $20,000/year and is paid something like $650, net, every two weeks, the average current check-cashing fee is nearly $16. So Wal-Mart will be providing enormous value to low-income consumers, who also happen to be its major target market. The company noted that it also currently processes 1.5-2MM money-services transactions per week.
On first glance, I thought Wal-Mart might get tarred for this business expansion. You can just imagine some consumer advocates picketing the big-box giant, charging that it is merely jumping in to get its share of vigorish from its financially struggling customer base.
But that doesn't seem to be the case at all here. Wal-Mart's money orders cost $.46, compared with $1.30 at the US post office. The company appears to be delivering substantial value to its customers with this suite of services.
However, that said, I don't think it's going to do an awfully lot of good for Wal-Mart over the long haul. In response to charges by a spokesman for the Massachusetts Bankers Association that "Wal-Mart wants people to cash their checks in their stores so they can then make impulse purchases in the store," the company replied that only 'about 14% of people who cash checks at the store make purchases at the same time,' according to the WSJ article. That would work out to about one collateral purchase trip for every 7-8 financial service visits. In effect, 6 times per year.
And, by the way, kudos to the bankers in Massachusetts for managing to come off explicitly as a group of bloodsuckers. By saying it's ok to charge egregious fees on check cashing for poor people, but heaven forbid those people save on the fees and spend some of that extra money on real goods they can take home with them, this group appears to want a monopoly on taking advantage of the least-well off in our society. At least Wal-Mart has demonstrated that, by intervening, they will actually give these poor people real benefits that they can't get from today's banking sector.
So, essentially, what we have is the Schumpterian phenomenon of Wal-Mart weighing in to gut value-added dollars in the low-end financial services sector, in order to transfer some of that value to its customers, thereby strengthening the company's position in that segment. I don't think Wal-Mart will profit, per se, from this move. It is mostly defensive.
In fact, it kind of makes you wonder what happened to Wal-Mart's purported move, last year, upmarket. Isn't this financial service expansion at the low end going to blur that repositioning?
It seems kind of ironic to me, by the way, how things have come full circle. Back in 1974, in my very first marketing class, I learned that Sears was then earning more gross dollars of revenue on the interest in charged on customer credit card balances, than it earned on merchandise margins. Of course, in the intervening 32 years, that has been radically changed. Retailers lost the entire captive financial services business to GE and the banking sector. Now, a large, cost-effective retailer comes back in to underprice the financial service sector on low-end services, in order to build more customer loyalty and, probably, gain some extra margin/square foot of floor space.
More on Corporate Governance: Executive Compensation Continues to Rise
The Wall Street Journal recently used the occasion of Pfizer's annual meeting to run yet another piece about exorbitant CEO compensation packages. Carol Hymowitz wrote a very nice piece detailing the realities of this problem.
When asked to defend Pfizer CEO Hank McKinnell's compensation, Dana Mead, head of the board's compsenation committee, did so by saying, '....Mr. McKinnell's pay was based on market forces and reflected his responsibility overseeing 110,000 employees."
The article notes that "disgruntled shareholders even tried to unseat Mr. Mead and another director this past April but failed."
What is irksome to me is that Mr. Mead didn't say something like, "Mr. McKinnell has the responsibility to earn above-average total returns for you shareholders. In hopes of attracting talented leaders to be our company's CEO, and make that happen, we need to offer a competitive compensation package. If Mr. McKinnell proves unable to meet this responsibility, he will be replaced with someone in whom we, your board members, feel is better-equipped to carry out this responsibility."
Ms. Hymowitz quotes Lucian Bebchuk, a Harvard University law professor, who notes that the board is beholden to the CEO for their membership and, thus, pretty much have to repay him/her with bloated compensation packages, and that "they don't have an incentive to change those arrangements."
Well, that really says it all, doesn't it? You have a board charged with CEO oversight, but who nominates the board? The CEO. Wonderful! I guess having no board is marginally more corrupt, but, judging by modern CEO compensation and corporate total return performances, not by much.
Though the article closes with comments on the competition for good CEOs as the reason for excessive compensation packages, I have my doubts about that. Look at corporate performance, and you'll see that very few CEOs seem to be able to achieve consistently superior returns for their shareholders. It should be fairly easy to design a CEO compensation package with the predominant proportion of it structured as variable, and payable upon attainment of consistently superior returns for the shareholders. That way, shareholders only pay for the performance. As I have written elsewhere on this blog, why would you want a CEO who doesn't think s/he can do this in the first place?
When asked to defend Pfizer CEO Hank McKinnell's compensation, Dana Mead, head of the board's compsenation committee, did so by saying, '....Mr. McKinnell's pay was based on market forces and reflected his responsibility overseeing 110,000 employees."
The article notes that "disgruntled shareholders even tried to unseat Mr. Mead and another director this past April but failed."
What is irksome to me is that Mr. Mead didn't say something like, "Mr. McKinnell has the responsibility to earn above-average total returns for you shareholders. In hopes of attracting talented leaders to be our company's CEO, and make that happen, we need to offer a competitive compensation package. If Mr. McKinnell proves unable to meet this responsibility, he will be replaced with someone in whom we, your board members, feel is better-equipped to carry out this responsibility."
Ms. Hymowitz quotes Lucian Bebchuk, a Harvard University law professor, who notes that the board is beholden to the CEO for their membership and, thus, pretty much have to repay him/her with bloated compensation packages, and that "they don't have an incentive to change those arrangements."
Well, that really says it all, doesn't it? You have a board charged with CEO oversight, but who nominates the board? The CEO. Wonderful! I guess having no board is marginally more corrupt, but, judging by modern CEO compensation and corporate total return performances, not by much.
Though the article closes with comments on the competition for good CEOs as the reason for excessive compensation packages, I have my doubts about that. Look at corporate performance, and you'll see that very few CEOs seem to be able to achieve consistently superior returns for their shareholders. It should be fairly easy to design a CEO compensation package with the predominant proportion of it structured as variable, and payable upon attainment of consistently superior returns for the shareholders. That way, shareholders only pay for the performance. As I have written elsewhere on this blog, why would you want a CEO who doesn't think s/he can do this in the first place?
Sunday, July 02, 2006
Ford & GM: Recent Developments
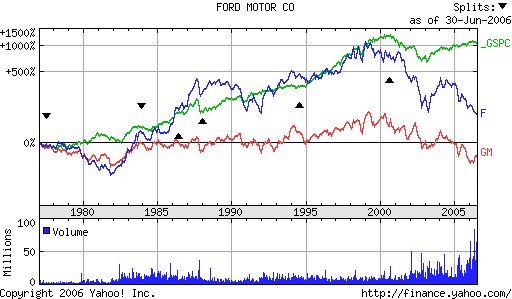
Ford and GM's recent developments were the subject of a short piece in this week's Wall Street Journal. The author of the piece only went back to January of this year to issue his opinion. His verdict was that GM is in better shape for a "turnaround" because of outside pressure from Kerkorian, while Ford's two-class stock structure kept its value from rising due to the founding family's insulation from common investors. His conclusion is that Ford is less market-sensitive, due to the Ford family's near-controlling 40% voting stake in the firm.
I find this a touch myopic, as the longterm Yahoo chart above shows. Comparing the S&P500, GM and Ford since 1979, it puts the lie to the notion that Ford has typically been slow to respond to market forces, due to the Ford family's control of the firm. Sure, in 2006, GM has displayed a better shareholder return than that of Ford. No question about that. Just not being in Chapter 11 yet is probably a big boost for GM.
However, if you look carefully at the chart above, it continues to echo what I discussed in a recent post about these two firms. While Ford's voting structure may shield it somewhat from market forces, it still has outperformed GM over the past quarter century. And by a rather handsome margin, as GM has been negative, while Ford looks to have returned something in the neighborhood (interpolating on the chart above) of 100%. The S&P returned roughly 1000% over the period.
That Ford had some significant "up" periods, from the early 1980s to 2000, suggests that they were, in fact, quite sensitive to shareholder returns. GM, by contrast, rarely broke out of a flat return curve, save for a few years in the late 1990s.
My point is that, due to an unnecessarily short analytical time horizon, the WSJ has summarily judged Ford to be too insular to save now. While GM, through the mixed blessing of attracting Kirk Kerkorian, and his lieutenant, Jerry York's advice to find a global partner, has temporarily surged ahead of the former in total return terms.
I don't necessarily believe Bill Ford is turning, or will turn around Ford. His "way forward" seems "way too optimistic," in my opinion. If only because the management team that got you to where Ford is now, is unlikely to take you somewhere else, as a shareholder. But the company is sensitive to market pressures all on its own.
I don't think GM is more "investor sensitive." Instead, it has to deal with a veteran value shopper, in Kerkorian. As the WSJ, as well as CNBC, articulated, what's good for GM shareholders, the prospect of a partial rescue in the form of some global tie-up with the likes of Nissan, is probably not good for CEO Wagoner. If anything, Wagoner put GM where it is today through his learned insensitivity to market forces, as a result of a long tenure at the stumbling auto giant.
Yes, GM may well have marginally brighter prospects for its shareholders. But don't attribute GM's idiosyncratic fortune to Ford's share voting structure. Ford is in trouble due to inept management that has tried to grapple with global pressures on an aged, badly-led competitor. Not due to an unwillingness to acknowledge the problem.
YouTube Comes Out of the Garage
YouTube must be nearing a significant milestone of some sort. The Wall Street Journal mentioned it in two different pieces in the last two weeks.
One piece covered a multitude of approaches being developed to provide video from the web to the home. YouTube doesn't address the last few feet, from the cable to the TV. But it is far and away the most visited video website, according to the WSJ's article.
What is remarkable about YouTube is that you can see it visibly following in the footsteps of Microsoft, eBay, Yahoo and Google. It was fashioned as a personal solution to a problem- sharing large video files between friends and acquaintances.
It's now become larger, gotten VC funding ($3.5MM from Sequoia), hired a Yahoo veteran to build their sales team, and begun to explore longer-term profitability models linked to their core service.
Along the way, commenting on these points, and the huge traffic YouTube boasts ( 3 million videos viewed daily, as of Dec. 15, 2005), the Journal pointed out that the two founders, literally in the apocryphal garage, had out-innovated a host of existing, large media companies ( e.g., see my recent post on moribund Time Warner). Now, several large media corporations are rumored to be sniffing around YouTube, looking to acquire it.
It's truly gratifying to see this type of company develop as it has. For me, it maintains and nourishes my faith in enterprises which begin with keen consumer behavioral insights and a savvy, gritty sense of implementation. Rather than oozing forth from the likes of Disney or Time Warner, this type of high-energy, edgy operation springs up from virtually "nowhere." Mainstream media firms would probably bog down over the copyright issues that YouTube has from user-posted content that is inappropriately published, resulting in their legal departments becoming profit centers due to bizarre time and cost-allocation methods. Instead, YouTube deals with these matter with alacrity, gently letting its popularity and 'cool' image persuade some of the larger copyright holders to look for ways to work together, rather than try to stomp YouTube out of existence.
I have no idea where these two guys and their firm will end up. But it's a lot of fun, and instructional, to watch them rip through the electronic media world, successfully meeting needs and attracting customers, while overpaid suits in the suites of a variety of larger competitors sit and stare at their coming downfall. I have to believe that Joseph Schumpeter would be extremely proud and not at all surprised to see YouTube rocketing across the online video publishing sky, threatening established vendors across the media sector.
One piece covered a multitude of approaches being developed to provide video from the web to the home. YouTube doesn't address the last few feet, from the cable to the TV. But it is far and away the most visited video website, according to the WSJ's article.
What is remarkable about YouTube is that you can see it visibly following in the footsteps of Microsoft, eBay, Yahoo and Google. It was fashioned as a personal solution to a problem- sharing large video files between friends and acquaintances.
It's now become larger, gotten VC funding ($3.5MM from Sequoia), hired a Yahoo veteran to build their sales team, and begun to explore longer-term profitability models linked to their core service.
Along the way, commenting on these points, and the huge traffic YouTube boasts ( 3 million videos viewed daily, as of Dec. 15, 2005), the Journal pointed out that the two founders, literally in the apocryphal garage, had out-innovated a host of existing, large media companies ( e.g., see my recent post on moribund Time Warner). Now, several large media corporations are rumored to be sniffing around YouTube, looking to acquire it.
It's truly gratifying to see this type of company develop as it has. For me, it maintains and nourishes my faith in enterprises which begin with keen consumer behavioral insights and a savvy, gritty sense of implementation. Rather than oozing forth from the likes of Disney or Time Warner, this type of high-energy, edgy operation springs up from virtually "nowhere." Mainstream media firms would probably bog down over the copyright issues that YouTube has from user-posted content that is inappropriately published, resulting in their legal departments becoming profit centers due to bizarre time and cost-allocation methods. Instead, YouTube deals with these matter with alacrity, gently letting its popularity and 'cool' image persuade some of the larger copyright holders to look for ways to work together, rather than try to stomp YouTube out of existence.
I have no idea where these two guys and their firm will end up. But it's a lot of fun, and instructional, to watch them rip through the electronic media world, successfully meeting needs and attracting customers, while overpaid suits in the suites of a variety of larger competitors sit and stare at their coming downfall. I have to believe that Joseph Schumpeter would be extremely proud and not at all surprised to see YouTube rocketing across the online video publishing sky, threatening established vendors across the media sector.
Thursday, June 29, 2006
Time Warner's Troubles Again

The Wall Street Journal ran another piece about TimeWarner's woes last Friday. I wrote about TWX recently here. The chart at the left displays the firm's performance, relative to the S&P500, over the last five years.
Rather than repeat what I wrote there, which is pretty recent, I'd like to use the continuing coverage of TimeWarner's troubles to discuss a root cause of the trouble. That cause is a confusion among senior management of growth and size.
Here's a quick primer. Growth prospects have and create value based upon their own performance. Adding or retaining growth prospects among a collection of non-growth units will hide the value created by the growth prospects. Being a large company is no longer value creating in and of itself, and certainly not in a fast-changing, technologically-affected sector like entertainment and communications.
Thus, Time Warner is now being run exactly wrong. It's a testament to a bygone age in which size conferred safety from takeovers. Dick Parsons points to a few units and assures investors that, any day now, TWX will pull out of its value-destroying tailspin.
The reality is this. In this day and age, small companies, like YouTube (to be covered in an imminent post) can create successfully, in a garage what large media companies cannot. Small startups can employ bright people, off-the-shelf technology and functional services (accounting, HR, sales, finance), get funding from VC's or other sources, and, ultimately, the market. In surprisingly short timeframes, they can commercialize and market products and services that a giant like Time Warner can only discuss and plan. If the latter could effectively implement the concept to begin with.
Time Warner is ailing because its many mediocre divisions, staffed by mediocre salaried employees, can't innovate and grow sufficiently to match competitors. The size of this congolmerate makes delivering excellent customer value at a profit a second-order issue, behind just "running the company."
According to the WSJ, TWX has lost 10% of it's market value since Icahn abandoned his attempt to get control of the board. Not surprising.
In such a dynamic sector as entertainment, why would anyone expect a large, multi-divisional dinosaur to create consistently-superior shareholder returns? The very size of TWX almost guarantees that some of their units will drag performance. Shareholders would be so much better off by a split of the firm into many pieces, each delivering superior value to consumers on its own, and earning consistently superior returns for its shareholders. The weak, lagging units would, necessarily, be dealt with as the market typically does- value destroyed, bought cheaply for restructuring, and removed as a burden on the better-performing growth prospects that are now hidden within Time Warner's vast collection of media businesses.
Wednesday, June 28, 2006
Bill Gates' New World
The business media was abuzz on Monday and Tuesday of this week with news of Bill Gates' best buddy, Warren Buffett's, gift of $37B to the former's foundation.
I caught part of the public relations event in which Bill, his wife, Melinda, and Warren Buffett announced the gift. Has anyone seen Bill Gates this happy and relaxed since his early days as a middling guest of Steve Jobs, when the latter was still doing battle with IBM in the mid-1980s?
Last month, I saw Gates interviewed on Donny Deutsch's "The Big Idea." When Deutsch asked Gates what Bill would say to the leaders of Google, if they were in the audience, Bill nervously mumbled something like, ".....ah...we're going to keep you guys honest." I wrote about it in this prior post. I'm sure that struck fear into the hearts of Google's leaders......NOT.
Then there was the WSJ story recently about Gates commissioning his former aide to develop a Microsoft VOIP telephony business. Let's see....Vonage is already out front, and SBC/ATT and Verizon are having their own troubles just treading water in the voice business. What is it Microsoft is going to bring to this market, besides some of that now-famous $35B cash hoard?
Oh, wait, Google's positioned in that space, too, with instant messaging and email......oops!
Corporate failures are replete with examples of companies whose only contribution to a new product/market was the cash they burned through, to their shareholders' dismay. Ask Carl Icahn about Blockbuster.
What seems unfailingly clear to me, now, is that Bill Gates is doing his shareholders a tremendous disservice by hanging around Microsoft headquarters. I have been saying for months, in various posts, that his last five years at the helm of the company he founded have been disastrous. It's past time for him to go. When he looks so elated at the chance to give someone else's money away, and be rid of the job of creating shareholder value, it's time for him to do the right thing- right now. Not in two more years.
I have to believe that Bill is eager to have a full-time job at which he cannot fail. Oh, sure, maybe the Google guys will somehow convince Warren Buffett to give them part of the $37B promised to Bill and Melinda's foundation, but that's a stretch.
I think the sooner Bill totally and completely separates himself from Microsoft, and concentrates on giving away the billions in his foundation, the better it will be for Microsoft shareholders. A new Chairman might even sweep out some of that board deadwood and get a few competent business people in there to help oversee an overdue transformation, unlikely as it would be to succeed.
Better late, than never.
I caught part of the public relations event in which Bill, his wife, Melinda, and Warren Buffett announced the gift. Has anyone seen Bill Gates this happy and relaxed since his early days as a middling guest of Steve Jobs, when the latter was still doing battle with IBM in the mid-1980s?
Last month, I saw Gates interviewed on Donny Deutsch's "The Big Idea." When Deutsch asked Gates what Bill would say to the leaders of Google, if they were in the audience, Bill nervously mumbled something like, ".....ah...we're going to keep you guys honest." I wrote about it in this prior post. I'm sure that struck fear into the hearts of Google's leaders......NOT.
Then there was the WSJ story recently about Gates commissioning his former aide to develop a Microsoft VOIP telephony business. Let's see....Vonage is already out front, and SBC/ATT and Verizon are having their own troubles just treading water in the voice business. What is it Microsoft is going to bring to this market, besides some of that now-famous $35B cash hoard?
Oh, wait, Google's positioned in that space, too, with instant messaging and email......oops!
Corporate failures are replete with examples of companies whose only contribution to a new product/market was the cash they burned through, to their shareholders' dismay. Ask Carl Icahn about Blockbuster.
What seems unfailingly clear to me, now, is that Bill Gates is doing his shareholders a tremendous disservice by hanging around Microsoft headquarters. I have been saying for months, in various posts, that his last five years at the helm of the company he founded have been disastrous. It's past time for him to go. When he looks so elated at the chance to give someone else's money away, and be rid of the job of creating shareholder value, it's time for him to do the right thing- right now. Not in two more years.
I have to believe that Bill is eager to have a full-time job at which he cannot fail. Oh, sure, maybe the Google guys will somehow convince Warren Buffett to give them part of the $37B promised to Bill and Melinda's foundation, but that's a stretch.
I think the sooner Bill totally and completely separates himself from Microsoft, and concentrates on giving away the billions in his foundation, the better it will be for Microsoft shareholders. A new Chairman might even sweep out some of that board deadwood and get a few competent business people in there to help oversee an overdue transformation, unlikely as it would be to succeed.
Better late, than never.
Boeing's Failed Connexion Business Venture
Here's another sad story from the inept marketing deparment files.
No less a corporate giant than Boeing is reported to be considering sale or closure of its Connexion internet venture. This is the business unit that provides the service to airlines which allows passengers to connect to the internet in flight.
According to the Wall Street Journal, in last Thursday's edition, the business is probably on Boeing's books for $1B of asset value, but may only have a market value of $150MM.
What surprised me is the marketing strategy that Boeing used for this service. At fees of $10-27/flight, on commercial carriers, it seems rather pricey for the expense budget set. Can you imagine a road warrior defending hundreds of dollars of connection fees per trip to his or her manager?
Additionally, these days, you'd think the aforementioned warrior enjoys the relatively brief period of inaccessibility. Perhaps s/he can actually use the time to think and reflect about business, rather than respond pell mell to various assaults from the laptop, blackberry and cell phone.
Apparently, Boeing belatedly decided to work with Rockwell Collins to outfit corporate (and, one assumes, time share) jets with this service. Wouldn't you think this would have been the first segment they went after? The folks who fly these planes are, by definition, seen as executives whose time is more valuable than the ones who fly commercial. One would think they could more easily, if it's even necessary, justify the Connexion fees for their trips. If it didn't "fly" with this group, it wouldn't succeed in the larger business travel community. But, if it did show promise in this more elite segment, the business would at least have bought some time to make further penetration into the business travel market.
It's astonishing that such a relatively simple business could be mismarketed and mismanaged. Especially when owned and staffed by a capable, credible, large US company of Boeing's stature.
It is understandable that not all ideas work out. But you'd think the more adventurous ones would be led and staffed by a more diligent and sensible group that knew basic market segmentation concepts, and how to implement them.
No less a corporate giant than Boeing is reported to be considering sale or closure of its Connexion internet venture. This is the business unit that provides the service to airlines which allows passengers to connect to the internet in flight.
According to the Wall Street Journal, in last Thursday's edition, the business is probably on Boeing's books for $1B of asset value, but may only have a market value of $150MM.
What surprised me is the marketing strategy that Boeing used for this service. At fees of $10-27/flight, on commercial carriers, it seems rather pricey for the expense budget set. Can you imagine a road warrior defending hundreds of dollars of connection fees per trip to his or her manager?
Additionally, these days, you'd think the aforementioned warrior enjoys the relatively brief period of inaccessibility. Perhaps s/he can actually use the time to think and reflect about business, rather than respond pell mell to various assaults from the laptop, blackberry and cell phone.
Apparently, Boeing belatedly decided to work with Rockwell Collins to outfit corporate (and, one assumes, time share) jets with this service. Wouldn't you think this would have been the first segment they went after? The folks who fly these planes are, by definition, seen as executives whose time is more valuable than the ones who fly commercial. One would think they could more easily, if it's even necessary, justify the Connexion fees for their trips. If it didn't "fly" with this group, it wouldn't succeed in the larger business travel community. But, if it did show promise in this more elite segment, the business would at least have bought some time to make further penetration into the business travel market.
It's astonishing that such a relatively simple business could be mismarketed and mismanaged. Especially when owned and staffed by a capable, credible, large US company of Boeing's stature.
It is understandable that not all ideas work out. But you'd think the more adventurous ones would be led and staffed by a more diligent and sensible group that knew basic market segmentation concepts, and how to implement them.
Monday, June 26, 2006
Basic Business Skills Seen Lacking in Recent News Articles
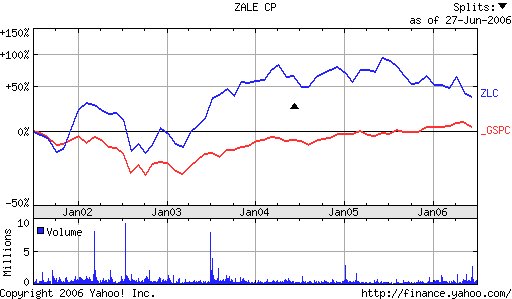
The Wall Street Journal featured two interesting articles last week which provide evidence of a continuing lack of skills in basic business management.
One piece concerned Zale jeweler's self-inflicted wounds over the two years. The chart at right (click on it for a full size version), from Yahoo, depicts the company's performance, relative to the S&P, for the past 5 years. Sure enough, the stock price has slid recently. What's interesting is that it was merely mediocre prior to that. It hadn't really fallen steeply since 2003.
According to the WSJ article, CEO Mary Forte assumed command and unilaterally took Zale from its low-end positioning as a purveyor of inexpensive diamonds, and frog-marched it upscale. Evidently on the basis of personal hunch and her affinity for upscale retail goods, Forte radically changed product mix and marketing plans. While the article paints a confused picture in which a board member, now interim CEO, alleges that Forte did not disclose the radical nature of her plans, a senior marketing officer claimed that she was refused a meeting with the board to explain the extent of the changes.
I find it amazing that, in this day and age, a major, albeit low-end, retailer like Zale could experience such seat-of-the-pants strategy and marketing shifts, amidst poor communications. As I have written regarding Wal-Mart's attempts to move upmarket, this kind of change is always fraught with risk. It's rare in retailing that a major company has successfully moved upmarket without taking a very, very long time to reposition itself.
A few days earlier, the WSJ ran a book review of a new tome from two BCG consultants. It is entitled, "Treasure Hunt," and provides the shocking news that consumers sometimes buy on price, and sometimes pay up for premium merchandise.
Stop the presses! Revamp the Wharton and Kellogg marketing curricula!
Really, are these guys serious? This has been a staple marketing truism since well before I went to undergraduate school in the late-1970s. That two consulting executives feel a need to illuminate the rest of us probably says more about their lack of knowledge of the past, and basic marketing, than about the novelty of their insights.
Truthfully, if these two guys, Michael J. Silverstein and John Butman, are surprised by these findings, would you want to pay them to learn more about business on your company's tab? The WSJ review by Laura Landro, for whom I have a good deal of respect, suggests that its unspecified citing of "BCG client work" for data, and its use of fairly generic insights on consumer buying behavior, makes it just the latest of a long series of popular rewrites of basic marketing knowledge and theory going back well over thirty years.
Once again, I wonder what it means that these authors thought they found something new, and someone thought this material of sufficient value to publish it. Probably that the average level of business acumen in US companies is far less than you really want to believe.
Mediocre MBA Applicant Pools
My partner and I were discussing the modern MBA full-time program the other day. Specifically, we were comparing notes on our situations as relatively inexperienced college graduates applying to Stanford and Wharton over 20 years ago, with a typical full-time, self-funded entrant to a top B-school now.
His point, with which I agree, is that business schools such as Columbia, Chicago, Stanford, MIT, Tuck, Harvard and Wharton, in all probability, no longer attract the best students to their day programs. Instead, they now attract a mediocre talent pool. This is largely because of the schools' insistence on substantial work experience by candidates prior to attending their programs.
Consider this. A bright young college graduate, after 4-5 years of experience, at a mid-large-sized company, is likely on a decent career path. These days, s/he could probably get the employer to pay for grad school. Otherwise, the potential B-school entrant has to forego two years' compensation, still pay for living expenses, plus the cost of grad school. Rough estimates for this are in the neighborhood, I believe, of $200K.
So, one has to ask, why would someone incur all that added expense, when an employer will consider funding a candidate and continuing to keep them on payroll, or perhaps give them leave, in order to retain top talent? One answer is, the current experienced, full-time, self-funded MBA candidate is not the most talented segment of potential program entrants.
My partner added, for good measure, the following hypothetical situation. If a young college grad is doing well at his or her job, some years out, would s/he really throw away all the progress, money, momentum, and contacts, for two years of self-funded school? A really good prospect can do better than taking him- or herself out of the workforce for two years on their own tab, only to have to start over career-wise.
And, in these days of leaner staffs and heavier workloads, perhaps the non-applicants get better experience and skills by remaining in the workforce, sans graduate degree, and taking on more responsibility. Perhaps this results in better-performing employees. Only two years ago, I read an HBR piece touting the MFA as the advanced degree of the future.
Frankly, even in my day, over two decades ago, quite a few of my fellow Penn grad students were far more interested in the added money they'd make upon graduation than in actually learning anything from their course work. Few had an active interest in learning a specific discipline, outside of career retreads wanting to enter the arcane world of M&A or financial instrument trading. I still read of 'best practices' in marketing which bear a striking similarity to those taught back when I was at Penn.
Perhaps this explains why, despite the usual outpouring of full-time business school grads from name programs, companies, on average, don't seem to run better, or make fewer management gaffes. It could well be that name-graduate business program education is of decent quality, but the students are not.
His point, with which I agree, is that business schools such as Columbia, Chicago, Stanford, MIT, Tuck, Harvard and Wharton, in all probability, no longer attract the best students to their day programs. Instead, they now attract a mediocre talent pool. This is largely because of the schools' insistence on substantial work experience by candidates prior to attending their programs.
Consider this. A bright young college graduate, after 4-5 years of experience, at a mid-large-sized company, is likely on a decent career path. These days, s/he could probably get the employer to pay for grad school. Otherwise, the potential B-school entrant has to forego two years' compensation, still pay for living expenses, plus the cost of grad school. Rough estimates for this are in the neighborhood, I believe, of $200K.
So, one has to ask, why would someone incur all that added expense, when an employer will consider funding a candidate and continuing to keep them on payroll, or perhaps give them leave, in order to retain top talent? One answer is, the current experienced, full-time, self-funded MBA candidate is not the most talented segment of potential program entrants.
My partner added, for good measure, the following hypothetical situation. If a young college grad is doing well at his or her job, some years out, would s/he really throw away all the progress, money, momentum, and contacts, for two years of self-funded school? A really good prospect can do better than taking him- or herself out of the workforce for two years on their own tab, only to have to start over career-wise.
And, in these days of leaner staffs and heavier workloads, perhaps the non-applicants get better experience and skills by remaining in the workforce, sans graduate degree, and taking on more responsibility. Perhaps this results in better-performing employees. Only two years ago, I read an HBR piece touting the MFA as the advanced degree of the future.
Frankly, even in my day, over two decades ago, quite a few of my fellow Penn grad students were far more interested in the added money they'd make upon graduation than in actually learning anything from their course work. Few had an active interest in learning a specific discipline, outside of career retreads wanting to enter the arcane world of M&A or financial instrument trading. I still read of 'best practices' in marketing which bear a striking similarity to those taught back when I was at Penn.
Perhaps this explains why, despite the usual outpouring of full-time business school grads from name programs, companies, on average, don't seem to run better, or make fewer management gaffes. It could well be that name-graduate business program education is of decent quality, but the students are not.
Sunday, June 25, 2006
"The Market, She Be Angry....."
My partner and I were, among the other topics I mentioned in my prior post, discussing how the media covers equity markets as if it is a living thing. Thus, the title, which my partner uttered comically to capture my description of CNBC's Bob Pisani's moronic commentary on equity market behavior last week during one of the down/flat days.
Despite the signs of investors waffling on the economy's health, Brian Wesbury commented that average mortgage interest rates are still a full point lower than they were during the last expansion. And the Fed is moving to ensure low, long-term inflation. Thus, there's no reason to expect the economy to suddenly sieze up and slide into a recession.
But, "the market, she be misguided" for now, I guess. The bulk of investors are too short-sighted, their memories too short, to see beyond a temporary period of seemingly mixed economic and market signals.
Of course, if they were otherwise, the better performers probably would not be better, because they would not be pre-positioned for the subsequent equity market rise, when these mediocre investors figure out there is no need to be cautious, and move back into equities.
I am reminded here of James O'Shaughnessy's admonition that even the best strategies can have periods of as long as two years of underperformance. Our own strategy strives for annual consistency, and has typically achieved it. Right now, with a market full of investors with no particular lasting directional disposition, our strategy is, as expected, underperforming. But it's only been so for a few months, and is unlikely to remain so for very long.
Researching the S&P's historical performance this morning, I found that it had a near-zero trailing 12-month return for several consecutive months only once in the last 15 years- from March, 1994, to January, 1995. Even now, the trailing S&P is above 6%. Last year's first half was similar to this year's in that, by the end of June, the market was negative for the year-to-date. What all this seems to indicate is that the last 3-4 months of weak market returns are unlikely to remain weak for long. Chances are that the index will either plummet or soar sometime within the next few months. And a strategy's relative, or even absolute, performance during these few months of investor indecision could well become moot in another 6 months.
".......the market, She be deliberating........."
Despite the signs of investors waffling on the economy's health, Brian Wesbury commented that average mortgage interest rates are still a full point lower than they were during the last expansion. And the Fed is moving to ensure low, long-term inflation. Thus, there's no reason to expect the economy to suddenly sieze up and slide into a recession.
But, "the market, she be misguided" for now, I guess. The bulk of investors are too short-sighted, their memories too short, to see beyond a temporary period of seemingly mixed economic and market signals.
Of course, if they were otherwise, the better performers probably would not be better, because they would not be pre-positioned for the subsequent equity market rise, when these mediocre investors figure out there is no need to be cautious, and move back into equities.
I am reminded here of James O'Shaughnessy's admonition that even the best strategies can have periods of as long as two years of underperformance. Our own strategy strives for annual consistency, and has typically achieved it. Right now, with a market full of investors with no particular lasting directional disposition, our strategy is, as expected, underperforming. But it's only been so for a few months, and is unlikely to remain so for very long.
Researching the S&P's historical performance this morning, I found that it had a near-zero trailing 12-month return for several consecutive months only once in the last 15 years- from March, 1994, to January, 1995. Even now, the trailing S&P is above 6%. Last year's first half was similar to this year's in that, by the end of June, the market was negative for the year-to-date. What all this seems to indicate is that the last 3-4 months of weak market returns are unlikely to remain weak for long. Chances are that the index will either plummet or soar sometime within the next few months. And a strategy's relative, or even absolute, performance during these few months of investor indecision could well become moot in another 6 months.
".......the market, She be deliberating........."
Friday, June 23, 2006
Current Equity Market Performance
I had a long meeting with my partner this week, and the topic of our portfolio strategy's performance arose. The strategy now trails the index by some 10 percentage points.
Earlier in the year, I was more perplexed and concerned by the portfolio's lackluster performance relative to the index. Now, however, it's clearer to me what is occurring.
Beginning with May's negative index return, the first this year, and continuing with a nearly equal performance so far in June, the S&P is now hovering at a 0% return for the year. Evidently, many investors have become so paralyzed and confused by various confusing signals regarding global economic activity and US inflation, that they are just treading water. They feel no compelling directional push from the mass of data.
As my partner and I discussed this, he asked if it were not true that, essentially, our position is, "we are right, and the market will come around sooner or later." Is this not rather arrogant, he thought? "Arrogant" may not have been the word he used- but his point was similar. Are we not "blaming" the market for our being behind, and accusing other investors of "getting it wrong" on equity valuations.
This led me to another application of my insight on mediocrity. If you search this blog for the term "mediocrity," or "mediocre," you will find several past blog posts which explain my thoughts on this important concept.
In the equity market, I believe that the vast preponderance of investors, institutional included, are mediocre, and, at times such as these, spend most of their energy being scared, trading aimlessly, and generally emitting no directional signal whatsoever.
We have a lot of apparently mixed signals in the market right now, if you aren't very savvy. There is the bugaboo of high energy prices. Then there's the Mideast situation overlay- Iran, Iraq, and even Nigerian supply issues. Commodity prices have been high, gold rose, and, in the US, the Fed is worried about the current rate of inflation.
Yet, US corporate performance is good, and commodity prices and demand signal continued healthy global growth.
My contention is that the "average" investor is now like a deer caught in the headlights of an oncoming car. S/he is frozen.
Taking a look at my portfolio selection process' recent results, I am struck by the continued significant presence of energy companies. Homebuilding fueled the portfolio's outstanding performance for some 18 months over the past two years. As the sector cooled, though, the companies in the sector that had been selected for the portfolio were gradually dropped by the process. Not so with energy. Something else is going on here. Despite this year's choppy return performance by many energy companies, they remain prominent in the model's selections.
My thinking is that this represents the system's reaction to a strong, if confusing, equity market situation. The portfolio strategy does worst with a near-zero index return. In times like these, growth equities are punished, but not so emphatically, for so long, as to justify shorting them.
Instead, we are in the position of remaining long prior to what I believe will be an awareness on the part of many market investors, later this year, that things are really quite attractive and healthy in the equity markets. Since our model is designed to be invested, and not in cash, we are now long, and, thus, behind a wavering market.
The recent occurrence of days of sharp gains and losses by the index and the portfolio, some approaching 4% daily, suggest to me that we are near a "bottom" of uncertainty-related trading. I expect that by summer's end, either the market will plunge, and our strategy will go short, or investors will realize that there is healthy fundamental global economic growth, and the equity market will advance sharply for several months.
Earlier in the year, I was more perplexed and concerned by the portfolio's lackluster performance relative to the index. Now, however, it's clearer to me what is occurring.
Beginning with May's negative index return, the first this year, and continuing with a nearly equal performance so far in June, the S&P is now hovering at a 0% return for the year. Evidently, many investors have become so paralyzed and confused by various confusing signals regarding global economic activity and US inflation, that they are just treading water. They feel no compelling directional push from the mass of data.
As my partner and I discussed this, he asked if it were not true that, essentially, our position is, "we are right, and the market will come around sooner or later." Is this not rather arrogant, he thought? "Arrogant" may not have been the word he used- but his point was similar. Are we not "blaming" the market for our being behind, and accusing other investors of "getting it wrong" on equity valuations.
This led me to another application of my insight on mediocrity. If you search this blog for the term "mediocrity," or "mediocre," you will find several past blog posts which explain my thoughts on this important concept.
In the equity market, I believe that the vast preponderance of investors, institutional included, are mediocre, and, at times such as these, spend most of their energy being scared, trading aimlessly, and generally emitting no directional signal whatsoever.
We have a lot of apparently mixed signals in the market right now, if you aren't very savvy. There is the bugaboo of high energy prices. Then there's the Mideast situation overlay- Iran, Iraq, and even Nigerian supply issues. Commodity prices have been high, gold rose, and, in the US, the Fed is worried about the current rate of inflation.
Yet, US corporate performance is good, and commodity prices and demand signal continued healthy global growth.
My contention is that the "average" investor is now like a deer caught in the headlights of an oncoming car. S/he is frozen.
Taking a look at my portfolio selection process' recent results, I am struck by the continued significant presence of energy companies. Homebuilding fueled the portfolio's outstanding performance for some 18 months over the past two years. As the sector cooled, though, the companies in the sector that had been selected for the portfolio were gradually dropped by the process. Not so with energy. Something else is going on here. Despite this year's choppy return performance by many energy companies, they remain prominent in the model's selections.
My thinking is that this represents the system's reaction to a strong, if confusing, equity market situation. The portfolio strategy does worst with a near-zero index return. In times like these, growth equities are punished, but not so emphatically, for so long, as to justify shorting them.
Instead, we are in the position of remaining long prior to what I believe will be an awareness on the part of many market investors, later this year, that things are really quite attractive and healthy in the equity markets. Since our model is designed to be invested, and not in cash, we are now long, and, thus, behind a wavering market.
The recent occurrence of days of sharp gains and losses by the index and the portfolio, some approaching 4% daily, suggest to me that we are near a "bottom" of uncertainty-related trading. I expect that by summer's end, either the market will plunge, and our strategy will go short, or investors will realize that there is healthy fundamental global economic growth, and the equity market will advance sharply for several months.
Thursday, June 22, 2006
Boeing v. Airbus: The Value of Executing Fundamentals

The Wall Street Journal has recently run several pieces on Boeing's resurgence at the expense of Airbus. Last Thursday, the article provided details of Airbus' sizable gamble on the A380.
What is very comforting to read is that Boeing learned what customers were doing- going for niche direct routes- and designed a plane for that. The 787 "Dreamliner."
Airbus, in contrast, continued to 'serve' the failed hub-spoke system, and launched an expensive program to produce the A380. As it turns out, there is little demand for the plane, even if it were not behind schedule and over budget.
Sometimes, success is just getting the fundamentals right when the other guy doesn't. Boeing excelled at the simple "blocking and tackling" of asking customers what they needed, what they were doing, and then provided a produce, the 787, tailored to those needs. Airbus did not.
As a result, Boeing's fortunes have steadily improved over the past several years (click on the chart above to see the larger version). Despite McNerney's recent arrival, and Boeing's past military program management/ethics problems, the commercial aircraft division seems to have done things right, and already begun to put Boeing on a path of consistent returns.
Wednesday, June 21, 2006
Cell Phone Video Content Provider Troubles
Last November, I wrote a piece about the likelihood that a lot of people will want to view video content over ipods and cell phones.
Yesterday's Wall Street Journal featured a piece that described the troubles of several new mobile media companies, including one involving ESPN.
While I continue to believe that an insufficient number of people will pay to watch large amounts of content on cell phones, I did not realize there is an additional wrinkle to these companies.
They are forming new mobile networks, using leased lines, to market their content. This seems incredibly risky. No wonder Mobile ESPN is having trouble.
These start-ups are betting they can lure users from current calling plans of Verizon or Cingular, for example, just to get the video content on the start-up network. I would have expected these firms to license their content to existing providers. Maybe, if they fail at their own networks, that's what they will revert to doing.
I have a feeling that the coming wave of mobile video is going to look an awfully lot like the first wave of internet retailing did in the late 1990s.
Yesterday's Wall Street Journal featured a piece that described the troubles of several new mobile media companies, including one involving ESPN.
While I continue to believe that an insufficient number of people will pay to watch large amounts of content on cell phones, I did not realize there is an additional wrinkle to these companies.
They are forming new mobile networks, using leased lines, to market their content. This seems incredibly risky. No wonder Mobile ESPN is having trouble.
These start-ups are betting they can lure users from current calling plans of Verizon or Cingular, for example, just to get the video content on the start-up network. I would have expected these firms to license their content to existing providers. Maybe, if they fail at their own networks, that's what they will revert to doing.
I have a feeling that the coming wave of mobile video is going to look an awfully lot like the first wave of internet retailing did in the late 1990s.
Monday, June 19, 2006
Oil's New Rules: Sovereign Producers Change The Game
I read last week's Wall Street Journal article on the changing nature of oil supply and demand with great interest, and I am sure I am not alone in that regard.
The picture painted by the piece is quite dark. America experiencing both the loss of substantial, easily-accessible quantities of oil, while also remaining a major consumer of oil, though by no means now necessarily the only large one. Add to this the knowledge that several other major consumers, India and China, are also paying up for access to, or ownership of, oil reserves, and the picture gets almost totally black.
Or does it?
Back in the 1960s and before, the era with which the article contrasts the present situation, the phrase "global economy" had nowhere near the same meaning it does today. Without repeating a lot of economic history which can be found elsewhere, suffice to say that the world's major economies are far, far more intertwined today than they were even 30 years ago, let alone 40+ years ago.
I suspect this matters in the case of oil supply and demand. Oil is an industrial input, as well as a consumer good. Suppose China gained ownership of most of the oil reserves needed to slake its thirst, to the exclusion of America. What then? Would not the corresponding slowdown in US industrial production and consumer consumption boomerang right back onto the very China which had caused the shortage? And would this not ratchet down their own economic activity level, wealth, standards of living, etc?
When the Saudis had that kind of power, all they would lose was money they didn't really need to spend. The Saudi economy didn't so much depend upon selling non-energy goods to the Americans, as the Indian and Chinese economies currently do. Now, the Saudis want to develop energy-related industries, but here, too, it's not clear they will benefit from this in the long term. The Chinese and Indians are different. If their exploitation of the ownership of oil reserves gets too draconian, the global economy will come crashing down on everyone's head, not just the the victim countries who don't own sufficient oil reserves.
Furthermore, those countries paying for long term oil supplies at nearly $70/bbl are now locked into those energy costs. So are their petrochemicals, and other goods and services downstream which require the oil feedstock or refined petroleum. Doesn't that mean that, if oil were to decline just to, say, $60/bbl, those countries are now at a $70/60 price disadvantage? Are not the sectors of their economies which used oil all going to be overpriced, relative to those countries acquiring supply on the spot or more near term forward markets?
How is locking in oil reserves at a high price different from: S&L's locking in deposits with high long term rates on the liabilities, or; insurance companies locking in investment product customers with unsustainable rates on GIC (guaranteed investment contracts), or; utilities securing long term natural gas supplies at historically high prices? Haven't we seen each of these three scenarios wreck a sector or some companies in the US sometime in the last 30 years?
If so, why shouldn't China and India meet similar fates if their recent acquisition of oil supplies prove to be at historically unsustainably high prices?
I may be wrong, and the US may truly be on the economic skids, thanks simply to its dependence on oil which it does not own nor to which it is not buying access. But something about the interlocking nature of the current global economy leads me to suspect that the end game is not as simple as the WSJ article makes it out to be.
For everyone's welfare, let's hope I'm onto something, and that the article's author overlooked some key differences between the 1960s' and today's global economy.
The picture painted by the piece is quite dark. America experiencing both the loss of substantial, easily-accessible quantities of oil, while also remaining a major consumer of oil, though by no means now necessarily the only large one. Add to this the knowledge that several other major consumers, India and China, are also paying up for access to, or ownership of, oil reserves, and the picture gets almost totally black.
Or does it?
Back in the 1960s and before, the era with which the article contrasts the present situation, the phrase "global economy" had nowhere near the same meaning it does today. Without repeating a lot of economic history which can be found elsewhere, suffice to say that the world's major economies are far, far more intertwined today than they were even 30 years ago, let alone 40+ years ago.
I suspect this matters in the case of oil supply and demand. Oil is an industrial input, as well as a consumer good. Suppose China gained ownership of most of the oil reserves needed to slake its thirst, to the exclusion of America. What then? Would not the corresponding slowdown in US industrial production and consumer consumption boomerang right back onto the very China which had caused the shortage? And would this not ratchet down their own economic activity level, wealth, standards of living, etc?
When the Saudis had that kind of power, all they would lose was money they didn't really need to spend. The Saudi economy didn't so much depend upon selling non-energy goods to the Americans, as the Indian and Chinese economies currently do. Now, the Saudis want to develop energy-related industries, but here, too, it's not clear they will benefit from this in the long term. The Chinese and Indians are different. If their exploitation of the ownership of oil reserves gets too draconian, the global economy will come crashing down on everyone's head, not just the the victim countries who don't own sufficient oil reserves.
Furthermore, those countries paying for long term oil supplies at nearly $70/bbl are now locked into those energy costs. So are their petrochemicals, and other goods and services downstream which require the oil feedstock or refined petroleum. Doesn't that mean that, if oil were to decline just to, say, $60/bbl, those countries are now at a $70/60 price disadvantage? Are not the sectors of their economies which used oil all going to be overpriced, relative to those countries acquiring supply on the spot or more near term forward markets?
How is locking in oil reserves at a high price different from: S&L's locking in deposits with high long term rates on the liabilities, or; insurance companies locking in investment product customers with unsustainable rates on GIC (guaranteed investment contracts), or; utilities securing long term natural gas supplies at historically high prices? Haven't we seen each of these three scenarios wreck a sector or some companies in the US sometime in the last 30 years?
If so, why shouldn't China and India meet similar fates if their recent acquisition of oil supplies prove to be at historically unsustainably high prices?
I may be wrong, and the US may truly be on the economic skids, thanks simply to its dependence on oil which it does not own nor to which it is not buying access. But something about the interlocking nature of the current global economy leads me to suspect that the end game is not as simple as the WSJ article makes it out to be.
For everyone's welfare, let's hope I'm onto something, and that the article's author overlooked some key differences between the 1960s' and today's global economy.
Saturday, June 17, 2006
Bill Gates' Retirement: Nice Idea, but Too Late
I read in Friday's Wall Street Journal that Bill Gates announced his retirement from Microsoft effective in two year's time. Ray Ozzie is to become "chief software architect," apparently effectively immediately.
As I have written before in this column, here, and here, I think this will be a good move, but at least two years too late. Ozzie had impeccable software design credentials before he came to Microsoft. Actually, better than Gates'. One technology veteran, whose name I do not recall, was cited as having credited Gates with inventing the "software in a box" business, but said Bill never really understood or came to terms with the 'free online software' approach that is currently gutting Microsoft's business model. Yes, it's time for Chairman Bill to go play with his billions and leave the serious business of rescuing Microsoft to more open-minded adults.
Rather than, as I suggested last fall, have Ozzie take a $20MM check down the road and start up a new company for Microsoft, Gates is stepping out of the way at the parent instead. Trouble is, the culture is still what it is, and Ozzie may have challenges changing it for the better. And Gates will be around the company for two more years.
Corporate history is replete with examples of how resistant to change companies are when the retiring leader remains "around." The best example I recall is Harry J. Gray, of United Technologies, hampering Rand Araskog after the so-called "transition" of leadership from the former to the latter. I'm sure there are other examples.
About the best that can be said of this change, for Microsoft shareholders, is that at least Gates is going to subject them to no more than two additional years of value destruction before making way for better, more objective and value-creating management. If the shareholders are lucky, Ray Ozzie won't have left in the meantime due to clashes with Ballmer or other long-time Microsoft veterans..
As I have written before in this column, here, and here, I think this will be a good move, but at least two years too late. Ozzie had impeccable software design credentials before he came to Microsoft. Actually, better than Gates'. One technology veteran, whose name I do not recall, was cited as having credited Gates with inventing the "software in a box" business, but said Bill never really understood or came to terms with the 'free online software' approach that is currently gutting Microsoft's business model. Yes, it's time for Chairman Bill to go play with his billions and leave the serious business of rescuing Microsoft to more open-minded adults.
Rather than, as I suggested last fall, have Ozzie take a $20MM check down the road and start up a new company for Microsoft, Gates is stepping out of the way at the parent instead. Trouble is, the culture is still what it is, and Ozzie may have challenges changing it for the better. And Gates will be around the company for two more years.
Corporate history is replete with examples of how resistant to change companies are when the retiring leader remains "around." The best example I recall is Harry J. Gray, of United Technologies, hampering Rand Araskog after the so-called "transition" of leadership from the former to the latter. I'm sure there are other examples.
About the best that can be said of this change, for Microsoft shareholders, is that at least Gates is going to subject them to no more than two additional years of value destruction before making way for better, more objective and value-creating management. If the shareholders are lucky, Ray Ozzie won't have left in the meantime due to clashes with Ballmer or other long-time Microsoft veterans..
"Efficient Markets" from the Wall Street Journal
This week saw the Wall Street Journal publish two pieces under the theme "efficient markets." Once again, I am disappointed with what they will fill 2/3 of their op-ed page. Each piece has some glaring faults, in my opinion.
The first, appearing Tuesday, was written by the retired head of George Mason University's law school, one Henry Manne. He makes a good conclusion, despite most of his article having little to do with it. Essentially, Manne draws a distinction between viewing market prices for a stock as primarily affected by the last, "marginal" investor/trader, and viewing them as the averaged guesses of a large number of buyers and sellers. He cites an intriguing-sounding book in this regard. So intriguing, I'll probably go to Amazon to buy the book, and forget Manne's name after next week.
In any case, Manne uses this contrast to argue for legalizing all "insider trading" which is not specifically prohibited by contracts, i.e., mergers and acquistions activity, or other confidential activities. What he proposes is that company officers not prohibited to trade because of confidential deal knowledge, be allowed to trade based upon their legal, but special, knowledge of their company. I have agreed with this point of view for decades.
Where Manne seems to wander into difficult terrain is in his critique of behavioral finance. After generally acknowledging it as a field, he vaguely dismisses most of its findings as 'prove in time to be less anomalous than was first thought,' but gives no particulars. He then castigates the field for having no general theory of why markets operate as they do. He then states that, this being the case, "some close approximation of the efficient market theory is still the most accurate and useful model of the stock market that we have."
I guess this is where I suggest that maybe a former law school Dean is the wrong guy to engage to write a moving treatise on the differences between behavioral finance proponents and efficient markets supporters. I find Manne's logic to be simply wrong. Nobody of whom I know has mandated that the field of behavioral finance must spring into being whole and possessing a full depth of decades of research on the order of that existing for efficient markets.
In fact, as Thomas Kuhn propounded several decades ago, in his work on the structure of scientific revolution, new schools of thought usually begin by nibbling away at the errors at the margins of theories of the reigning school. Only with time and resources does the newer theoretical school of thought build its own full theories to explain complete workings of systems.
Just because behavioral finance is now becoming more well-known and possessing of deeper research, does not mean we have to continue to accept the flawed reasoning of efficient markets theorists.
In my opinion, Manne could have begun his article with his citing of the book, "The Wisdom of Crowds, by James Surowecki, and it would have been more succinct and better reasoned.
The second part of this short series appeared in Wednesday's WSJ, again on the op-ed page. This article was authored by Jeremy J. Siegel, a Finance professor from one of my alma mater's, the University of Pennsylvania. His topic is the imminent rise of non-cap-weighted indices for financial asset management.
I won't go into the details of Siegel's arguments here, except to state that he believes it will soon be possible to use fundamental measures, such as sales or dividends, to weight indices for use in financial asset management. Siegel pounds away at one theme in particular- that these new indices would allow for higher average returns, and less volatility, than the various current cap-weighted indices, such as the S&P500, Russell, or Nasdaq.
There are, however, to problems with Siegel's positions. First, it is partially disclosed that he has been busily working to create just these types of 'new' indices with a private firm, WisdomTree Asset Management. So, in reality, this op-ed piece seems to be a thinly-disguised piece of public relations and "placed" advertising.
But the more substantive error Siegel makes is in arguing that the measurement function for a "successful," or "useful," index, is that is exhibit high returns with low volatility. It seems to me that he is confusing a market index with an investment strategy.
Indices such as the S&P500 are composed for a specific reason: to emulate the allocation of resources in the US economy, by sector. The S&P500 is actively managed in its membership by Standard & Poors, a McGraw-Hill unit, in order to provide a group of publicly-traded companies whose business activity and weighting are reasonably representative of the activity of the US economy. When you buy this index, you are, in effect, buying the performance of the US economy, broadly described. That's all it is. It's not supposed to have a target return or volatility.
It's the same with the Russell and Nasdaq, for their particular representations. The objectives are to represent some specific underlying economic activity, not to tailor an index to the point that it becomes an active investment strategy all on its own.
That said, I am disappointed that these two flawed pieces found there way, with such fanfare, onto the Journal's pages this week. One author writes badly-reasoned prose about a field that isn't actually his area of expertise, while another author completely misses the point of his subject and, instead, lobbies for his current business enterprise to be used to replace current market indices.
If this is an example of the WSJ's best efforts at financial market education and theoretical advancement, perhaps we now have a better understanding of why the markets are so dominated by such frenetic, emotional short-term trading activity. Market participants are unlikely to find much in the way of helpful insight in the pages of our nation's major business daily newspaper.
The first, appearing Tuesday, was written by the retired head of George Mason University's law school, one Henry Manne. He makes a good conclusion, despite most of his article having little to do with it. Essentially, Manne draws a distinction between viewing market prices for a stock as primarily affected by the last, "marginal" investor/trader, and viewing them as the averaged guesses of a large number of buyers and sellers. He cites an intriguing-sounding book in this regard. So intriguing, I'll probably go to Amazon to buy the book, and forget Manne's name after next week.
In any case, Manne uses this contrast to argue for legalizing all "insider trading" which is not specifically prohibited by contracts, i.e., mergers and acquistions activity, or other confidential activities. What he proposes is that company officers not prohibited to trade because of confidential deal knowledge, be allowed to trade based upon their legal, but special, knowledge of their company. I have agreed with this point of view for decades.
Where Manne seems to wander into difficult terrain is in his critique of behavioral finance. After generally acknowledging it as a field, he vaguely dismisses most of its findings as 'prove in time to be less anomalous than was first thought,' but gives no particulars. He then castigates the field for having no general theory of why markets operate as they do. He then states that, this being the case, "some close approximation of the efficient market theory is still the most accurate and useful model of the stock market that we have."
I guess this is where I suggest that maybe a former law school Dean is the wrong guy to engage to write a moving treatise on the differences between behavioral finance proponents and efficient markets supporters. I find Manne's logic to be simply wrong. Nobody of whom I know has mandated that the field of behavioral finance must spring into being whole and possessing a full depth of decades of research on the order of that existing for efficient markets.
In fact, as Thomas Kuhn propounded several decades ago, in his work on the structure of scientific revolution, new schools of thought usually begin by nibbling away at the errors at the margins of theories of the reigning school. Only with time and resources does the newer theoretical school of thought build its own full theories to explain complete workings of systems.
Just because behavioral finance is now becoming more well-known and possessing of deeper research, does not mean we have to continue to accept the flawed reasoning of efficient markets theorists.
In my opinion, Manne could have begun his article with his citing of the book, "The Wisdom of Crowds, by James Surowecki, and it would have been more succinct and better reasoned.
The second part of this short series appeared in Wednesday's WSJ, again on the op-ed page. This article was authored by Jeremy J. Siegel, a Finance professor from one of my alma mater's, the University of Pennsylvania. His topic is the imminent rise of non-cap-weighted indices for financial asset management.
I won't go into the details of Siegel's arguments here, except to state that he believes it will soon be possible to use fundamental measures, such as sales or dividends, to weight indices for use in financial asset management. Siegel pounds away at one theme in particular- that these new indices would allow for higher average returns, and less volatility, than the various current cap-weighted indices, such as the S&P500, Russell, or Nasdaq.
There are, however, to problems with Siegel's positions. First, it is partially disclosed that he has been busily working to create just these types of 'new' indices with a private firm, WisdomTree Asset Management. So, in reality, this op-ed piece seems to be a thinly-disguised piece of public relations and "placed" advertising.
But the more substantive error Siegel makes is in arguing that the measurement function for a "successful," or "useful," index, is that is exhibit high returns with low volatility. It seems to me that he is confusing a market index with an investment strategy.
Indices such as the S&P500 are composed for a specific reason: to emulate the allocation of resources in the US economy, by sector. The S&P500 is actively managed in its membership by Standard & Poors, a McGraw-Hill unit, in order to provide a group of publicly-traded companies whose business activity and weighting are reasonably representative of the activity of the US economy. When you buy this index, you are, in effect, buying the performance of the US economy, broadly described. That's all it is. It's not supposed to have a target return or volatility.
It's the same with the Russell and Nasdaq, for their particular representations. The objectives are to represent some specific underlying economic activity, not to tailor an index to the point that it becomes an active investment strategy all on its own.
That said, I am disappointed that these two flawed pieces found there way, with such fanfare, onto the Journal's pages this week. One author writes badly-reasoned prose about a field that isn't actually his area of expertise, while another author completely misses the point of his subject and, instead, lobbies for his current business enterprise to be used to replace current market indices.
If this is an example of the WSJ's best efforts at financial market education and theoretical advancement, perhaps we now have a better understanding of why the markets are so dominated by such frenetic, emotional short-term trading activity. Market participants are unlikely to find much in the way of helpful insight in the pages of our nation's major business daily newspaper.
Thursday, June 15, 2006
China's Burgeoning Car Market: Can It Save GM?
Tuesday's Wall Street Journal featured a long article discussing China's explosively growing demand for automobiles. Many statistics were cited, but, suffice to say, it would seem that China is among, if not the most, fast-growing countries for auto sales.
Midway through the article, it is mentioned that GM won a "coveted deal for a joint venture" to produce autos back in 1997. That was nine years ago.
My consulting friend, S, and I were chatting about this incredible market opportunity for car manufacturers and marketers in China.
Doesn't it seem odd that GM, which is mired in such difficulties in the American car market, doesn't appear to be doing more to dominate China's auto industry? Or at least take advantage of a new, fast-growth market in order to establish some strong brand positions?
The article recounted the many car producers who are far from world-class manufacturers. These in include a cell phone manufacturer and the city of Bejing. It was striking how casually producers enter the Chinese auto market. There are apparently virtually no barriers to entry. From the picture painted by the piece, one is led to believe that there is very little concentration of market share, nor standards for what passes as a marketable car in China.
I should stipulate here that I do not have detailed knowledge of GM's market position in China, nor the various market shares among leading vendors. However, as my friend S pointed out, this market opportunity is so large, it doesn't take a lot of complicated planning by the wizards at GM in Detroit to figure out that it would be a good idea to try to become the market leader in the fastest-growing car market on the planet, in, by the way, the world's most populous country.
When the article went on to enumerate the economic challenges of the growth of automobile ownership in China- gasoline consumption, infrastructure, environmental safeguards, air quality, gasoline quality and refinery capabilities- it seemed to me that there would, or should, be a role in the Chinese automotive sector for an experienced car manufacturer with valuable knowledge which could help make the Chinese auto sector more efficient, productive, and environmentally friendly.
Could GM not bargain its capabilities at introducing various safety, emission controls, and modern auto design and manufacturing methods, for more access to the Chinese car market, and more control over its venture(s)? When you think of what GM should be good at, these sorts of attributes come to mind, as the result of manufacturing cars in a mature market for decades. Even GM's lack of effective car design in the US wouldn't appear to matter too much in the Chinese market, given how many small-scale vendors are apparently pumping out cars of a rather commodity-like nature.
If GM can't add value to a relatively primitive market like China's burgeoning car market, what can it do? If it can't make a compelling case for adding value for the Chinese automotive sector, maybe its weakness in the US is symptomatic of a truly global dilemma for the ailing car company.
It just seemed odd to me that a major article about the Chinese auto industry, in the major
US daily business newspaper, barely mentioned the world's largest car company. Or anything about how GM plans to take advantage of this rare opportunity to exploit a very large and very fast-growing market for its products.
This really doesn't seem like rocket science, or a planning challenge that the GM execs in Detroit would have to spend much time to formulate. In the best case, they could even create a new, subsidiary in China which they could eventually spin off to existing shareholders, thereby transferring the value-added elements of the current company from its troubled US domicile to another entity.
If GM's knowledge and people are still valuable, they should be able to add value in a new market, like China, even more easily than the mature, highly competitive American car market in which they currently are struggling.
Midway through the article, it is mentioned that GM won a "coveted deal for a joint venture" to produce autos back in 1997. That was nine years ago.
My consulting friend, S, and I were chatting about this incredible market opportunity for car manufacturers and marketers in China.
Doesn't it seem odd that GM, which is mired in such difficulties in the American car market, doesn't appear to be doing more to dominate China's auto industry? Or at least take advantage of a new, fast-growth market in order to establish some strong brand positions?
The article recounted the many car producers who are far from world-class manufacturers. These in include a cell phone manufacturer and the city of Bejing. It was striking how casually producers enter the Chinese auto market. There are apparently virtually no barriers to entry. From the picture painted by the piece, one is led to believe that there is very little concentration of market share, nor standards for what passes as a marketable car in China.
I should stipulate here that I do not have detailed knowledge of GM's market position in China, nor the various market shares among leading vendors. However, as my friend S pointed out, this market opportunity is so large, it doesn't take a lot of complicated planning by the wizards at GM in Detroit to figure out that it would be a good idea to try to become the market leader in the fastest-growing car market on the planet, in, by the way, the world's most populous country.
When the article went on to enumerate the economic challenges of the growth of automobile ownership in China- gasoline consumption, infrastructure, environmental safeguards, air quality, gasoline quality and refinery capabilities- it seemed to me that there would, or should, be a role in the Chinese automotive sector for an experienced car manufacturer with valuable knowledge which could help make the Chinese auto sector more efficient, productive, and environmentally friendly.
Could GM not bargain its capabilities at introducing various safety, emission controls, and modern auto design and manufacturing methods, for more access to the Chinese car market, and more control over its venture(s)? When you think of what GM should be good at, these sorts of attributes come to mind, as the result of manufacturing cars in a mature market for decades. Even GM's lack of effective car design in the US wouldn't appear to matter too much in the Chinese market, given how many small-scale vendors are apparently pumping out cars of a rather commodity-like nature.
If GM can't add value to a relatively primitive market like China's burgeoning car market, what can it do? If it can't make a compelling case for adding value for the Chinese automotive sector, maybe its weakness in the US is symptomatic of a truly global dilemma for the ailing car company.
It just seemed odd to me that a major article about the Chinese auto industry, in the major
US daily business newspaper, barely mentioned the world's largest car company. Or anything about how GM plans to take advantage of this rare opportunity to exploit a very large and very fast-growing market for its products.
This really doesn't seem like rocket science, or a planning challenge that the GM execs in Detroit would have to spend much time to formulate. In the best case, they could even create a new, subsidiary in China which they could eventually spin off to existing shareholders, thereby transferring the value-added elements of the current company from its troubled US domicile to another entity.
If GM's knowledge and people are still valuable, they should be able to add value in a new market, like China, even more easily than the mature, highly competitive American car market in which they currently are struggling.
3M & McNerney
 Yesterday's Wall Street Journal contained an interview with Jim McNerney, former Jack Welch lieutenant, former 3M CEO, and recently-recruited Boeing CEO.
The interview depicted McNerney as a level-headed, self-effacing, sensible leader.
However, in several passages, he referred to his 3M stint. So I was curious to see what his track record was there. Upon Googling McNerney and 3M, I see that he joined them as their first outsider CEO in December of 2000. According to an article from the time, he said he was going to focus on growing 3M.
What's interesting to me is the pattern of 3M's stock price from about the time McNerney took the helm. Until then, looking back via the Yahoo-sourced chart from 1970 to the present, 3M had pretty much tracked the S&P500 in a lockstep fashion. As the index soared in the bubble years of the late '90s, 3M's trajectory remained more modest, and continued as such after the bubble's deflation in 2001.
As of 2002, however, the two lines crossed. This means that, after some 30+ years, an investment in 3M, aside from dividends, had basically matched the S&P, but done no better. In the three years that followed, two under McNerney, the company began to depart from its index-like performance pattern.
The company's stock price began to exhibit unevenness, with declines and stagnation mixed with a brief updraft in 2003. Then the trajectory fell as the index began to regain strength.
All in all, an ironic track record for McNerney. It appears that under his leadership, 3M's stock price path remained pretty consistent, suggesting that investors didn't really see much difference with McNerney running the company. The only significant changes were bad ones- the dips in price in this decade.
What is not evident in the McNerney era of 3M is a break with its own past stock price path. It failed to noticeably ignite sufficient investor confidence or interest to move its stock price trajectory above the long term path it has been on for 30 years. That is, until recently when it has uncharacteristically flattened.
Does this portend anything for Boeing? From where does McNerney's credibility come, if this is his recent post-GE track record? Surely Boeing's recent stock price performance doesn't yet reflect McNerney's actions. For the record, it hasn't really changed, either, in several years.
I know of nothing negative about Jim McNerney. The comments attributed to him in the WSJ piece seem promising. However, that's about all there seems to be on file to suggest he will lead Boeing where it has not been before this. If 3M is any indicator, I'm not sure I expect Boeing to show any signs of unusually better performance than before McNerney arrived.
I wonder on what basis the WSJ seems so positively disposed toward Boeing and McNerney, given this lack of evidence of his prior accomplishments at 3M.
Tuesday, June 13, 2006
Old Media in The New Internet Media World
Monday's Wall Street Journal carried an interesting in-depth piece about a television station in Grand Rapids, Michigan, struggling to cope with the effects of the internet on its business model and future performance.
I wrote about this a few months ago here. In that post, I discussed the larger issue of the broadcast networks' responses to internet-based entertainment.
Now, I see by this WSJ piece, that the changes are hitting home at the local station level already. According to the article, the television station's advertising revenues and viewership are shrinking, and it is scrambling to find ways of stocking a webpage with advertising-funded content.
As I ponder the end-game of this situation, I can't help but see a parallel to the troubles and solutions of daily newspapers a decade or more ago. Papers began to share printing plants, and, essentially, become differently positioned products freelancing off of the same production assets. It would not surprise me if local television stations, including the major city stations, do the same.
The article focused on the core expense item, local news gathering. Can something like this really pay for more than one television station in a market, when the major networks can't even make it pay nationally and globally anymore? Doubtful.
Instead, I'd expect that, over the next few years, competing local broadcast stations will pool their facilities and news gathering, perhaps simply merging into one station per local market. If not the latter, then at least sharing all possible resources, save on-air staff, content selection, and idiosyncratic local programming.
What caught me a bit off-guard as I read the article is how quickly the nascent internet entertainment wave is already eroding some of the grassroots businesses in old media. My consultant friend, S, may be surprised to learn how quickly a trend she feels is years off in affecting major media behavior and consumption, is already reshaping local broadcast media in the hinterlands.
We are already seeing the beginning of old media's forced changes in the face of the rise of the new, internet-enabled digital media world.
Yet another example of Schumpeterian dynamics at work without any overt organizing entity to guide it, save technological change and consumer behavioral responses.
I wrote about this a few months ago here. In that post, I discussed the larger issue of the broadcast networks' responses to internet-based entertainment.
Now, I see by this WSJ piece, that the changes are hitting home at the local station level already. According to the article, the television station's advertising revenues and viewership are shrinking, and it is scrambling to find ways of stocking a webpage with advertising-funded content.
As I ponder the end-game of this situation, I can't help but see a parallel to the troubles and solutions of daily newspapers a decade or more ago. Papers began to share printing plants, and, essentially, become differently positioned products freelancing off of the same production assets. It would not surprise me if local television stations, including the major city stations, do the same.
The article focused on the core expense item, local news gathering. Can something like this really pay for more than one television station in a market, when the major networks can't even make it pay nationally and globally anymore? Doubtful.
Instead, I'd expect that, over the next few years, competing local broadcast stations will pool their facilities and news gathering, perhaps simply merging into one station per local market. If not the latter, then at least sharing all possible resources, save on-air staff, content selection, and idiosyncratic local programming.
What caught me a bit off-guard as I read the article is how quickly the nascent internet entertainment wave is already eroding some of the grassroots businesses in old media. My consultant friend, S, may be surprised to learn how quickly a trend she feels is years off in affecting major media behavior and consumption, is already reshaping local broadcast media in the hinterlands.
We are already seeing the beginning of old media's forced changes in the face of the rise of the new, internet-enabled digital media world.
Yet another example of Schumpeterian dynamics at work without any overt organizing entity to guide it, save technological change and consumer behavioral responses.
Monday, June 12, 2006
Stock Buybacks
The Wall Street Journal ran a front page piece today discussing large cap companies' recent trend of busily buying back stock, and that this has been misleading investors as to the actual health of the business.
I confess to have been initially confused by this. Surely nobody seriously focused just on EPS, so that a reduction in equity which would arithmetically boost the ratio is seen as performance improvement? But, I guess the WSJ is, in effect, telling us that most analysts and investors are too inept to spot this.
More to the point, though, who cares about EPS? Growth is found up on the revenue line of the income statement. EPS is such a manufactured concept that I'm surprised, especially post-Enron, that anybody would consider the measure so crucial.
I don't really care much whether companies are buying back their stock or not, ceteris paribas. If they pay too much, I presume that investors will depress the stock's price even more by selling their shares. If it's a wise move, the price and total return should rise. However, it seems to me that the more important issue is whether companies are growing revenue in a consistently superior manner.
Focusing only on balance sheet antics seems to me to be a bit misplaced. My proprietary research has found that, for growth companies, balance sheet structure, per se, is not so important as maintaining revenue growth. If a company has to resort to stock buybacks to manufacture EPS growth, and relies on investors and analysts to not notice, then it's probably already in a bad position.
Certainly, buying back stock does signal that the company hasn't adequate prospects for the capital. Perhaps the shares are priced so that the buybacks are a profitable move for the remaining shareholders.
However, it continues to amaze me that the WSJ can be serious in believing that many analysts and investors rely on EPS data, and would fail to realize whether or not a company is manipulating the measure via stock repurchases.
Looks like I'm not the only one who believes that most analysts and institutional investors constitute a mediocre crowd that mindlessly pushes near-term stock prices around with little understanding of longer-term context.
I confess to have been initially confused by this. Surely nobody seriously focused just on EPS, so that a reduction in equity which would arithmetically boost the ratio is seen as performance improvement? But, I guess the WSJ is, in effect, telling us that most analysts and investors are too inept to spot this.
More to the point, though, who cares about EPS? Growth is found up on the revenue line of the income statement. EPS is such a manufactured concept that I'm surprised, especially post-Enron, that anybody would consider the measure so crucial.
I don't really care much whether companies are buying back their stock or not, ceteris paribas. If they pay too much, I presume that investors will depress the stock's price even more by selling their shares. If it's a wise move, the price and total return should rise. However, it seems to me that the more important issue is whether companies are growing revenue in a consistently superior manner.
Focusing only on balance sheet antics seems to me to be a bit misplaced. My proprietary research has found that, for growth companies, balance sheet structure, per se, is not so important as maintaining revenue growth. If a company has to resort to stock buybacks to manufacture EPS growth, and relies on investors and analysts to not notice, then it's probably already in a bad position.
Certainly, buying back stock does signal that the company hasn't adequate prospects for the capital. Perhaps the shares are priced so that the buybacks are a profitable move for the remaining shareholders.
However, it continues to amaze me that the WSJ can be serious in believing that many analysts and investors rely on EPS data, and would fail to realize whether or not a company is manipulating the measure via stock repurchases.
Looks like I'm not the only one who believes that most analysts and institutional investors constitute a mediocre crowd that mindlessly pushes near-term stock prices around with little understanding of longer-term context.
Sunday, June 11, 2006
Ben Bernanke and His Critics
The past two weeks have provided numerous pundits and corporate economists, not to mention various 'economics reporters,' to opine on Ben Bernanke and his Fed. Especially the FOMC.
I find this somewhat amusing. After allowing for a free press, and the general value of public discourse and exchange of ideas, I believe the current flow of opinions marks most of the sources as of limited acumen or experience.
Bernanke and his colleagues have very sensibly articulated two things. First, they are data-driven in their interest rate decisions for the US economy. Second, in today's circumstances, the current 2% inflation rate is at the upper end of their comfort zone.
You don't have to be a genius to understand their message. You could, with a little experience, quickly realize that Bernanke & Co. understand the long term damage that inflation will do to the US financial markets and economy. Thus, they are acting to slow the rise of inflation now. And they are competently using the data available to modern central bankers to do so. Further, they are behaving as a coordinated, smoothly-functioning team.
If anything, most of the pundits, aside from people like Brian Wesbury and John Rutledge, seem to be incapable of simply understanding current Fed behavior.
The way I look at it is thusly. There are roughly 100 million working Americans. I don't know the exact number, but this is close enough for purposes of my example. Of these people, only one can be chosen to be Fed Chairman. That means there must be at least 40 academic, corporate, and financial services economists who believe they, too, are in the "first rank" of their profession. Toss in a few consultants, some investment fund economists, and maybe you get to 60 people. Add another 5-10 media critics, and you are near 75.
But there's only one Chairman. And he's Ben Bernanke. The other 75 people are not. They may care about Bernanke's behavior and comments, but I really doubt he cares all that much about theirs. Nor should you.
This may be worth remembering in the months and years ahead. Bernanke and the Fed, to use a famous phrase, "stand on the shoulders of giants." Paul Volcker's and Alan Greenspan's Federal Reserves were perhaps the two best monetary policy leaders and administrations our country has had. The bar was pretty high when Bernanke was confirmed as Fed Chairman.
Rather than spend a lot of time worrying about the comments of 70+ also-ran economists, pundits and media reporters, I'm going to continue to focus on Bernanke's, and other Fed Presidents,' words and actions. Perhaps you should as well. It may make for more clarity and less wasted time and effort deciphering the comments of the people who didn't get Bernanke's job.
I find this somewhat amusing. After allowing for a free press, and the general value of public discourse and exchange of ideas, I believe the current flow of opinions marks most of the sources as of limited acumen or experience.
Bernanke and his colleagues have very sensibly articulated two things. First, they are data-driven in their interest rate decisions for the US economy. Second, in today's circumstances, the current 2% inflation rate is at the upper end of their comfort zone.
You don't have to be a genius to understand their message. You could, with a little experience, quickly realize that Bernanke & Co. understand the long term damage that inflation will do to the US financial markets and economy. Thus, they are acting to slow the rise of inflation now. And they are competently using the data available to modern central bankers to do so. Further, they are behaving as a coordinated, smoothly-functioning team.
If anything, most of the pundits, aside from people like Brian Wesbury and John Rutledge, seem to be incapable of simply understanding current Fed behavior.
The way I look at it is thusly. There are roughly 100 million working Americans. I don't know the exact number, but this is close enough for purposes of my example. Of these people, only one can be chosen to be Fed Chairman. That means there must be at least 40 academic, corporate, and financial services economists who believe they, too, are in the "first rank" of their profession. Toss in a few consultants, some investment fund economists, and maybe you get to 60 people. Add another 5-10 media critics, and you are near 75.
But there's only one Chairman. And he's Ben Bernanke. The other 75 people are not. They may care about Bernanke's behavior and comments, but I really doubt he cares all that much about theirs. Nor should you.
This may be worth remembering in the months and years ahead. Bernanke and the Fed, to use a famous phrase, "stand on the shoulders of giants." Paul Volcker's and Alan Greenspan's Federal Reserves were perhaps the two best monetary policy leaders and administrations our country has had. The bar was pretty high when Bernanke was confirmed as Fed Chairman.
Rather than spend a lot of time worrying about the comments of 70+ also-ran economists, pundits and media reporters, I'm going to continue to focus on Bernanke's, and other Fed Presidents,' words and actions. Perhaps you should as well. It may make for more clarity and less wasted time and effort deciphering the comments of the people who didn't get Bernanke's job.
Friday, June 09, 2006
Stagflation? You Ain't Seen Nothing Yet
This past week, Bill Griffith of CNBC began to speak of the return of "stagflation." In one of the network's seemingly endless "debates" between analysts whom they dig up from who knows where, Griffith asked both guests about "slowing" GDP growth and "rising" inflation possibly triggering the resurgence of the dreaded 1970's malady.
Talk about overreaction. The irony, of course, was that Griffith is old enough to actually recall stagflation, as am I, while his two guest economists were not. That said, Griffith sounded like some addled old codger.
Let me tell you, as far as "stagflation" goes, you ain't seen nothin' yet. Try interest rates at 18%. It's easy to read about it. But, you have to have actually lived in a functioning economy to understand it. Money market accounts yielding 12%. Lending still going on, but many loans simply refused, because bankers were too embarrassed to quote rates in the mid-20%'s, in order to cover risk.
And of course, inflation running in the teens.Yes, the 70s were truly a time of economic sickness. But it coincided with the years after the Fed was chaired by G. William Miller, surely one of the most inept men to have ever held the position.
Today, we have inflation running at a full 10 percentage points below what it was back in the late 1970s. Rates are a dozen percentage points lower as well. Using the word "stagflation" at this time, with this Fed, borders on irresponsible.
Additionally, we just had very strong global growth last year, and a torrid first quarter in the US. Basic economic activity is quite far from moribund. The private equity deals demonstrate how much confidence there is in current markets, that private investors are putting so much money directly into large businesses, in order to add even more value before spinning them back out.
Fortunately, both young economic pundits on the CNBC show that afternoon rapidly and forcefully dismissed Griffith of his mistaken notion. However, if there is any justice, he should have lost whatever on-air credibility he still had to that point.
With comments like "are we in danger of brink of stagflation" at this juncture in our economic history, Griffith makes a strong case for replacing him with someone of like business sense. Say, Regis Philbin or John Stewart?
Talk about overreaction. The irony, of course, was that Griffith is old enough to actually recall stagflation, as am I, while his two guest economists were not. That said, Griffith sounded like some addled old codger.
Let me tell you, as far as "stagflation" goes, you ain't seen nothin' yet. Try interest rates at 18%. It's easy to read about it. But, you have to have actually lived in a functioning economy to understand it. Money market accounts yielding 12%. Lending still going on, but many loans simply refused, because bankers were too embarrassed to quote rates in the mid-20%'s, in order to cover risk.
And of course, inflation running in the teens.Yes, the 70s were truly a time of economic sickness. But it coincided with the years after the Fed was chaired by G. William Miller, surely one of the most inept men to have ever held the position.
Today, we have inflation running at a full 10 percentage points below what it was back in the late 1970s. Rates are a dozen percentage points lower as well. Using the word "stagflation" at this time, with this Fed, borders on irresponsible.
Additionally, we just had very strong global growth last year, and a torrid first quarter in the US. Basic economic activity is quite far from moribund. The private equity deals demonstrate how much confidence there is in current markets, that private investors are putting so much money directly into large businesses, in order to add even more value before spinning them back out.
Fortunately, both young economic pundits on the CNBC show that afternoon rapidly and forcefully dismissed Griffith of his mistaken notion. However, if there is any justice, he should have lost whatever on-air credibility he still had to that point.
With comments like "are we in danger of brink of stagflation" at this juncture in our economic history, Griffith makes a strong case for replacing him with someone of like business sense. Say, Regis Philbin or John Stewart?
Media's New Obsession: Misunderstanding the Fed
It seems that the majority of our country's business media feels that it, too, must vette Ben Bernanke's ascension to Chairman of the Federal Reserve System. Aside from Brian Wesbury's recent excellent op-ed piece in the Wall Street Journal, most media pundits have been claiming that Bernanke is now focused on proving his credentials to them.
How drole. If you can't be Chairman of the Fed, tell everyone he has to prove himself to you. Thus, we have the untutored CNBC "senior economics correspondent" Steve Leisman babbling ceaselessly with his "guests" about Ben Bernanke's actions, thoughts, intentions, and performance. It's not that obtuse. I seriously doubt if Bernanke even cares what Leisman thinks or says.
Rather, as Wesbury wrote, Bernanke is busy simply repairing the damage of the on-again, off-again monetary policy which marked Alan Greenspan's last few years. Not to criticize Greenspan. He did a marvelous job under very difficult circumstances. However, the result of mopping up the aftermath of the burst technology investment bubble of 1999-2001 was some confusion as to which indicators to watch to manage monetary policy.
By historical standards, today's rates are very low. But direction and a sense of vigilance are important for the financial markets' long term health.
Despite the media's hand-wringing, the Fed continues to behave in the long term best interests of the US economy and financial markets. This past week's coordinated comments by Bernanke, Moskow, and the Atlanta Fed President, all addressing the current 2% rate of inflation as being 'at the high end of their comfort level,' were evidence of how effectively and professionally managed Federal Reserve System is. There is no mystery to anyone paying close attention to the FOMC members- they have repeatedly stated that their decisions on rate policies are data-driven.
The Fed is doing its job by managing inflation. The media continues to do its job of selling print/online eyeballs to advertisers by, when necessary, creating uncertainty where there is none.
How drole. If you can't be Chairman of the Fed, tell everyone he has to prove himself to you. Thus, we have the untutored CNBC "senior economics correspondent" Steve Leisman babbling ceaselessly with his "guests" about Ben Bernanke's actions, thoughts, intentions, and performance. It's not that obtuse. I seriously doubt if Bernanke even cares what Leisman thinks or says.
Rather, as Wesbury wrote, Bernanke is busy simply repairing the damage of the on-again, off-again monetary policy which marked Alan Greenspan's last few years. Not to criticize Greenspan. He did a marvelous job under very difficult circumstances. However, the result of mopping up the aftermath of the burst technology investment bubble of 1999-2001 was some confusion as to which indicators to watch to manage monetary policy.
By historical standards, today's rates are very low. But direction and a sense of vigilance are important for the financial markets' long term health.
Despite the media's hand-wringing, the Fed continues to behave in the long term best interests of the US economy and financial markets. This past week's coordinated comments by Bernanke, Moskow, and the Atlanta Fed President, all addressing the current 2% rate of inflation as being 'at the high end of their comfort level,' were evidence of how effectively and professionally managed Federal Reserve System is. There is no mystery to anyone paying close attention to the FOMC members- they have repeatedly stated that their decisions on rate policies are data-driven.
The Fed is doing its job by managing inflation. The media continues to do its job of selling print/online eyeballs to advertisers by, when necessary, creating uncertainty where there is none.
Thursday, June 08, 2006
Tesco's Exemplary Management
Tuesday's Wall Street Journal also carried a piece describing the superb marketing management of Tesco, the British grocery chain. It's wonderful to read of such sensible, informed, data-driven marketing and operations management in a large-scale firm.
That Tesco's skill has given Wal-Mart fits adds luster to the firm.
What struck me about Tesco's fundamental success ( the article does not mention, and I do not, presently, know its total returns for the past several years) is that it is really not much more than consistent, classic marketing management. Things I was taught almost 20 years ago at Penn's business school, where I studied marketing.
Tesco has combined its membership card with very good data analytics. Together, they allow Tesco's very capable managers to do that of which marketers always dream- know specific customer behaviors, and link pricing and product tactics to them.
The article describes both customer-segment management, as well as physical store management, using their member data. By comparing across stores, and customer segments, the Tesco management team has been able to add store features, products, etc, to both increase other store sales, as well as store sales in problem areas.
They really seem to have taken segmentation analyses, product strategy, and channel strategy about as far as I think I've seen it go, successfully.
What was illuminating was to read quotes from the managers of one of their lesser-performing competitors, Asda, who failed to appreciate the value of Tesco's member data. They really did not "get it." How powerful the combination of demographics, purchase data, and location are.
Again, as in my previous post regarding Howard Stringer at Sony, it's a pleasure to witness fine management in such a large-scale firm. These two pieces demonstrate what I mean when I write about the mediocre 70% of management. Here are two firms who are clearly way above that tranche. They either manage what they have in a consistently disciplined, successful manner, like Tesco. Or, like Stringer, they keep and refocus their assets and strengths, while coldly assessing their weaknesses and move to remedy those.
It's such a pleasure, amidst articles on GM, Intel, and Microsoft, to read about really self-aware, capably-managed firms like Tesco and Sony.
That Tesco's skill has given Wal-Mart fits adds luster to the firm.
What struck me about Tesco's fundamental success ( the article does not mention, and I do not, presently, know its total returns for the past several years) is that it is really not much more than consistent, classic marketing management. Things I was taught almost 20 years ago at Penn's business school, where I studied marketing.
Tesco has combined its membership card with very good data analytics. Together, they allow Tesco's very capable managers to do that of which marketers always dream- know specific customer behaviors, and link pricing and product tactics to them.
The article describes both customer-segment management, as well as physical store management, using their member data. By comparing across stores, and customer segments, the Tesco management team has been able to add store features, products, etc, to both increase other store sales, as well as store sales in problem areas.
They really seem to have taken segmentation analyses, product strategy, and channel strategy about as far as I think I've seen it go, successfully.
What was illuminating was to read quotes from the managers of one of their lesser-performing competitors, Asda, who failed to appreciate the value of Tesco's member data. They really did not "get it." How powerful the combination of demographics, purchase data, and location are.
Again, as in my previous post regarding Howard Stringer at Sony, it's a pleasure to witness fine management in such a large-scale firm. These two pieces demonstrate what I mean when I write about the mediocre 70% of management. Here are two firms who are clearly way above that tranche. They either manage what they have in a consistently disciplined, successful manner, like Tesco. Or, like Stringer, they keep and refocus their assets and strengths, while coldly assessing their weaknesses and move to remedy those.
It's such a pleasure, amidst articles on GM, Intel, and Microsoft, to read about really self-aware, capably-managed firms like Tesco and Sony.
Howard Stringer's New Sony Corp
Tuesday's Wall Street Journal featured a glowing piece on Howard Stringers, Sony's CEO. The article took the form of excerpts from Walt Mossberg's interview of Stringer at a recent conference on digitalization.
I have to say, from the piece, I like Stringer a lot. He seems to embody several great qualities in a leader. He seems both passionate, but deliberative as well. He has respect for his new company's strengths, but is wasting no time in remedying its weaknesses. He's not cowed by culture, nor language gaps. And he's not arrogant.
An acquaintance of mine from CBS had spoken glowingly of him there, when discussing his departure. She told me he also took a number of his best lieutenants with him to Sony. According to the article, he has also hired a key technology head from Apple, Tim Schaaff.
I like how Sir Howard appreciates Sony's vast product breadth, and finds strengths in it, as he also begins to pare back its excesses. He spoke eloquently about the new Sony Reader portable electronic book device. Stringer seems to share Steve Jobs' ability, in contrast to Bill Gates, to identify with his average customer, and passionately embrace a product he can "feel" is right.
From his remarks, I sense Stringer has the potential to fashion a turnaround at Sony by refocusing on successful exploitation of its classic strengths. By contrast, for instance, I think Gates and Microsoft are simply throwing money at new areas in which they have no particular advantage.
Sony isn't a member of the S&P500. I wish it were, because, based upon what I read this week, it could well become a good example of a firm on track to be consistently fundamentally strong and, then, consistently superior in its total returns to shareholders.
I have to say, from the piece, I like Stringer a lot. He seems to embody several great qualities in a leader. He seems both passionate, but deliberative as well. He has respect for his new company's strengths, but is wasting no time in remedying its weaknesses. He's not cowed by culture, nor language gaps. And he's not arrogant.
An acquaintance of mine from CBS had spoken glowingly of him there, when discussing his departure. She told me he also took a number of his best lieutenants with him to Sony. According to the article, he has also hired a key technology head from Apple, Tim Schaaff.
I like how Sir Howard appreciates Sony's vast product breadth, and finds strengths in it, as he also begins to pare back its excesses. He spoke eloquently about the new Sony Reader portable electronic book device. Stringer seems to share Steve Jobs' ability, in contrast to Bill Gates, to identify with his average customer, and passionately embrace a product he can "feel" is right.
From his remarks, I sense Stringer has the potential to fashion a turnaround at Sony by refocusing on successful exploitation of its classic strengths. By contrast, for instance, I think Gates and Microsoft are simply throwing money at new areas in which they have no particular advantage.
Sony isn't a member of the S&P500. I wish it were, because, based upon what I read this week, it could well become a good example of a firm on track to be consistently fundamentally strong and, then, consistently superior in its total returns to shareholders.
Tuesday, June 06, 2006
More on Management Mediocrity- Part 2: Airlines
Yesterday's Wall Street Journal featured yet another piece on inept long-term management. This time, we were treated to an in-depth explanation of how major airlines have apparently chosen to manage ineptly for years.
According to the Journal's article,
"The improving financial results posted by seven of the nation's 10 big airlines in recent months reflect a fundamental shift in strategy....The big carriers, which for decades have doggedly pursued market share at any cost, now are focusing just as aggressively on the profitability of each route and flight."
Imagine that. Actually measuring profitability on a flight and route basis, then choosing to stop flying the unprofitable ones. What kind of management were shareholders of these '10 big airlines' paying for all those years- dart throwing? ouija boards?
It isn't really necessary to reiterate in detail what the well-written article states. Airline after airline has finally gotten serious about operating on profitable routes, and adjusting their size to fit. Load factors are now expected to reach 85% this summer.
Isn't it about time, for an industry that has frequently been described as having lost money, on a cumulative basis, since the Wright brothers flew at Kitty Hawk at the dawn of the last century? According to the article, part of the profitability turnaround comes from a new generation of revenue management systems which allow for pricing decisions to take into account whether passengers are flying just one segment of a flight, or are a more lucrative passenger on a longer trip, of which the segment is but one part.
I'm reminded of the legendary Bob Crandall's comment that he wished he could have spun off American Airlines and kept the reservation system. Knowledge is power, and it looks like, in the airline industry, some rational managers, with better knowledge management tools, are finally gaining the upper hand.
Will this result in higher non-business fares and fuller airplanes? Doubtless. Of course, if that bothers you, why not wait til there's only one airline left on many routes, and pay their uncontested fare? Because the way things have been going, it's only a matter of time until something like that scenario was bound to occur.
I don't keep track, but so many airlines have been in, then out, then maybe back in, then out again, of Chapter 11, it's hard to recall the ones that have not filed for bankruptcy at some point.
That's no way to run a company, much less a sector. Business behavior like that signals too much capital committed to earn too few profits, and, thus, excess capacity. As if on cue, the article in the Journal notes that, these days, airlines are not chasing every expansion opportunity that occurs with a failed airline. Rather, they are focusing on development of added routes providing they are quickly and routinely profitable. What a concept!
Perhaps, in a backward-looking sort of way, airline executives have finally learned about consumer behavior in their business. Most non-business flyers appear to value price over brand, so that brand ubiquity added no value in that segment. Add in the ever-increasing pressure to avoid travel using email, instant messaging, and desktop- and laptop-based videoconferencing on inexpensive cameras, and you have a recipe for the disaster that occurred in the airline industry. Demand became hyper-price sensitive, and the internet contributed to the "discovery" of low prices, squeezing airline margins.
Apparently, empty feeder flights didn't deliver profitable customers and higher load factors when all routes are under pricing pressure.The eventual reaction, for airlines to survive, is to reduce capacity to the solidly profitable routes. It appears that in airline management, glamour is out, and sensibility is in.
Schumpeterian dynamics are alive and well in yet another part of our economy. And that, as usual, is a long term good thing for consumers and our economy.
According to the Journal's article,
"The improving financial results posted by seven of the nation's 10 big airlines in recent months reflect a fundamental shift in strategy....The big carriers, which for decades have doggedly pursued market share at any cost, now are focusing just as aggressively on the profitability of each route and flight."
Imagine that. Actually measuring profitability on a flight and route basis, then choosing to stop flying the unprofitable ones. What kind of management were shareholders of these '10 big airlines' paying for all those years- dart throwing? ouija boards?
It isn't really necessary to reiterate in detail what the well-written article states. Airline after airline has finally gotten serious about operating on profitable routes, and adjusting their size to fit. Load factors are now expected to reach 85% this summer.
Isn't it about time, for an industry that has frequently been described as having lost money, on a cumulative basis, since the Wright brothers flew at Kitty Hawk at the dawn of the last century? According to the article, part of the profitability turnaround comes from a new generation of revenue management systems which allow for pricing decisions to take into account whether passengers are flying just one segment of a flight, or are a more lucrative passenger on a longer trip, of which the segment is but one part.
I'm reminded of the legendary Bob Crandall's comment that he wished he could have spun off American Airlines and kept the reservation system. Knowledge is power, and it looks like, in the airline industry, some rational managers, with better knowledge management tools, are finally gaining the upper hand.
Will this result in higher non-business fares and fuller airplanes? Doubtless. Of course, if that bothers you, why not wait til there's only one airline left on many routes, and pay their uncontested fare? Because the way things have been going, it's only a matter of time until something like that scenario was bound to occur.
I don't keep track, but so many airlines have been in, then out, then maybe back in, then out again, of Chapter 11, it's hard to recall the ones that have not filed for bankruptcy at some point.
That's no way to run a company, much less a sector. Business behavior like that signals too much capital committed to earn too few profits, and, thus, excess capacity. As if on cue, the article in the Journal notes that, these days, airlines are not chasing every expansion opportunity that occurs with a failed airline. Rather, they are focusing on development of added routes providing they are quickly and routinely profitable. What a concept!
Perhaps, in a backward-looking sort of way, airline executives have finally learned about consumer behavior in their business. Most non-business flyers appear to value price over brand, so that brand ubiquity added no value in that segment. Add in the ever-increasing pressure to avoid travel using email, instant messaging, and desktop- and laptop-based videoconferencing on inexpensive cameras, and you have a recipe for the disaster that occurred in the airline industry. Demand became hyper-price sensitive, and the internet contributed to the "discovery" of low prices, squeezing airline margins.
Apparently, empty feeder flights didn't deliver profitable customers and higher load factors when all routes are under pricing pressure.The eventual reaction, for airlines to survive, is to reduce capacity to the solidly profitable routes. It appears that in airline management, glamour is out, and sensibility is in.
Schumpeterian dynamics are alive and well in yet another part of our economy. And that, as usual, is a long term good thing for consumers and our economy.
Monday, June 05, 2006
More On Management Mediocrity: Time Warner's Example
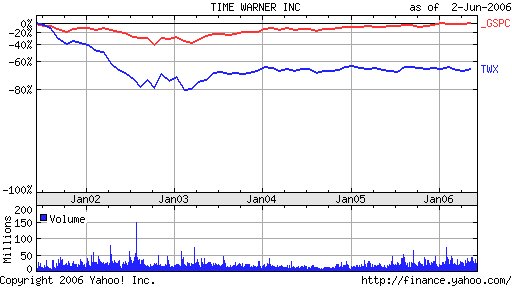
Friday's Wall Street Journal featured an article on Time Warner that provided, a very revealing look into the troubled media conglomerate's strategic difficulties stretching back all the way to the 1990 merger of Time and Warner Brothers.
Rather than focus exclusively on Time Warner's many missteps throughout the years since 1990, I'd like to treat it as an excellent example of how companies which people believe are run by deep ranks of talented, intelligent senior executives are, in fact, mismanaged by the confused bungling of mostly mediocre, turf-protecting senior executives.
As the article discusses some of the changes in the media sector over the past decade, it quotes Sumner Redstone of Viacom saying,
"We had a lot of clout from size. Look at where it got us- nowhere. The world has changed a lot. Success depends to a large extent on your ability to adapt."
It seems a little late for Redstone to be now realizing these truths. Size hasn't counted for as much as it used to since, oh, when IBM lost its early lead in PCs in the late-1980s. And when has the ability to adapt ever not been useful? It would appear that, like Redstone and Viacom, the Ross-Levin-Parsons regime of Time Warner also failed to appreciate the necessities of successful adaptation to changing environments.
Apparently, Time Warner's history is full of various warring groups from Time, Warner, HBO, and AOL, depending upon the era, protecting their own, or trying to grab another internal group's turf, for internal financial advantage. This type of multi-divisional energy expenditure is a sure way for a large company to be come a smaller company, if not simply never become larger, over time. Time Warner seems to have done just fine on this measure of "success."
While current TW President Jeff Bewkes is pushing each unit to be unsubsidized, he still manages a conglomerate, each of whose acquisitions were partially sold on the benefits of integration and expense sharing. So, what he is essentially doing, by running TW as a group of independent units, is admitting that more than a decade of mergers and acquisitions were sold to investors for ultimately indefensible reasons.
I don't think I read in the piece that any of the ex-senior executives, such as Gerald Levin, Nick Nicholas, Steve Case, or Dick Parsons are giving any of their easily-won compensation back as recompense to misled investors.
And, yet, after years of lackluster shareholder return performance, Parsons still maintains, "if you have the sum of the parts under your control, you can sometimes get to the market faster."
Yes, and that is reflected where, in the firm's stock price performance, Dick?
For background, I've pasted a Yahoo-sourced stock price chart for Time Warner, in comparsion with the S&P500, for the past five years. Prior to that, it is not clear whether the stock price used was AOL's, or Time Warner's, but it seemed to have been the former's, which would be moot for this post.
Viewing the chart, it's easy to see that TWX lost most of the 80% of value to the index by early 2003, and then slid a little bit more in the ensuing three years.
The WSJ piece further attributes to TW's 'executives' the belief that "...its breadth gives management a birds-eye view of the industry's shifting landscape and a better understanding of key issues."
Again, Time Warner seems to be able to do nothing for its shareholders with that 'birds-eye view and the 'better understanding of key issues.' My suspicion is that this is one of those cases in which a company would be better off dumping the unprofitably growing, or nongrowing divisions, and hire a tightly-controlled team of outside consultants to provide a cheaper 'birds-eye' view of the sector, from a truly objective perspective.
Media has surely been hit, and hit hard, by the incursion of digital technology over the last decade. It would be a pretty narrow-minded, dull management group indeed to believe that such dynamic value destruction and change in source of value creation, would lend itself to maintaining a large, slow-moving, bureaucratically-infighting-plagued conglomerate.
(Actually, as I write that, I'm reminded of Microsoft and Google, but that's for another post....)
As I wrote at the beginning of this piece, I don't wish to single out Time Warner, per se, for inept management, although they certainly have displayed it over the past five years. And, it appears from the WSJ article, if we could find the original Time Warner stock price history for 1990-2000, probably for that period as well.
Rather, I'd like to note how simply following the serial, failed expansions and merger integrations of more than a decade, alone, should have convinced a reasonable person that something was terribly amiss in the management of this company, or any company behaving in this fashion.
To continually destroy value via mergers, while simultaneously extolling the value of them, is ludicrous behavior. Why did anyone think the TW-AOL merger would ever work, with Time Warner's own checkered history of expansion?
Large firms often do have inept management. Track records of failure to consistently outperform the S&P500's total return do mean something. It's a shame that Time Warner has been able to reward senior management for fifteen years, while serially botching merger after merger, at their shareholder's expense.
My advice is, when you observe consistently mediocre, or worse, performance of a firm over several years time, take it seriously. Don't assume a turnaround is in the works any day soon. Don't assume the management responsible for the ongoing mediocre performance will wake up tomorrow, see reality, and change strategies on a dime. Rather, expect what you have heard from Dick Parsons of Time Warner for five years- continued justification for failed strategies and execution thereof. Then, sell the stock if you own it, and buy something with a better track record.
Subscribe to:
Posts (Atom)


