Walt Mossberg of the Wall Street Journal reviewed the new lineup of Apple's iProducts and Services in Wednesday's edition of the paper. He notes that, with the advent of Microsoft's Zune, and RealNetwork's Rhapsody, Apple has completely overhauled it's offerings.
Even if I did not own Apple's stock in my strategy's portfolio, I would appreciate the company's very aggressive product/market management.
Given the quickly-shifting sands of competition in this arena, Joseph Schumpeter would be very proud to see how Apple has rapidly cannibalized its own product line, in order to meet new competitive threats.
For instance, they have redesigned the low-end Shuffle, and pared the number of now mid-range offerings of the original iPod, and eliminated the iPod Mini altogether. Through a combination of pricing and product repositioning, the company has made room for new, higher-functionality entries in its iPod line.
It has also upgraded iTunes, the online entertainment content management system which is the companion to its iPod line, in time for the entry of the two new competitors' products.
The vagaries of consumer tastes may result in the loss of significant market share for Apple's products. Or it may result in the firm's continued dominance of the product/market. Either way, Apple won't lose share and growth because it stood still, became complacent, or milked the business.
It's a pleasure to see a leading company, like Apple, do such an admirable job in a key business, such as digital entertainment content, of moving ahead to change the competitive environment while it still can significantly effect that environment, rather than rest, and let new competitors control the terms on which competition will play out over the next few years.
Thursday, October 05, 2006


New Pension Liability Effects: Bracing for Negative Shareholders Equity
In a story with potentially large effects on the financial services sector, the FASB recently ruled to require the charging of pension obligations directly to equity. This is, according to observers of the situation, going to result in some major companies having negative equity.
To read more about the changes, you can go here. To quote from that site's article,
"That means huge liabilities could suddenly drop like a bomb onto balance sheets, putting any deficits squarely in the public view and possibly throwing some lending agreements into question because it may lead to sharp drops in corporate net worth.
Figuring out if any maneuvering is going on won't be an easy task. Investors will have to closely watch companies' assumptions for such things as health care and wage inflation that are used to determine the costs of defined benefit plans, which promise retirees a monthly check and often medical coverage.
For years, companies have gotten off easy by agreeing to such benefits without having to immediately set aside ample assets to cover them. Standard & Poor's estimates that the companies in its benchmark index offering such benefits held assets worth only $1.409 trillion in 2005 to cover $1.870 trillion in pension and other retiree-benefit obligations, resulting in a record deficit of $461 billion."
A Reuters article further noted,
"Investors may see some of the biggest changes in the balance sheets of companies like General Motors Corp., Ford Motor Co., Goodyear Tire & Rubber Co. and Exxon Mobil Corp., which maintain some of the largest U.S. pension and other post-retirement benefit plans.
Automakers, airlines, steelmakers and other manufacturing companies are likely to face the biggest obligations because of histories with unions and legacy costs, according to accounting analysts at Bear Stearns."
Let me note that all of this harks back to one of my earliest posts, from last September, about the long-lasting effects of the mutually-flawed bargains struck beginning 50+ years ago between American corporate and labor union leaders.
If the companies in question see their stock prices change materially from this FASB decision, then it suggests that the analyst corps was never doing an adequate job of understanding the true financial positions of these companies. If, on the other hand, the stock prices do not change materially, then it suggests that the existing measures weren't really all that useful to begin with, because they were in error, yet still in cited.
Analysts can't have it both ways, can they?
Late last week on CNBC, in an interview with an equity analyst, the first effect mentioned was that of screwing up traditional stock evaluation measures.
My own early work on valuation taught me about the inadequacy of measures such as Price/Earnings and Market/Book ratios, and other point-in-time balance sheet or income statement measures.
Now, it appears that those measures will have a permanently disjointed history that cannot be smoothed or calculated away. Furthermore, their future behaviors may now result in calculation-inhibiting values. This was always the case with using earnings, which can dip below zero, making growth calculations effectively insoluble. Now, even some balance sheet staples like basic Shareholder Equity will be unusable.
This is why I use simpler scalers with a time dimension in my analysis of companies' performances. Specifically, revenue growth and total return. No ratios.
I learned years ago, grappling with the more conventional ratios and snapshot measures, that they are subject to incomprehensible results, and, sometimes, literally incalculable ones.
By focusing on the quantitative expressions of a company's ability to consistently acquire and retain customers, at appropriate prices for the products and services they sell, i.e., revenue growth, and matching these values with investors' judgments on the adequacy of the resulting financial results, i.e., consistently superior total returns, my methods free me from the risk of accounting distortions.
Rick Santelli of CNBC Gets Even Smarter: The Impact of Derivatives On Spreads
This morning, as I was reading the Wall Street Journal and watching CNBC's Squawkbox, Rick Santelli was debating the recent confusion in the debt markets regarding inflation, interest rates, and economic growth.
Joining the debate were Joe Kernan, Steve Leisman, the show's under-educated 'senior economic reporter,' and a guest host.
Kernan is always a level-headed, sensible, and smart commentator. Leisman is typically self-impressed, and blind to his own lack of basic economic education.
Santelli, the network's Chicago-based reporter from the options pits at the CBOT, is among the most intelligent, informed, educated, and plain-spoken bond market reporters that I have ever seen on television. Bar none.
This morning, Rick gave the most lucid example I've ever heard of how the existence of credit derivatives affects, and has permanently affected, bond market spreads. He explained how, when one can buy protection for the drop in value of a bond, it necessarily puts upward pressure on the price, because the lowest value it can now attain is much higher than it otherwise would be.
He then went on to note that many people have missed this important development in the bond markets. And that even Fed officials might be misinterpreting the meaning of the now-closer spread relationships, versus their historic wider margins.
Leisman asked, to paraphrase,
"can it now be that, and I don't really understand this, that the bond markets are existing on one plane, setting rates, and the Fed is on another plane, or level, with its rate setting views?"
Santelli responded that, yes, the two might not agree contemporaneously, but in time, would gravitate to the bond market's view. Kernan laughed, and Leisman sort of looked puzzled, which was to be expected. But Santelli clearly meant that, over time, the closer spreads for yields between various debt instruments are here to stay, and the Fed will have to adjust to this. The money markets will overwhelm the Fed's interest rate manipulations every time, until the Fed takes the market's judgments into account.
What really impressed me is Santelli's matter-of-fact command of bond market reality, and its impact on economic theories that others believe are governing that reality.
He is one CNBC correspondent who I could watch all day, and probably never feel I'd learned everything I could by listening to him.
Wednesday, October 04, 2006
Monday on CNBC: The Conflicted Trader
I saw interviews with two 'traders' on CNBC Monday morning which yielded diametrically opposite views
First, Art Cashen, the florid-looking mossback from UBS, said that interest rates and Bernanke govern the market now. Period. Nothing else mattered.
Then a trader for another large broker was similarly questioned. He waffled on every question, giving no solid opinions whatsoever, except to say 'it all comes down to earnings'
So, there you have it. It's all about interest rates. Well, except when it's all about earnings.
Gee- thanks guys. I didn't think about either of these.
Once again, this anecdote of the conflicted floor traders shows how inane talking to brokers is. For the most part, they trade for clients- insitutional managers, other houses, and large private accounts. For the most part, all the brokers really 'know' is instantaneous order behavior.
Of course, they like to personify the 'market' because it adds presumed value and glamor to a business going totally electronic. Seriously, how can "the market" really know or care about the level of a single composit index, and truly behave differently as that level's old, nominally-valued maximum is exceeded?
One thing the piece did demonstrate- it takes different views to make a market, and even interviewing only two brokers already did that.
Tuesday, October 03, 2006
Professional Fund Manager's Erratic Behaviors
Saturday's Wall Street Journal featured an article about a Lehman fund manager, Jon Brorson, fretting over the recently monthly performances of the market indices, his fund, and what can be gleaned of US economic activity.
The article states, in part,
"Mr. Brorson's worries served him in May. Then, he shifted toward "defensive" companies whose sales tend to hold up in all kinds of economies, such as drug makers, food producers and electric utilities. His May move was gutsy -- and right. The Dow got to within 81 points of its record and then fell 8% into July.....Now, as it rises, he's fighting the trend again. .... His travails over the past two months show just how hard it is even for dedicated pros to call the turns. It's especially hard at times like these when investors are debating whether a shifting economy will change stocks' direction."
I see in this echoes of 'the broad market has it wrong' attitude, as he holds and waits. In fact, I can identify with the sentiment.
However, I also note how Brorson makes snap calls on fuzzy, unclear economic information. In effect, betting on the come. Then people judge his guess for the month.
If this is really the stock in trade of the average fund manager, I wonder how any of them develop consistent track records.
Wait! They don't, for the most part! The number of public fund managers who consistently beat the S&P is incredibly small. Forget doing it every year- even most years, it's unattainable on a consistent basis. Maybe this monthly micro-managing suggests why that is the case?
I would imagine that the kind of guesswork, based upon shifting, often wrong economic insights and confusing data, cannot be sustained for more than, say, a year. That is, if it is just a string of lucky guesses.
For instance, recently, many investors seemed to be worried that softening home prices will drag the economy into recession. However, just a few days ago, the Wall Street Journal carried an article by one of its reporters, Greg Ip, which noted the following,
"The overwhelming majority of mortgage debt and home-equity loans are held by Americans in the upper half of the income range. Households in the top 10% of income hold 42% of the value of home-equity lines of credit."
Thus, much of the risk of real-estate-related bad debt is overstated. This is the type of economic information that seems to go unnoticed or misinterpreted.
It's one of the reasons I don't buy and sell portfolio positions every month. Even supposedly firm economic data can mislead, e.g., the infamous, but nonexistent, spring 2005 "softening." Now, it is the 'recession,' or imminent 'soft landing,' in the face of continued economic data suggesting continued healthy growth.
Jon Brorson's concerns are ones I share. But I just don't see how changing one's strategy and spontaneously attempting to take advantage of a short-term economic will o'the wisp can lead to consistently superior total return performance over the long term.
Monday, October 02, 2006
The Rush By "Old Media" To Offer Online Video
Recently, I wrote, here, about Apple's iTV announcement, and its probably effect on cable TV providers going forward. Subsequently, I wrote about the recent Goldman Sachs media conference, here, discussing the rush of existing content library owners to dump....er......make deals for the distribution of their libraries to any and all digital channels while they still have value.
Then, last week, the Wall Street Journal ran an article in the back pages of the second section discussing the rush by all sorts of companies to offer online digital video now. The piece was entitled, "As Internet TV Gains Popularity, Cable Firms Bulk Up Offerings."
A nice idea, but a little late, as indicated by this line in the article,
"Video Web sites now draw users in numbers that rival those of cable or satellite companies. YouTube, the country's No. 1 online-video site, had more than 34 million unique visitors in August, according to Nielsen/NetRatings. MySpace was second with 17.9 million unique visitors. In comparison, Comcast, the country's largest cable company, has 24 million subscribers, and DirectTV, the largest satellite-TV provider that is owned by News Corp., has 15.5 million U.S. subscribers."
So the hi-speed access that came along with cable-TV has now grown to undercut the latter by allowing free, independent production and distribution of video content which is growing to rival the paid content on the original cable pay-TV systems.
If this situation doesn't demonstrate Schumpeter's visions of creative destruction at the extreme, where a firm's own success creates the undercurrent that hollows out its competitive position's strength, what does?
In this case, though, I think cable companies are myopic. Consider this closing quote from the WSJ article. The source of the quote, Steve Burke, CEO of Comcast, said, in reference to his own idea of
"creating an extensive viewing guide that would aggregate Comcast's TV schedule with online clips and video-on-demand options, giving people a mega portal for one-stop viewing shopping,"
"We're not alone in our aspiration to be that one place."
Now, I think that's the problem with old media's viewpoint.
There is, in my opinion, no "one place."
YouTube is 'one place,' alright, but hardly the "one place." It may not even be king of the hill in another year. That, of course, is the risk a potential acquirer will have to take.
The essential concept of internet-based, free video content sites almost guarantees no single site will be "the" site. Wherever a critical mass of video content may be gathered and offered, a viable site may be created. The company that has really missed the boat on this is, of course, Amazon.
Amazon, with its broad array of storefronts for independent book sellers/shippers, could easily have offered the same type of home to indie video producers, becoming the internet's video 'general store.'
Not anymore. That opportunity is gone, and, with it, Amazon's ability to capture anything beyond "me too" traffic and revenues.
It's simply incomprehensible to me how, having seen the future, a la YouTube, the CEO of Comcast still doesn't "get it," and is throwing money at an attempt to create, much further down the road, an omnibus, ostensibly partially-paid video site, to challenge a free one. Between Comcast and TimeWarner, one wonders if any old media companies will be worth more than a fraction of their current market values in a few year's time.
Kerkorian's Bold GM Gambit
You can't say Kirk Kerkorian isn't a bold poker player.
Friday's Wall Street Journal details his bid to buy an additional six million shares of GM, and plans to perhaps buy another six million. These stakes, if purchased, according to the Journal article, would make Kerkorian the second-largest GM shareholder, with a 12% position.
Although it looked like a losing position this summer, Kerkorian's original investment has now gained about 14%, thanks to GM's recent stock price rebound, on the basis of cutting deals with its unions over buyouts and layoffs.
The Journal piece characterizes the GM situation as becoming a sort of show down between CEO Rick Wagoner, who wants to slowly rebuild the company, if there's time, and Kerkorian, who wants a much faster, thorough restructuring, including a three-way alliance between GM, Renault and Nissan.
My recent thoughts on the GM situation can be found here. Suffice to say, I don't think GM is a viable performer, in terms of consistently superior total returns, without some sort of outside help or alliance.
Kerkorian is certainly playing a bold game, though. He could take his winnings off the table at this point, and have outperformed the S&P for the period. However, he chose instead to double-up, indicating he's after a much bigger gain, and prepared to invest the time and effort to secure it.
By moving to take a larger position, the betting is that, in the language of his SEC filing, "there should be strong GM board involvement" in assessing potential alliances. Meaning Kerkorian wants to outmaneuver Wagoner's internal attempts to scuttle the alliance, and get it approved by the board, out of Wagoner's direct reach and control.
It's hard to guess what the outcome will be in this case. There are so many options for Kerkorian, and the rest of the GM board. However, I don't recall Kerkorian leaving a situation like this with a loss. If he's prepared to add to his GM stake, then he must feel very confident that he can force the alliance, and reap the gains he expects from a resultant higher GM stock price.
In a sense, he can't lose, in the long term. If Wagoner's alleged "turnaround" really is more than short-term cost cutting, then the shares will rise, and Kerkorian makes more money. If Wagoner is wrong, Kerkorian, as the second-largest shareholder, through his employee, Jerry York, can probably force Wagoner's departure, and proceed with an alliance for GM. The only question at that point is whether or not Ghosn's Nissan is still open to the alliance, or has already tied up with Ford.
Could it be that Ghosn, watching from outside, could now hold off from a Ford alliance, and simply wait Wagoner out, knowing that Kerkorian will eagerly come calling, with less onerous terms than Wagoner has demanded?
It continues to be a phenomenonally interesting end-game for GM and Kerkorian, as the time to demonstrate a believable, lasting reversal of GM's fortunes grows shorter.
Friday, September 29, 2006
More on the Current Dow Frenzy and "Cute" Tickers
Today I have two Wall Street-oriented topics to address. One involves the recent fervor over whether the Dow will post a new all-time high. The other is about a recent article in the Wall Street Journal regarding 'catchy' ticker symbols.
My puzzlement over the Dow level revolves around the mistaken impression by so many analysts, market observers and pundits, that the precise level of a composite index matters over so long a time, to individual investors.
Among the more bone-headed, indefensible comments uttered in the last few days is that, now that the Dow may rise above its prior high, some unnamed investors, who apparently had their prior holdings frozen in time, will promptly unload all of their holdings, to finally book a gain.
Run that one by me again, please? Just because the Dow hasn't risen above its prior high of some 5-6 years ago has no relationship with how each individual equity, or even mutual funds, performed. Let alone what investors did with those positions.
Is it reasonable to believe that most investors have been hanging onto the same portfolio they owned 5 years ago? That's the only way that a new Dow high would actually unleash a flood of sell orders to finally rescue distressed equities that were underwater all of this time.
It just seems too absurdly foolish for anyone to think this way, but Mark Hanes and several others articulated just that view in the past few days.
A composite index is, admittedly, a function of its component parts. In the case of the Dow, that's only 30 industrials. So what about, say, the other 470 that are part of the S&P500 (I haven't checked, but I'm reasonably sure the Dow is a proper subset of the S&P), let alone the other 3000+ equities with liquidity in the market these days?
That's why I think the exact level of the Dow or S&P is mostly moot. Rather, the rate of change of an index is more useful in suggesting how investors may react, as they view a steady, or unsteady, progression of monthly returns of "the market," as narrowly represented by the Dow, or, more broadly, by the S&P500.
The other financial topic which caught my eye this week appeared in yesterday's WSJ. Entitled, "Does Stock by Any Other Name Smell as Sweet," it cited 'research' purporting that certain stock tickers, simply by virtue of their 'name,' cause, or are associated with, higher average returns, than other stock tickers.
The tickers in question, such as YUM, HOG, BID, and EYE, are thought to trigger more awareness in investors' minds. According to the article, researchers Adam Aiter and Daniel Oppenheimer claim to have found that pronounceable tickers which were bought and held on their first day of trading earned $85.35 more, on a $1,000 portfolio, than other tickers. Further, Pomona College's Gary Smith alleges that portfolios formed from "clever" tickers, from 1984 to 2004, had a return of 23.6%, against 12.3% for a 'hypothetical index of all NYSE and Nasdaq stocks.'
In neither case does the article mention average returns, or standard deviations, or the significance level of the stated performance differences.
What's more, both 'studies' suffer from a more glaring error. By using only one predictive variable, and measuring the difference in returns, or stock prices, they implicitly assign all performance differences, or their variances, to the stock ticker 'pronounceability' or 'cleverness' variable.
Does anyone truly believe this? Would you drop all of your other equity strategies right now, and invest in one of these two?
More reasonable would be a study in which the authors included a set of commonly-used predictive variables, and the stock ticker variable. Then the variance in performance of stocks, or portfolios, could be allocated to each predictive variable, or the predictive variables themselves could be factor analyzed, to assess shared association.
Either, or both, of these approaches would yield more believable, defensible, and useful conclusions to the question of whether the 'cuteness' of a stock ticker actually adds to its return potential.
It's disappointing to me that the Journal even printed this piece, let alone without much in the way of critical commentary on them. It did include one remark by an obscure finance professor from the University of Utah, who did at least suggest controlling for, rather than actually assessing the predictive power of, other predictive variables.
After all that, the article concludes by noting that the researchers themselves do not "recommend that people make trading decisions based on our findings."
What, then, was the point of this piece? Just entertainment? That would seem to be the Personal Section, would it not?
Have a great weekend!
Thursday, September 28, 2006
Today's Dow Frenzy

Dow closed 33.74 points shy of a record yesterday.
Now, every financial media personality is crowing that a new Dow high is within reach. As if that really matters.
CNBC's resident (endlessly) talking head, Bob Pisani, went over the top, explaining that this new high is crucial for investor confidence.
Well, I think he's only very partially right. This year is already seeing a positive Dow and S&P. And, by the way, it's the S&P which has the largest fund presence, so that is the index which would really matter. But it is not anywhere near as close to an all-time high as the Dow is.
It's not clear that a new high, whether on a close, or intra-day, really matters as much as steady, quarterly positive returns for the index.
But, leaving these behavioral questions aside, I see that, as usual, the on-air media is back to personifying "the market." I wrote about this last June, here.
This morning, CNBC rolled out the moss-backed Art Cashen, a floor-based executive of one of the Street's brokerage firms, and caught NYSE CEO John Thain in passing, to solicit comments calculated to heighten the drama of whether or not a new intra-day Dow high would be made.
If anything demonstrates to what degree media coverage of the capital markets is more about entertainment than reasoned assistance to investors, today's sorry spectacle would be it.
More Automotive Developments: Toyota, GM and Nissan
The automotive sector is once again in the news this week.
A Wall Street Journal article earlier this week reported on the self-parking Lexus LS460. Toyota, its developer, demonstrated this amazing technology in a parking garage 'within sight of Ford's Dearborn headquarters'.
The story made, in my opinion, several key points.
One was the story of the crystal headlight glass. Evoking the attention to detail that was involved in the legendary development, over 20 years ago, of the original Sony Walkman portable cassette player, the car's chief engineer painstakingly redesigned the headlights to more accurately resemble fine crystal. To do so, he actually had a crystal headlight made, then sent this to the supplier in order to be sure the latter had the exact "look" desired, from which to manufacture the production-grade headlights for actual assembly.
Second, Toyota is now enjoying, and employing, the accruing benefits of success, including internal funding for growth. The article mentions many measures of Toyota's recent success: profits, size, hiring plans, etc. Suffice to say, their attention to consumer tastes, desires, and the fulfillment of those, has driven it past Ford and GM in terms of profitability and recent growth rates.
It should have. That's how markets are supposed to work.
The Journal story's ending comment is noteworthy. It comments on Toyota's continuing 'inferiority complex.'
To quote the piece, "Unlike baseball pennant races, contests for sales and dominance in the (auto) industry never end."
That's entirely right. Joseph Schumpeter taught us that "the race" never ends- anywhere, anytime. Thus my search for consistently superior performance, which, in a well-run, well-positioned company, can be the resulting hallmark of this healthy inferiority complex of Toyota's.
Next, we have yesterday's and today's coverage of the Paris alliance talks between Carlos Ghosn of Nissan, and Rick Wagoner of GM.
Between the WSJ piece yesterday, and this morning's continuing coverage on CNBC, it's evident that, for better or for worse, Rick Wagoner is rolling the dice now, with all of GM's shareholders' money on the line.
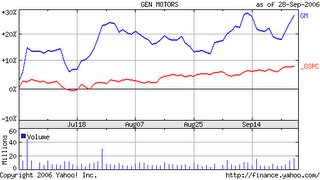 Personally, I find it laughable that anyone can call this year, based upon such brief and one-off events, a "turnaround" for GM. The chart on the left is what traders, analysts, and CNBC talking heads are all excited about right now. Over the past three and six months, GM's stock price is easily outperforming that of the S&P500.
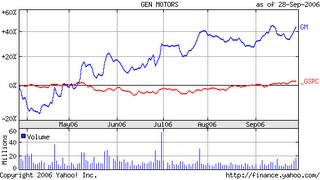 This, we are told, is the result of investors believing that GM is now in turnaround mode, and will return to automotive dominance imminently.
Not so fast....
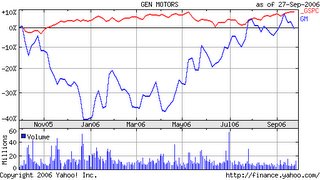
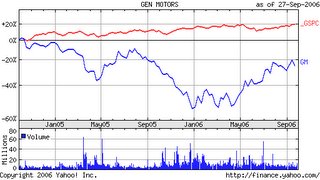 Here's what the charts look like for the past one and two years. Completely different, aren't they? GM is flat for the past twelve months, and down for the past two years.
Now I read, and hear, that GM's CEO is feeling so confident of his brief, one-time trick of shedding some labor costs, that he's decided to demand tribute from Carlos Ghosn and Nissan/Renault, should the two form an alliance. According to the Journal, GM wants a "multibillion-dollar payment" from Nissan and Renault.
 Wagoner is really a clever guy- give him that. He doesn't want this alliance. It was forced upon him by Jerry York and Kirk Kerkorian, his newest and most irksome board member and shareowner. How to evade the alliance? Loudly proclaim that a non-sales, non-customer-based, one-time financial cost reduction is, in reality, the much-heralded "turnaround," and then use that "fact" in order to make an unacceptable demand as a condition of any alliance with Nissan and Renault.
Yesterday's Wall Street Journal front-page piece, and this morning's coverage of the situation by CNBC, both cast doubt on the likelihood of any alliance being consummated. The most recent word is that the two parties have agreed to go away and reconsider terms, etc, for the weeks remaining in their 90-day alliance evaluation period which ends on October 15.
So Rick Wagoner is now "all in" with his shareholders' money. The Nissan/Renault alliance probably marks the last refueling stop on GM's uncertain road to recovery. If Wagoner successfully derails the alliance, then his shareholders better pray he has more up his sleeve than more job and cost cuts. And maybe Wagoner better check his own liability insurance for coverage from gigantic shareholder lawsuits for fiduciary breach.
Back to Toyota, though. Because that company figures in the GM alliance talks, too. According to Ghosn, Toyota is the company to beat, and he wants this alliance in order to have a decent chance of surviving that juggernaut's impending rise to global automotive dominance. Being a game of momentum and scale, Ghosn realizes that his companies have to be able to stay the course with enough capacity and design capability to match the Japanese giant, stride for stride, going forward.
Clearly, Ghosn isn't sure he has enough resources to do it presently. But GM may be demanding too high a price, and for an alliance that Ghosn doesn't even seem, based on his comments this summer, will even work effectively.
Once again, we see Schumpeter's theories in action. Wagoner is playing in his little Detroit fishbowl, and just wants Nissan/Renault, and Ghosn, to go away. Maybe to Dearborn, maybe back to Tennessee. Yet, GM can't really demonstrate a full-fledged, customer-based resurgence in its own fortunes at this time, nor, really, a very highly-probable scenario in the near future, either.
Ghosn, on the other hand, is running scared. Which is a good thing. He's competent, tough, and now, scared. Just like Toyota, his main adversary for the coming, pre-Chinese automotive sector rise, decade. That kind of healthy fear transforms companies into nimble, fleet customer-needs-serving, consistently superior total return performers. Not always, but it helps.
So now we have the lay of the land, in the microcosm of two of this week's automotive sector stories. Toyota demonstrates why it's the company to fear in the sector. Nissan's Ghosn demonstrates why he's the best bet for challenging Toyota globally. GM's Wagoner demonstrates that he's more interested in being left alone, to the potential detriment of his shareholders. And Ford is desperately hoping that maybe Ghosn will come back to call on them, and let them at least fight on the number two team, rather than alone, against Toyota.
A Wall Street Journal article earlier this week reported on the self-parking Lexus LS460. Toyota, its developer, demonstrated this amazing technology in a parking garage 'within sight of Ford's Dearborn headquarters'.
The story made, in my opinion, several key points.
One was the story of the crystal headlight glass. Evoking the attention to detail that was involved in the legendary development, over 20 years ago, of the original Sony Walkman portable cassette player, the car's chief engineer painstakingly redesigned the headlights to more accurately resemble fine crystal. To do so, he actually had a crystal headlight made, then sent this to the supplier in order to be sure the latter had the exact "look" desired, from which to manufacture the production-grade headlights for actual assembly.
Second, Toyota is now enjoying, and employing, the accruing benefits of success, including internal funding for growth. The article mentions many measures of Toyota's recent success: profits, size, hiring plans, etc. Suffice to say, their attention to consumer tastes, desires, and the fulfillment of those, has driven it past Ford and GM in terms of profitability and recent growth rates.
It should have. That's how markets are supposed to work.
The Journal story's ending comment is noteworthy. It comments on Toyota's continuing 'inferiority complex.'
To quote the piece, "Unlike baseball pennant races, contests for sales and dominance in the (auto) industry never end."
That's entirely right. Joseph Schumpeter taught us that "the race" never ends- anywhere, anytime. Thus my search for consistently superior performance, which, in a well-run, well-positioned company, can be the resulting hallmark of this healthy inferiority complex of Toyota's.
Next, we have yesterday's and today's coverage of the Paris alliance talks between Carlos Ghosn of Nissan, and Rick Wagoner of GM.
Between the WSJ piece yesterday, and this morning's continuing coverage on CNBC, it's evident that, for better or for worse, Rick Wagoner is rolling the dice now, with all of GM's shareholders' money on the line.
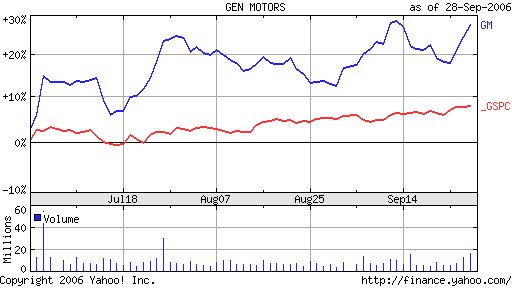 Personally, I find it laughable that anyone can call this year, based upon such brief and one-off events, a "turnaround" for GM. The chart on the left is what traders, analysts, and CNBC talking heads are all excited about right now. Over the past three and six months, GM's stock price is easily outperforming that of the S&P500.
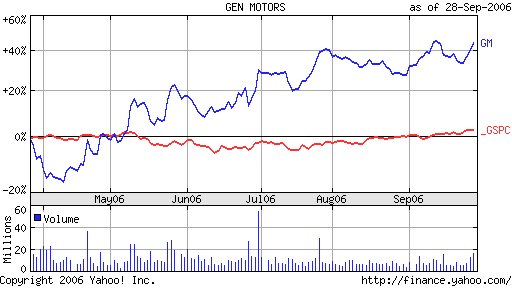 This, we are told, is the result of investors believing that GM is now in turnaround mode, and will return to automotive dominance imminently.
Not so fast....
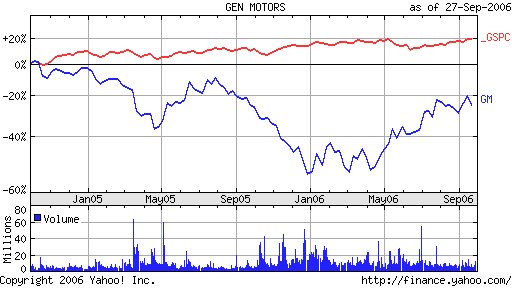 Here's what the charts look like for the past one and two years. Completely different, aren't they? GM is flat for the past twelve months, and down for the past two years.
Now I read, and hear, that GM's CEO is feeling so confident of his brief, one-time trick of shedding some labor costs, that he's decided to demand tribute from Carlos Ghosn and Nissan/Renault, should the two form an alliance. According to the Journal, GM wants a "multibillion-dollar payment" from Nissan and Renault.
 Wagoner is really a clever guy- give him that. He doesn't want this alliance. It was forced upon him by Jerry York and Kirk Kerkorian, his newest and most irksome board member and shareowner. How to evade the alliance? Loudly proclaim that a non-sales, non-customer-based, one-time financial cost reduction is, in reality, the much-heralded "turnaround," and then use that "fact" in order to make an unacceptable demand as a condition of any alliance with Nissan and Renault.
Yesterday's Wall Street Journal front-page piece, and this morning's coverage of the situation by CNBC, both cast doubt on the likelihood of any alliance being consummated. The most recent word is that the two parties have agreed to go away and reconsider terms, etc, for the weeks remaining in their 90-day alliance evaluation period which ends on October 15.
So Rick Wagoner is now "all in" with his shareholders' money. The Nissan/Renault alliance probably marks the last refueling stop on GM's uncertain road to recovery. If Wagoner successfully derails the alliance, then his shareholders better pray he has more up his sleeve than more job and cost cuts. And maybe Wagoner better check his own liability insurance for coverage from gigantic shareholder lawsuits for fiduciary breach.
Back to Toyota, though. Because that company figures in the GM alliance talks, too. According to Ghosn, Toyota is the company to beat, and he wants this alliance in order to have a decent chance of surviving that juggernaut's impending rise to global automotive dominance. Being a game of momentum and scale, Ghosn realizes that his companies have to be able to stay the course with enough capacity and design capability to match the Japanese giant, stride for stride, going forward.
Clearly, Ghosn isn't sure he has enough resources to do it presently. But GM may be demanding too high a price, and for an alliance that Ghosn doesn't even seem, based on his comments this summer, will even work effectively.
Once again, we see Schumpeter's theories in action. Wagoner is playing in his little Detroit fishbowl, and just wants Nissan/Renault, and Ghosn, to go away. Maybe to Dearborn, maybe back to Tennessee. Yet, GM can't really demonstrate a full-fledged, customer-based resurgence in its own fortunes at this time, nor, really, a very highly-probable scenario in the near future, either.
Ghosn, on the other hand, is running scared. Which is a good thing. He's competent, tough, and now, scared. Just like Toyota, his main adversary for the coming, pre-Chinese automotive sector rise, decade. That kind of healthy fear transforms companies into nimble, fleet customer-needs-serving, consistently superior total return performers. Not always, but it helps.
So now we have the lay of the land, in the microcosm of two of this week's automotive sector stories. Toyota demonstrates why it's the company to fear in the sector. Nissan's Ghosn demonstrates why he's the best bet for challenging Toyota globally. GM's Wagoner demonstrates that he's more interested in being left alone, to the potential detriment of his shareholders. And Ford is desperately hoping that maybe Ghosn will come back to call on them, and let them at least fight on the number two team, rather than alone, against Toyota.
Wednesday, September 27, 2006
More on Media from the Goldman Conference: Old vs. New
Last week’s Goldman Sach’s media investors’ conference was the subject of a recent Charles Schwab daily market email, to which I subscribe.
In part, it read,
“Investors could be forgiven for wondering if they had stepped into the wrong conference on Tuesday. Old media executives talked up digital strategies even as YAHOO warned of an unforeseen advertising shortfall. It appeared that old and new media companies had swapped roles for a day. While many blue chips slipped on Tuesday, a handful of media stocks rose after top executives at WALT DISNEY CO., VIACOM INC. and TIME WARNER INC. declared at the conference commitments to exploit the Internet to serve viewers anywhere, on any device. Meanwhile, Yahoo Inc. watched its shares fall after disclosing that two key advertising segments, autos and financial services, were weaker than expected. The panic selling of Yahoo appeared to do little to shake the resolve of media executives, some of whom once considered the Internet little more than an interesting sideshow. What's up for one-time Internet-skeptic NEWS CORP. next year? "To continue to drive into the digital transformation," Chief Executive Rupert Murdoch told investors. Murdoch's own stock on Wall Street has surged after buying one of the fastest growing Internet properties, MySpace.com, last year. Disney CEO Bob Iger took the opportunity to reveal it had sold $1 million of movie downloads on APPLE COMPUTER INC.'s iTunes in just a week.”
It does seem ironic that the “old” media companies are scrambling pell-mell to secure outlets for their aging content libraries, while the “new” media Yahoo was visibly weakened during the conference.
However, I don’t think Yahoo’s experience holds any import for the clutch of old media firms. As I have written here recently, Yahoo is probably the weakest of the “new” media firms, if you can rightly call it that. It doesn’t really offer content, what it does offer is mostly for free, and it isn’t really distribution, either.
Rather, what does not surprise me is that TimeWarner, Disney, Viacom and News Corp are frantically trying to sell or lease their video and audio content before it becomes eclipsed by the potential all-online production and distribution model.
Consider the prospect, in the current online environment, of some hot TV producers and rising new stars on YouTube going directly to consumers online with new films. It’s not as far-fetched as it may at first seem. Right now, on YouTube, one can view smart, interesting videos with great production values, running to more than 10 minutes. From there, it’s not a huge step into feature-length films. All it will take is some promotion on a YouTube channel, a URL, provision to take payments using PayPal, and broadcast and theaters have become disintermediated. A few years of this, and the content libraries of those old media titans will begin to be barren of recent goods, and only have aging stock gathering cyberdust.
Of all the old media names, I would hypothesize TimeWarner may be in the most precarious situation, this week’s analysts’ upgrades notwithstanding. As an owner of significant distribution and content assets, nobody trusts it. Other distributors can’t be assured of continued access to TW content. Other content providers worry that they will be locked out of, or given inferior access/terms, on TW’s cable systems. No company has managed consistently superior total return performance as an integrated media distribution and content firm yet. I doubt TimeWarner’s going to be the exception.
Add to this Apple’s impending release of iTV, about which I wrote here, and the downfall of old media becomes more likely. With an easy method of downloading new, online-marketed content from URL to PC, then, wirelessly to the Apple-provided, or one of its competitor’s, servers, and then via wires to consumers’ living room TVs, broadcast’s weakness becomes more glaring.
It’s really…well…entertaining, to watch the media sector change almost quarterly, as old media hurries to extract some value for its content, while new media distribution races ahead by allowing anyone to produce and market content, bypassing traditional media.
Dare I write, “stay tuned?”
Tuesday, September 26, 2006
Immelt's Five Year Anniversary As GE CEO
On September 11th, The Wall Street Journal ran a celebratory piece on Jeff Immelt's five-year anniversary as GE's CEO.
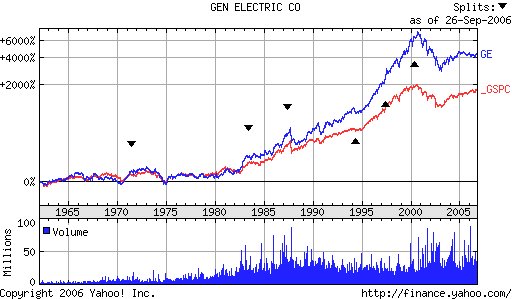
The Yahoo-sourced chart on the left depicts how Immelt's reign compares with those of prior CEOs of the company (Phillippe, Borch, Jones, Welch) going back to the early 1960s.
It's fair to say that long timeline charts such as this one can downplay earlier rough spots, since the end periods tend to have magnified appearances. For instance, the late-80s drop in stock price, coinciding with the 'crash' of 1987, is significant for its time, but pales in comparison to the absolute drop of the last few years.
 That being the case, here's a five-year view of the same information, corresponding to Immelt's tenure as CEO.
It seems to me that the WSJ is giving Immelt, and GE, the kid glove treatment. Maybe it's because of the fear of loss of GE's advertising revenues, and access to future stories.
However, looking at this Yahoo chart, it's difficult to understand how an industrial conglomerate can have underperformed the S&P500 through these particular last five years, and not be seen as needing to be led by someone else, or simply broken up.
Ask yourself this question:
If GE did not exist today, would someone create it as it currently exists?
I think the answer would almost certainly be, "no." What possible value would investors see in a TV network and movie studio buying: a jet engine business, a locomotive business, a financial services business, and power generation systems businesses, to name a few. There's absolutely no business synergies whatsoever that are unique to these businesses.
As I wrote here early last month, there is no longer any apparent value to the constituent business units of GE being assembled as GE.
Rather than observe the data I did in my earlier piece, the Journal contained quotes like this one, from Immelt's lieutenant, Bob Wright, vice chairman and head of GE's entertainment sector,
"He's in a good dynamic for a guy who has a lot of weight on his shoulders."
Does anybody reading this understand that sentence? Maybe Wright meant this,
"He's making a heckuva lot of money for a guy who has a lot of weight on his shoulders from not delivering for his shareholders."
Toward the end of the article, we perhaps get a clue as to why Immelt's GE is foundering so badly. The Journal relates that Immelt "urges employees to make bigger bets without fearing for their jobs if they fail." "Make it personal," the piece quotes GE's CEO as saying.
So now we have the 'kinder, gentler,' GE in evidence. Maybe Immelt figures, if he is kind to his employees, and forgives lack of performance, or consistently poor investment judgment, his board will do the same for him. Seems to be working, right?
In the end, all of Immelt's changes are not affecting the company's total returns. He can globalize the behemoth, ask his managers to take more risks, and even shuffle businesses in and out of the GE portfolio.
But in the end, over five years, Immelt simply has failed to lead GE to consistently superior performance, while raking in a royal compensation, as I noted here, back in March. In that post, I observed that Immelt has already received at least $21MM in cash compensation for failing to create consistently superior total returns for his shareholders. There's no way he needs to take the risks evidently necessary to make GE's long-term performance superior to the S&P's.
Furthermore, why give up this multi-million dollar gravy train and break the company up?
In this era of concern over "corporate governance," I'm frankly disappointed that the Wall Street Journal gave Immelt such an easy pass while reviewing his first five years at the helm of GE.
A year ago, I wrote, prior to almost any well-known pundit or industry analyst, that Ford and GM were in major trouble. Especially Ford. Back then, I opined that maybe the old media and investment banking giants weren't being candid, because the slowly-dying auto giants still paid a lot of bills for companies in those sectors.
I wonder if the same thing is occurring now, with GE. The truth would be very, perhaps too, costly to the media and financial service sectors, wouldn't it?
Monday, September 25, 2006
Retail Notes
I read two interesting pieces recently in the Wall Street Journal regarding retail commerce.
On Thursday, the paper's Marketplace section reported how widely flat-panel TV retailing has spread. Companies as diverse as Office Depot, Home Depot, Costco and Kohl's have jumped into the fray. Until now, conventional local TV retailers, and big box electronics outlets like Circuit City and BestBuy have been responsible for much of the sales volume of flat-panel TVs.
As prices for the new TVs fall, and larger models hit price points below $2,000, low-price retailers such as Wal-Mart and Costco are becoming a larger part of the retailing market.
It's not surprising that so many retailers are drawn to an almost-sure thing- the rise in popularity, as prices fall, of flat-panel television. Of course, if these companies do realize tremendous sales growth from the products, then, at some point, they face a dilemma in replacing that sales growth, or lapsing back into slower-growth modes. And that type of pattern typically keeps companies from earning consistently superior total returns over a number of years.
With so many retailers entering this product/market, it suggests that the production capacities for these TVs, probably in the Far East, must be very large. It doesn't require a lot of thought to envision some pretty vicious retail price competition, as a flood of flat-panel models pour into the US market in the next few years.
On another retail topic, today's Journal catalogued a number of states and municipalities which are passing, or have passed, anti-Wal-Mart legislation.
The Journal piece quotes Boston's Mayor, Thomas Menino, as saying,
"They don't pay wages that are sufficient. Their benefit structure is poor. I don't need employers like that in our city."
Interesting that a public official feels comfortable prohibiting citizens from choosing to work for Wal-Mart, or the company for risking its own capital in opening a store in the Boston area. So much for individual liberty in terms of choosing employment options in Boston.
However, a company that has engendered this type of reaction across the country can't be in great shape. Many municipalities seem to be restricting or prohibiting Wal-Mart's entry in order to protect their locally-owned businesses.
As I wrote here, and here, recently, Wal-Mart is already tampering with the branding and positioning strategies which brought it such success over the past two decades.
These cases of governmental hostility to the company's expansion plans would seem to add more challenges to Wal-Mart's already-full plate. According to the Journal's piece, the company's sales growth has slowed below double-digits recently, after decades in the that range. Same-store sales growth is a third of what it was in 1990.
The company is targeting urban areas, finally, for its next growth spurt. But it doesn't look like that's going to be happening.
Which corresponds with what I wrote here last fall. I just don't see the company continuing its past successes in terms of both fundamental growth and consistently superior total returns for its shareholders.
US Corporate Recruiting of MBAs: The WSJ's Survey
Last week's Wall Street Journal survey of corporate recruiters ranked the University of Michigan as the nation's #1 graduate school of business. In fact, the highest rank for one of the traditionally better-known schools was #7, for the University of Pennsylvania's Wharton School.
In a way, I believe it explains some of what we see in corporate America.The recruiters, according to the article accompanying the rankings, value 'communication and interpersonal skills,' 'ability to work within a team,' and 'personal ethics and integrity' all above more task-related dimensions like 'analytical and problem-solving skills,' and 'strategic thinking.'
It conjures up in my mind a group of nice, well-dressed, friendly but unimaginative young MBAs all gathered around a large conference table, 'teamworking' some issue for their new employer.
Perhaps the average returns of US business doesn't get 'better' because so many companies are so pragmatic when it comes to hiring management 'talent.' If they hire MBAs for teamwork and communication, maybe they miss getting problems solved, spotting opportunities for innovative products and services, or making the right strategic moves.
To me, this survey's results firmly indicate that the MBA has finally become a trade degree, along the lines of an electrician's or plumber's license. Not a toolkit for business value creation.
My partner discussed the survey results with his son, and they agreed that, given the choice between attending Michigan or, Penn, Chicago, MIT, etc, they'd both pass on Michigan for one of the other business schools with faculties more associated with the development and publication of new business thinking.
While I am not surprised with the survey's results, I believe it confirms a continuing use of business schools by companies as a rudimentary training ground for mundane business management needs, rather than a source of potential leadership and fresh thinking.
What I would be more interested in, from the survey's results, is which companies recruit more heavily at the more classically-highly-ranked schools, such as Wharton, Harvard, Yale, Sloan, Chicago, etc. Is there a difference in companies' long-term total return performance which is in any way explained or associated with the schools from which they primarily draw their new management hires?
Could we develop a profile of how the customers of some graduate schools of businesses are different than those of others? In a word, segment the customers of these schools?
Have the schools themselves done so, and, if so, what have they found?
Now, that would really interest me. Perhaps the WSJ should do this in the future, to provide some more interesting insights on what the trends in selection criteria imply for company performance over the long term. Summary statistics are nice, but the segment-specific insights would be very revealing.
Friday, September 22, 2006
The More Things Change......
Steve Jobs on Microsoft (Extended Version)
I found this little clip on YouTube the other day, when I was testing the blogging link on that site.
Jobs' accusation of Microsoft's lack of innovative ideas and being cultural philistines doesn't seem to have changed in the years since this interview occurred.
The video clip doesn't have a date, but I'm guessing, by Jobs' look and his references, that it is sometime in the early-mid 1990s.
What I find ironic is that this clip would work today, only for the iPod vs. Microsoft's latest Apple knock-off, the imminent Zune digital music player.
True, Apple stole its Mac OS from Xerox. But what they did with it was inspired and beautiful, if expensive and lacking in troubleshooting capability. Microsoft began its tradition of workmanlike copying of Apple with its Windows OS.
Now, we have the same companies, and the same behaviors, except that this time Apple actually created the digital music download-playing systems itself.
And, of course, this time, the market shares are reversed, and probably will stay that way.
In discussing this with my partner the other day over lunch, I opined that Jobs has already left music playing behind, and is now heading for the higher, virgin ground of digital video content downloading and playing. By the time Microsoft and RealNetworks catch up, Apple will probably have captured the dominant market position, and a proprietary storage method, again.
It's just so eerie that this would all be playing out once more, with the same two companies, and same two leaders, so many years later......
Thursday, September 21, 2006
One Year Anniversary
This month marks my first anniversary writing this blog. Since my first posts, here, beginning on September 15th of 2005, I've written almost 250 pieces.
As I've made this a more routine, daily commentary, my focus has left politics, and focused nearly exclusively on business.
One of the things I've noticed is that writing a daily "column" has sharpened my own sense of the essentials in the business stories on which I comment. It's also helped me to understand how technology has become such a great leveler in recent years. With online publications, cable news, and free online video services such as YouTube, a writer like me is at no disadvantage with respect to news flow, when it comes to selecting topics and having access to information about those topics, on which to opine.
Beyond that, it's also given me many opportunities to test and reinforce my contention, initially born out of my proprietary empirical research, that there are certain hallmarks of companies and sectors that seem to lend themselves to achieving consistently superior returns for their shareholders. Since this is the focus of my companion large-cap equity investment strategy, writing a daily piece for this blog has added a visceral, approachable feel to the rather theoretical notions which originated from my research ten years ago.
If you read this blog regularly, thanks for visiting, and I hope you continue to read and enjoy my work.
The Business of Entertainment Ticket Sales & Reselling
Tuesday's Wall Street Journal featured an article about the business of selling, and reselling, entertainment event tickets. Ticketmaster, a part of Barry Diller's IAC/Interactive Corp., and the market leader, is portrayed as having reversed its long-held position against reselling, and now trying to cut itself in on scalpers' profits. In fact, many states are now reconsidering, or simply not enforcing, their laws against the resale of tickets for more than $1 above the original price.
The key facet of the business which has brought it to this point is described in a quote by Ticketmaster's chairman, Terry Barnes,
"We're in an industry that prices its product worse than anybody else."
The result is frequently either unfilled stadii, or scalpers realizing healthy profits from underpriced tickets. A revealing statistic is that the estimated sales of tickets in the US secondary market was roughly $5B last year, or nearly Ticketmaster's own revenue from ticket sales.
Now, artists whose events are handled by Ticketmaster complain that more of the end user prices of tickets should belong to them, including the extra revenues from online resales, or "scalping," in general.
In the other "corner" of the competitive ring is a smaller, but significant, rival, StubHub, along with eBay's use for ticket resale auctions. Founded in 2000 by two Stanford Business School graduates, the Journal piece reports that StubHub will have $400MM in ticket sales, double that of 2005, on which it makes 25% for its own revenue.
The two major competitors, Ticketmaster and StubHub, view the "market" in radically different terms. The former sees all end-sale ticket revenues as prospectively belonging to the artist and itself, while the latter views all secondary sales as simply between consumers.
It's hard to fault StubHub. Ticketmaster admits its own pricing strategies are so inept as to leave "5% to 10%, that are priced well below their market value," and a further "over 50% of tickets go unsold." Meaning, taken together, that over half of venue tickets are improperly prices, so as to yield sub-maximal, or no, revenues.
Two similar markets come to mind- IPOs and airline seats. Of the two, IPOs have more than simply revenue maximization as an objective. Typically, the offering is meant to create widespread distribution of shares, so that foregone gains on the day of the initial offering, and later, can be somewhat characterized as a "price" paid by the issuing owners, whose equity is up for sale, in order to create a large and liquid market in the shares for the future.
It's possible that musicians and other entertainers, be they sports figures or others, have similar secondary objectives. However, according to Ticketmaster's new position, it seems like this is ebbing in importance. The company began, in 2003, to auction some tickets online, in an attempt at revenue maximization. Apparently, even this hasn't yet resulted in the successful initial sales of prime seats for desired prices.
This would seem to suggest that the artists, and Ticketmaster, should be calling Bob Crandall's old outfit, American Airlines, to consult with it on yield management for entertainment ticket sales.
On a more basic level, however, it seems that artists are trying to have their cake, and eat it, too. In the past, artists have wanted cash up front to fund them, and allegedly do what they do 'for art's sake.' Until, that is, it pays a lot. Then, it seems, they want the full end sales value of the seats for their events, without the risk of that value being less than they might get upfront via the current process.
But if they want the money, shouldn't entertainers take the risk of unsold seats? Cashflow risk? Timing of sales risk?
Why should Ticketmaster and the entertainers they represent get scalper's prices without the risks?
Painters don't get a cut of their painting's eventual high prices, if their canvases ultimately trade for much higher sums among and between collectors.
I think StubHub is correct on this one. Ticketmaster, it points out, brokers deals for artists to play venues. The ticket seller estimates what to charge for tickets, and artists get a cut. However pricing is done, it is their choice.
Would Ticketmaster, the venue, and artists all be OK with a simple online bidding process? Reserving the timing of various tickets for maximum yield? Calling on an airline for help with yield management of the scarce and perishable inventory of event tickets?
On one hand, they may realize better ticket sales by volume and percentage of seats, as well as total revenues. On the other hand, Ticketmaster's stable of entertainers may lose fans, as they are seen as directly involved and complicit in the move to a total auction market for live performance tickets, possibly moving most tickets beyond the price range of many of their fans.
Doesn't it really boil down to the opening quote by Ticketmaster's chairman? The company appears to simply be inept at a key operating function, price setting and yield management, in its major business line, selling tickets to venue seating for its entertainment clients.
Wednesday, September 20, 2006
Conglomerates' Value-Added: Another Perspective
Last week's WSJ article about United Technology's new corporate ad campaign caught my attention.
The topic is an old one, going back at least as far as my own graduate business school education in the late 1970s. In that sense, nothing in the piece was really "new" That is, how does a conglomerate provide a clear presence to the market for itself? And is it even necessary?
However, times have changed since I was a grad student, in that, now, a publicly-held company's long-term success measure is usually its total return.
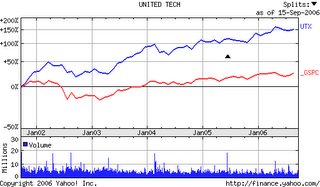 So, the first thing I did, upon reading the piece, was to call up the Yahoo five-year price chart for UTC and the S&P500. That chart is displayed on the left.
It's clear that UTC has nothing to worry about. The company's five-year performance is vastly superior to that of the index, and has had no significant downturns which lasted more than a few months.
Why waste money on corporate advertising, when the investors are getting such stupendous returns? Exactly who needs to know about UTC, the conglomerate, when the constituent businesses are delivering such surprisingly consistently superior performance?
It would seem that being a conglomerate is not, in this case, hurting UTC at all.
What is George David's, UTC CEO's, purpose in this matter? How will spending the planned $20 million affect the company's performance?
If UTC had stellar financial operating performance, but poor total returns, it might be different. But that's not the case.
And citing GE as an example of what it wants to emulate seems misguided, too. GE's returns have been abysmal under its CEO, Jeff Immelt, for five years.
Perhaps George David should save the $20MM for product development, and continue to improve his chances of continuing the difficult task of earning consistently superior total returns for his shareholders.
The topic is an old one, going back at least as far as my own graduate business school education in the late 1970s. In that sense, nothing in the piece was really "new" That is, how does a conglomerate provide a clear presence to the market for itself? And is it even necessary?
However, times have changed since I was a grad student, in that, now, a publicly-held company's long-term success measure is usually its total return.
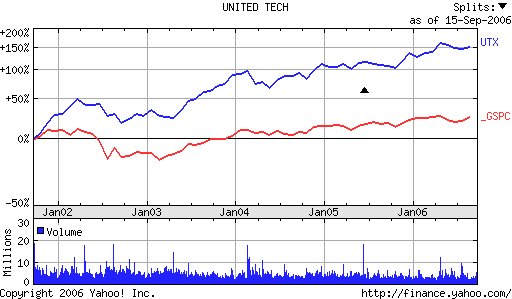 So, the first thing I did, upon reading the piece, was to call up the Yahoo five-year price chart for UTC and the S&P500. That chart is displayed on the left.
It's clear that UTC has nothing to worry about. The company's five-year performance is vastly superior to that of the index, and has had no significant downturns which lasted more than a few months.
Why waste money on corporate advertising, when the investors are getting such stupendous returns? Exactly who needs to know about UTC, the conglomerate, when the constituent businesses are delivering such surprisingly consistently superior performance?
It would seem that being a conglomerate is not, in this case, hurting UTC at all.
What is George David's, UTC CEO's, purpose in this matter? How will spending the planned $20 million affect the company's performance?
If UTC had stellar financial operating performance, but poor total returns, it might be different. But that's not the case.
And citing GE as an example of what it wants to emulate seems misguided, too. GE's returns have been abysmal under its CEO, Jeff Immelt, for five years.
Perhaps George David should save the $20MM for product development, and continue to improve his chances of continuing the difficult task of earning consistently superior total returns for his shareholders.
Tuesday, September 19, 2006
Rhapsody, iTunes, Zune and The Evolving Competitive Market for Digital Media Downloads
It seems that there is now a concerted effort by both RealNetworks and Microsoft to enter the integrated digital music device and download service market.
According to Monday's Wall Street Journal article, both companies are eyeing Apple's 75% share of a market which accounted for $1.5B in revenues for the company in just the last quarter. The firm has, according to the WSJ, sold 60 million iPods since the product line's introduction.
That must be nearly, on average, one per household in the US. Not that all sales are in the US, but as a benchmark, it's a huge installed base penetration for the device and its companion download service.
There's a really good quote in the article by Mike McGuire, an analyst with the Gartner Group,
"You've got to come to the party with something pretty special."
RealNetworks' Rhapsody service is more or less a musical rental business model. One pays a monthly subscription to keep downloaded material activated. Rhapsody will now work with SanDisk's Sansa player, the leading rival company to Apple in this market.
Microsoft is now approaching the product/market in the same manner as it did the XBox360, and with the same senior executives responsible for this new digital music/media business group. Rather than rely on outside developers, they are now mirroring Apple's total system provision of a player, the Zune, and its own net-based downloading service.
Apple has had this market largely to itself for at least five years. It's prices are very low now. Even more than a year ago, they had penetrated the lower end of the market with a $100, 512KB Shuffle. I can't see anyone undercutting them on price.
So it's difficult to see just what is left in the marketplace for Microsoft and RealNetworks to serve with significantly superior or different, value-adding functions and features.
In Microsoft's case, I'd even go so far as to suggest that this may mark their second major step toward dis-integrating the monolith that has been the Redmond software titan. As I opined to my consulting friend, S, some months ago, I think that way lies any hope of rescue and financial success for Microsoft.
From what I've read, there is no mention of the Xbox or Zune being integrated into or with other Microsoft products, notably Windows. But I don't know if wireless transfers of music is enough to dethrone Apple after a five-year headstart.
It will likely come down to a preference for the online interface experience. Or perhaps upgrading and replacing an older player with the same brand, in order to keep one's music library intact. Funny how well-designed products just naturally promote legal and profitable tying.
In the final analysis, based on what I've read so far, Apple doesn't have much to worry about in the near term. They've made their platform into a multi-media one, from simply music, in order to facilitate future growth. And adeptly sidestep competition from pure music players.
If this is the best RealNetworks and Microsoft can do, they may be in for a bad time in the digital media device and download product/market.
Monday, September 18, 2006
Energy Prices, Investors and the Economy and Markets
This has been a rather peculiar year for equity investing. Last week's Wall Street Journal, on Wednesday, featured two articles on disappointing investment performance at two very well-regarded firms- Goldman Sachs and Convexity Capital.
Our own equity strategy is doing poorly at the moment, as a result of energy prices, and investors' near term reactions to those prices.
My partner emailed me a recent NY Times piece which repeated many of the comments I've made regarding this situation. It is, to me, perplexing.
First, it's notable that so many hedge funds and veteran managers are doing poorly as well this year. It's not really a "growth" economy, so far as investors perceive it. The S&P500 Index has not had a monthly closing annual return above 6% yet this year. Many have been below 4%. Hardly a year of confident investing in a growing economy.
Which brings us to energy. The track record of energy firms which have entered our portfolio is one of consistently superior revenue growth and total returns for quite a few years. They are not simply timing bets on oil and gas prices. However, this year, more than even last year, has really caused confusion in the energy markets.
If economies are growing, then investors fear the Fed raising rates to check inflationary pressures. Pressures brought on by......energy prices! Rising rates will slow the economy. And lead to less energy usage.
If economies are slowing, investors feel energy will be in less demand, and, thus, have less value. As will, they feel, the companies producing and distributing the necessary fuels and their precursors.
It would seem that, for now, and for much of the past few months, the broad middle swathe of "average" investors, and I use the term pejoratively, feel that it is an inescapable conclusion that any probably economic outcome must lead to lower growth and lower energy prices, and, thus, lower prices for energy company equities.
To be sure, the way the S&P has bumped along near zero returns for so much of this year, and in the low single-digits the rest of the time, doesn't help. Nevermind that real economic growth has been pretty good for more than two years now. And that, per Arthur Laffer's comments recently, related in this post, we aren't seeing inflationary pressures, so much as the effects of commodity prices filtered through exchange rates.
I just don't see an economic recession among the various better pundits who forecast such things. ChIndia still seems to be growing and planning to consume copious amounts of energy. No imminent additions to supply are in sight, and demand doesn't seem to have materially slowed. True, current inventories are high for oil, gasoline and natural gas. Is this a long-term effect, or simply a snapshot in the early fall? Is it truly the basis for long-term declines in energy prices?
Granted, Chevron and Devon have announced a large new find in the deep waters of the Gulf of Mexico. As the NYTimes article my partner sent me, written by Daniel Akst reminds us,
"WhatÂ’s that you say? You think this sounds like good news rather than bad? You figure cheaper oil would boost economic growth while slashing the income of such lovable oil exporters as Iran?
Don’t kid yourself. Anything that reinforces the role of fossil fuels — particularly oil — as the industrial world’s primary energy source is bad, not good. Anything that prolongs the life of the internal combustion engine is a negative, not a positive. Anything that makes it cheaper to pump greenhouse gases into the atmosphere is cause for mourning rather than celebration.What we need is not lower oil prices but higher ones — significantly higher, enough to deter consumption and make us look seriously at alternatives........HIGHER prices have worked wonders before. Today, Americans can generate a dollar of gross domestic product using just half the energy required in 1973, that watershed year of the oil embargo and lines at gas stations. In countries where energy is more expensive, a dollar of G.D.P. requires considerably less energy still. Unlike a tax, moreover, higher prices have the advantage of applying all over the world, to everyone."
The point about the growth in US productivity with respect to oil is a fact I like to quote. However, the correspoinformationmation about countries where energy is even more expensive was welcome news to me.
It's a tumultuous time in the equity markets, and the energy markets, to be sure. Occurring at such relatively modest market returns, with questions about inflation, growth and recession in the air, all of this has a depressing effect on growth equity strategies.
I'm not completely sold on the idea that energy prices are down for the count, and their equity prices, with them. For a while, I do believe the weight of average market participants will continue to keep prices low. But it won't take much to send both commodity prices, and those of their producers, rocketing upwards again, once the broad, "average" investors, meinstitutionaltional managers, realize that supply and demand fundamentals of energy have not changed materially in the last twelve months.
Thursday, September 14, 2006
More Bad News At Ford
Poor Alan Mulally, Ford's new CEO. When it rains, it pours.
I've written here, and here, recently, of Ford's rather interesting, if perilous, changes.
From article in The Wall Street Journal this morning, it appears that Ford is making a combination of the worst choices among its various options on several fronts.
The company is looking to buyout out as much as 30% of its workforce, but is not announcing the termination or sale of any of its auto brands. Further, and one of the reasons for the sudden move to shed employees, is Ford's new forecast that profitability will not be in sight until after 2008, rather than during that year. It turns out, as I wondered last year, in this October post, that Ford is running out of time and money.
Throughout all of this information, I am reminded of Holman Jenkins' stressing how much is already going on at Ford, in an almost unstoppable manner, as Mulally arrives. The plant closings, buyouts, layoffs, and cost-cutting have been either underway or are now culminating in agreements with the UAW.
Then, this week, several senior executive departures were announced. Anne Stevens, a senior North American manager involved in the company's turnaround plans, has left. A few other managers are retiring. To Jenkins' point, were Mulally bringing in his own team, this might be opportune. Instead, he'll be attempting to sail the Titanic short-handed.
When I consider the two articles I cited recently offering free advice to Ford, and the actions announced today, the company's future does, indeed, seem a bit dimmer suddenly. Expensive, cash-consuming labor buyouts on one hand, and the retention of bloated brands, product lines and business units on the other, portray a company still in denial. Perhaps, as Jenkins suggested, a family still in denial.
Based upon today's events, it would seem that Ford, should it survive the next few years, will be a much smaller car company, if it manages to remain independent.
Apple Announces the Missing Link
Yesterday, Apple announced its iTV device to stream content to the Apple computer-like box, essentially a video-application digital file storage and management device, wired to a TV's video and audio inputs. As expected, and described in the Wall Street Journal, it will use a home wireless network to receive files from a Mac or PC. It even has a wireless controller, as I expected (ok, who wouldn't, at this point, right?).
Finally, the end game is now in sight for network television, and physical film distribution. This device, and its competitors from various other electronics purveyors, will finally allow consumers to shop for video content online, and download it in custom fashion to their home digital storage devices for play/temporary usage/ownership.
I've opined on this development over the past few months in prior posts like this one from February. It spells the final draining of value from the network television model, not to mention Blockbuster, and probably even Netflix. It's even possible this could be the next "killer app" in the consumer digital device world which forces massive upgrading of what one still calls "personal computers."
In any event, by June of 2007, the instrument of broadcast and physical video content distribution will be tangibly at hand, for about $300 (again, more or less my expectation of the price point). So, give things a year or so to shake out, and basic models of competitive units should sell for about $250-300.
As I wrote late last month, here, the less obvious victims of this innocuous little digital box will, I predict, be Verizon, AT&T, and the cable companies. With this final wireless link to what amounts to a digital video server wired to your TV, who needs Comcast's predetermined menu of channels and air times? Just start paying for the content you want, either from a "general store" like iTunes, or Amazon, or, go directly to URLs of the content producers and use your credit card or PayPal.
I am, in any case, quite excited at this new development. Even now, as I finish composing this, I am listening to CNBC's review of the new Microsoft iPod competitor, a type of video/audio file viewing/listening device that wirelessly shares with other users.
The race to market a wide variety of wireless multi-media devices is full on now. The winners and losers will probably include many accidents along the way- unintended casualties, and lucky successes. I'm looking forward to the competition, but I expect that, in the end, this will benefit unbundled, superior producers in every area of the new markets- content, device design, and selective disintermediation of content management.
"Free Advice for Ford"
Tuesday's and Wednesday's editions of the Wall Street Journal featured incredibly good pieces about Ford.
The first piece, written by Charlie Hughes (former CEO of Land Rover) and William Jeanes (former editor in chief of Car and Driver), succinctly pares suggestions for Ford's new CEO, Alan Mulally, down to three.
First, they recommend that Mulally's main objective be to make "the Ford brand the most successful brand in the world." Toyota, they believe, is Mulally's "new Airbus." A simple, compelling objective on which to focus the beleaguered firm.
Next, they advocate combining, divesting and eliminating the company's car brands to leave just the three remaining, and then put the full force of the company's efforts behind those brands. The brands they recommend retaining are Ford, Volvo and Jaguar. There is a sense to this, because those three, together, cover a maximal spectrum of customer segments, while being few enough in number to allow each brand to have similar products, but without any real chance of product/market overlap.
Finally, they suggest that Mulally has to create a new culture at Ford, to have any chance of success. They posit, reasonably, that a combination of years of careerist management, with a recent drumbeat of failure, has left the company bereft of much chance of success in its current condition.
I found their article elegantly reasonable, powerful and simple in its messages. Of course, much quantitative work will be required, whatever direction the new CEO takes, in order to have any hope of turning Ford around. But Hughes and Jeanes articulate a nice combination of suggestions which touch on problems involving customer confusion with overlapping and/or unprofitable brands, the company's own cultural malaise, and an objective which is, they write, "noble."
Yesterday, on the heels of that editorial, came Holman Jenkins' very different approach to offering welcoming advice to Alan Mulally. I like it equally well.
Holman focuses on Mulally's isolation at his new employer. Not only does Mulally have no troops with him from Boeing, obviating his ability to dismiss unwanted existing staff, but the "old king" still reigns. Not an enviable position.
Then Holman goes off on a truly inspired track. To those who doubt the viability of a private equity buyout at Ford, he notes that one was just done in the semiconductor sector of similar size. The difference, he notes, is the Ford family's intransigence at acknowledging reality. So long as the Fords insist on control, nobody else will use fresh money to bail them out. A condition for their rescue is to surrender control. After all, who got Ford into this mess in the first place?
The overall impression one gets from Mr. Jenkins' piece, especially its discussion of Ford's labor woes, and Mulally's background, is that Ford's new CEO may have his biggest impact not on the firm's strategy, or operations, but on the structure of the firm going forward. Perhaps privately owned, perhaps with significantly different labor dynamics.
Taken together, I find both pieces extremely candid and reasonable regarding Ford's, and Mulally's, options in the near term. Neither necessarily thinks Ford will survive, or independently and publicly. But they highlight some very valid concerns for the ailing auto maker's new CEO.
Wednesday, September 13, 2006
The Boomer Generation's New Behavior Patterns with Aging
Autonation's CEO, Mike Jackson, guest hosted part of CNBC's Squawkbox this morning. For a car salesman, as he described himself, he's a very interesting guy.
He talked at some length about the new patterns of aging spending seen in boomers. That is to say, the Americans now aging into their sixties, near retirement, are spending quite differently than did previous generations of Americans upon approaching retirement.
Essentially, he said that research with which he is familiar shows that this near-retirement generation is working at full throttle later into life, and spending like that as well. They are not slowing down.
He enumerated some examples, mostly of activity-oriented and self-indulgent purchases, such as cars, homes, electronics, etc. The point he drove home is that the impact of these very different spending patterns is causing a number of business-related disciplines to reconsider their assumptions about economic activity for the years ahead.
For instance, he noted the effect this different aged-person behavior would have on product development, calling for different feature mixes than were previously supposed for those advancing into their sixties. Additionally, their increased discretionary, luxury- and comfort-oriented spending should probably lead to changes in economists' assumptions regarding the impact of this generation on various aspects of the economy, including sector stimuli, savings rates, etc.
All in all, a rather thought-provoking appearance from Mr. Jackson. One which reminded me, per my marketing background and training, that fresh data is worth so much, in order to avoid incorrectly extrapolating trends that are no longer valid.
Tuesday, September 12, 2006
Perspective on Banking: Commodity or Not?
My long-time friend and some-time business partner, Bob, recently sent me a three-part series on the banking industry which appeared in the American Banker recently.
Contained in the third installment of the series was this passage,
"....Brand matters to bankers, even though many observers see banking as a commodity business.
"It's not like we are selling steel; there is a real customer interaction that occurs, both in the branch, on the Internet, over the phone," said Sallie Krawcheck, the chief financial officer of Citigroup Inc. "When you interact with the customer as often as a bank does on an issue that is as important as money, I don't think it is a commodity at all. There is real brand equity in the client experience of these financial services companies." "
I must say that I beg to differ. While branding may matter to bankers, it has historically rarely mattered to customers. Money may be important, but, then, so is oil or copper.
They are commodities, despite their occasional high prices and short supply. Money is no different.
 Despite what Krawcheck would like to believe, money is a commodity, and so is credit. If it weren't, we wouldn't have interest rate competition among lenders during periods of healthy growth and credit demand. In fact, her company, Citigroup, is a prime example of how credit and financial services businesses are not well-branded.
Consider the chart on the left, from Yahoo, displaying Citigroup's stock price relative to the S&P500, for the past five years.
Doesn't look much like a branded goods purveyor with healthy growth and good margins, does it? Unless, of course, it only meets market expectations. However, I'd suggest that whatever Citi has been doing, isn't working.
And that probably includes Krawcheck's insistence that the company's basic product, money and forms thereof, is not a commodity. The whole point of money, credit, and tradeable financial products is to be commodities.
Most consumers resent having to pay and ask a bank for access to their own money. Credit is the one product they go begging for. But even there, in this era of oversupply of credit sources, consumers are more judicious, and less desperate, than they had to be in decades past.
No, I don't think financial services has done very well trying to make credit and money a branded, provider-unique product or service.
Contained in the third installment of the series was this passage,
"....Brand matters to bankers, even though many observers see banking as a commodity business.
"It's not like we are selling steel; there is a real customer interaction that occurs, both in the branch, on the Internet, over the phone," said Sallie Krawcheck, the chief financial officer of Citigroup Inc. "When you interact with the customer as often as a bank does on an issue that is as important as money, I don't think it is a commodity at all. There is real brand equity in the client experience of these financial services companies." "
I must say that I beg to differ. While branding may matter to bankers, it has historically rarely mattered to customers. Money may be important, but, then, so is oil or copper.
They are commodities, despite their occasional high prices and short supply. Money is no different.
 Despite what Krawcheck would like to believe, money is a commodity, and so is credit. If it weren't, we wouldn't have interest rate competition among lenders during periods of healthy growth and credit demand. In fact, her company, Citigroup, is a prime example of how credit and financial services businesses are not well-branded.
Consider the chart on the left, from Yahoo, displaying Citigroup's stock price relative to the S&P500, for the past five years.
Doesn't look much like a branded goods purveyor with healthy growth and good margins, does it? Unless, of course, it only meets market expectations. However, I'd suggest that whatever Citi has been doing, isn't working.
And that probably includes Krawcheck's insistence that the company's basic product, money and forms thereof, is not a commodity. The whole point of money, credit, and tradeable financial products is to be commodities.
Most consumers resent having to pay and ask a bank for access to their own money. Credit is the one product they go begging for. But even there, in this era of oversupply of credit sources, consumers are more judicious, and less desperate, than they had to be in decades past.
No, I don't think financial services has done very well trying to make credit and money a branded, provider-unique product or service.
Monday, September 11, 2006
Intel's Restructuring
Intel's long-awaited restructuring was announced last week. Wednesday's Wall Street Journal featured an article detailing the company's plans. The market has been in suspense since this spring, when Intel's CEO, Paul Otellini, admitted the company was thoroughly reviewing all of its operations. I wrote about that in a post here.
My initial observations are largely sustained by the Intel restructuring plan details. They are cutting 10% of their workforce, mostly middle management. The company's senior management actually admits that they have become bloated and slower at decision-making in the middle ranks. This fits with my overall suspicion that Intel has become a victim of "sand in the gears," the term I use for what happens to a company experiencing successful growth for too long. Mediocre employees and bloated processes combine to begin to gradually silt up the company's ability to recognize and quickly react to changing environmental and/or competitive circumstances.
In this case, the combination of AMD's technological challenge to Intel, and the lowering of desktop and laptop PC systems which constitute so much of the end-user demand for the company's signature microprocessors.
Otellini is quoted as saying, "These actions, while difficult, are essential to Intel becoming a more agile and efficient company, not just for this year or the next, but for years to come." Probably true, but, unfortunately, as my old boss and mentor, Gerry Weiss, SVP of Chase Manhattan Bank's Planning and Corporate Development function would, and did say, 'When a company has to "restructure," that generally means it has failed to adapt to changing conditions in a timely manner. It is an indicator of management failure.'
The company is disposing of various smaller new business units connected with communications equipment, as well as focusing on trimming marketing personnel. This is puzzling to me, as I would have thought that product design was the problem, not marketing.
Typically, cutting resources at a company does not foster growth. While Otellini's restructuring program may, in fact, produce near-term profits, it is not at all clear that the results of the program will re-ignite Intel's ability to create superior value-added for its customers at profitable prices. And, thus, consistently superior total returns for its shareholders over the longer term.
Saturday, September 09, 2006
More on Wal-Mart's Store Strategy Changes
As I mentioned in my previous post, Wal-Mart is overhauling its single-store format, in favor of six ethnic-income segmented styles of stores.
At the same time, the head of US store operations, Eduardo Castro-Wright, is relocating regional executives to their regions, from Bentonville. This, by itself, is not such a big deal, one would think.
However, read the comment in the WSJ article from Todd Libbra, responsible for 132 stores in Illinois,
"By reading the newspapers, watching the TV stations and being part of the community, I have a better flavor for what's going on."
In Chicago, perhaps. I happen to be from Illinois- downstate Illinois. He isn't getting a clue as to what is happening outside of the Cook County environs while he's nestled up there near the Windy City.
And, by the way, Todd, ever hear of newspapers online? A little thing you can get via something called the "internet?" I'm sure Todd could have been subscribing to numerous Illinois city and town newspapers via the internet, or his staff could have covered this base. Is this manager a good example of the caliber of executive at, and general awareness level of the world outside, Wal-Mart? exec and getting the tribune
Regarding the ethnic basis of segmentation, lots of companies cater to ethnic tastes, but none that I know of trumpet this as a segmentation lever. What are these guys thinking? Didn't they have even racial trouble last year and this already?
Perhaps the largely white senior executives in Bentonville, starting with CEO Lee Scott, think that by having a Mexican chief of US stores they will deflect further charges of racism. Instead, I wonder if they risk having a truly primitive segmentation strategy, imported from a less-sophisticated consumer society ,Mexico, derail their firm.
And what about the 'other' ethnic groups? Is this an opportunity for Target to welcome them with open arms?
My guess is that a really good segmentation strategy focused on differentiating store types would have resulted in something like three types of stores: rural, ex-urban middle class, and ex-urban on the fringes of upper class locales. Assortments of goods could easily be changed more granularly than merely with store type.
As it is, I wonder if Wal-Mart's historically in-bred management isn't totally fumbling its new segmentation and store-type strategy. They have been successful and well-regarded for doing one thing well throughout America and much of the world- leveraging tremendous purchasing power to offer large assortments of goods to mostly, though not exclusively, lower-income individuals, at very low prices. And, apparently, they have had some success attracting upper-income individuals to the stores to buy basic, low-priced goods for which the source of the product is unimportant.
I just don't see their new move into this complicated, multi-store approach taking full advantage of Wal-Mart's historic strength in low-cost sourcing of supply, while it seems to put them squarely opposite some more savvy retailing competitors in what is, for Wal-Mart, an entirely new product/market space.
Subscribe to:
Posts (Atom)


