Monday, July 31, 2006

Proctor & Gamble: Poised for Sustained Growth?

I mentioned in a recent post that I read an interview with James Stengel, chief marketing officer of Proctor & Gamble. His focus on customer problems, lifestyles, and how P&G can improve their customers' lives was quite impressive.

In discussing this with my business partner, I mused about whether P&G may be, for the first time, heading toward inclusion in our equity portfolio of consistently superior companies. After all, with a clear-headed, viable focus on consumers, and customer needs, one might think that the firm is within reach of becoming a really well-led, well-managed creator of shareholder returns, based upon solid business concepts and executions leading to consistently superior revenue growth.
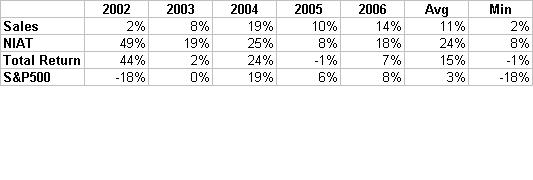
To get a better understanding of this, I did some analysis of the company's recent sales, NIAT, and total returns. They are presented in the table at left, on which you may click to enlarge.

The first thing I notice is that P&G's sales accelerated in 2004 and this year. A friend who works at the firm, locally, confirmed that these are the effects of the last two major acquisitions. The latter one being Gillette, last year.

This has an interesting effect on P&G, called "riding the tiger." Notice that its sales growth rates, pre-acquisitions, were in the single digits, on the low side, on average. In the years prior to 2002, they were also rather meager. Thus, P&G has bought growth, twice. The year in between the acquisitions displays a 10% sales growth- higher than the earlier years, but still not so high as with the immediate folding-in of the purchased sales bases.

My proprietary research shows that the market tends to favor companies which can consistently generate superior revenue growth. P&G has begun to buy its growth. Either of two things need to occur, if the company is to have a good chance of becoming a consistently superior total return-generating company.

Either it needs to generate organic growth to match that of the effects of the acquisitions, or it needs to be able to continue its acquisition program, making it a sort of 'standard operating procedure," for which investors are prepared to pay. The company is hitting some pretty high revenue growth targets for a consumer goods conglomerate. While the 10% revenue growth in 2005 was good, and better than the long-term S&P average, it was by no means near the upper end of the distribution of revenue growth in the S&P500.

NIAT growth at P&G has also been getting better, but the best years were in the earlier years of this period.


Taken together, the revenue and NIAT growth pictures lead to the total return performance shown in the table. P&G has a much better average than the S&P for the last five years. However, the last two years have been a close call. Most of the 12 point spread in average total return between the S&P and P&G is accounted for by 2002. I would guess that would have been from a "flight to quality" by investors, as the tech-bubble-bursting recession drove investors to safer havens. Too, the low returns in 2004 and 2006 could be the result of investor verdicts on the prices of each of the two major acquisitions in the the prior two years.

I like P&G's customer focus. I understand the broadening of their product and business portfolios recently. However, from the data above, I seriously wonder if they can sustain raw revenue growth in the next few years. This is where consistency of revenue growth at fairly high rates really challenges a company. If too much of the firm's recent success on this dimension was simply purchasing growth, then I think total returns will ebb, along with organic growth.

It will be very interesting to watch P&G in the next few years to see how their fundamental operating capabilities prove out, and whether the market rewards the firm, if they do.

Sunday, July 30, 2006

America's Largest Banks: It's About More Than Size

This week's Wall Street Journal featured an article, on Friday, announcing that Bank of America (really the renamed NCNB of old) is about to become a larger bank, by market value, than Citigroup.

If this doesn't highlight the wrong measure, I don't know what does? Ranking the banks by deposits?

As it happens, BofA has been superior by a truly important measure for some time now. As the table above shows (click on it for a larger view), over the last five years, it's total return to shareholders has averaged 14.4%, while Sandy Weill/Chuck Prince's Citigroup has lost shareholders 3.9%, on average. During the same period, the S&P500 has gained 3.2% per year, on average. Further, BofA outperformed Citi for 3 of the 5 12-month periods, and nearly tied it in a fourth (2004).

Tying in with the Friday article, and another one earlier in the week, about Prince's vow to grow "operating leverage" are the upper rows of the table above. It clearly shows that Citi's revenue growth has been anemic for the past five years. Once again, except for 2002, BofA outgrew Citi in terms of revenues. Both have been accelerating since the bottom of the recent recession in 2002. Citi may be improving, but, again, BofA has done even better.

Granted, BofA is not yet sufficiently superior to make it into my portfolio selections. But at this rate, it'll be there years before Citi.

Size has nothing to do with the comparison of these two financial giants. Ken Lewis has been doing something a lot better than Chuck Prince and, or course, his predecessor, Sandy Weill. And the consistently better total returns prove it.

Friday, July 28, 2006

AMD in The News Again

This week, AMD moved to buy ATI Technologies, which manufactures chips for PC graphics, plus other accessories which may be integrated into chip sets.

On the plus side, the move helps AMD position itself as unique, vis a vis Intel, because the latter will not have a captive graphics chip maker. On the negative side, analysts are wondering if AMD can successfully handle its burgeoning price war with Intel, while integrating ATI and investing in both itself and its acquisition, to realize the long-term benefits of the combination.

What I find heartening about AMD's move is that the management evidently understands that it must "ride the tiger." Having made the moves to take on Intel and surpass it in growth, it now is planning to cement that lead.

Will it work? Who knows? This is where consistently superior prior performance makes a difference, and right now, AMD does not seem to be there just yet. Its stock price performance has been uneven, versus the S&P, over the past five years. Only recently has it turned upward, outperforming the index. In the last five years, only two look to have seen AMD outperform.

Thus, its track record of surprising the market with results is not yet well-established.

I think, fundamentally, the ATI move is probably a good one. Not that this means I think it will work. I just think that, as I understand their situation, they needed to do something like the ATI acquisition to keep the pressure on Intel, and place their bets for future positioning.

It should be an exciting next few years, watching to see if AMD can decisively outgrow Intel, as well as earn consistently superior total returns while doing it.

Wednesday, July 26, 2006

Marketing & The Internet: The More Things Change.....

Despite what you might think about marketing management in the era of the internet, we don't appear to know much more about consumer behavior now than we did prior to this new era.

The Wall Street Journal has featured several pieces this month concerning marketing on the internet. Early in the month, they published a "special" report about it. Then Lee Gomes wrote a review of the internet-focused hot seller, "The Long Tail," by Chris Anderson, this week.

What struck me most about the WSJ special report was that it was so anecdotal. The piece featured stories of various retailers' and marketers' attempts to, and experiences with, internet advertising and/or promotion. From what I gathered, the time honored marketing dictum, attributed originally, I believe, to John Wannamaker, is still true,

"I know I'm wasting half of my advertising spending, but I don't know which half."

At the end of the report, the Journal printed an interview with Proctor & Gamble chief marketing officer, James Stengel.

I have to say, he seems, from his comments, like a very bright guy. His basic instinct is pure marketing- to use his company, and its products, to get into the very fabric of helping his customers live better lives. He seems similarly at sea about the internet, as the rest of the interviewees in the report were. But at least Stengel is clear about where he's going with any internet initiatives.

On the age-old split between lifestyle marketing, and benefit-bundle marketing, Stengel comes down on the side of the latter. That is, he focuses on what products can do for the customer, and how internet search and advertising can help a customer realize those benefits.

This stands in sharp contrast to efforts, most notably by product placements, to sell merchandise based upon a lifestyle with which they are prominently associated.

Given Stengel's focus, one might think that Anderson's new book, "The Long Tail," would be all about how the internet lets every niche product become a star. And that is what the author claims.

However, as Lee Gomes, the WSJ columnist discovers, the basic premise of the book is fraudulent. Anderson coins a new term, apparently prominent on the book's dust jacket, "The 98 Percent Rule." Basically, Anderson alleges that with the arrival of the internet, niche products get respect, and sales volume. Thus, the sainted "80/20" rule is dead, and the "98 Percent Rule" takes its place.

Except that Gomes debunks this myth. It turns out that all Anderson observed was the early days of hit-driven product websites, where consumers bought, downloaded, etc, nearly all the titles offered. As more product came into the inventories of companies like Netflix, Amazon, Ecast, and iTunes.

So, even before this new best-seller is a year old, its central message is found to be the flawed the conclusion of hasty and badly-done "research."

Oh, well. Maybe next year someone will decode internet buying behavior. For now, though, the usual suspects plod on. Advertisers can't quite measure consumer behavior, marketing managers throw tons of money at online promotion, in hopes that something will stick. And the poor, dull business of actually observing and reflecting on how a product will affect a customer's life continues to get little respect.

Except at P&G, about which I will write more imminently.

Tuesday, July 25, 2006

"Support" Your Local Retailer?: The Unseen Effects of Big Box Stores

Today is my father's 79th birthday. In honor of him, I would like to recount a story which is, to my way of thinking, his kind of humor. I can easily see him relating this story over dinner with our family when I was younger- much younger.

The tale begins with my athletic pursuits. I play a racquet sport. So I wear athletic supporters. Depending on how often you play, and how many you have, they last for varying amounts of time. I play a lot. Even with 6-7 supporters, the constant washing and drying eventually leaves them limp, the elastic overheated and stretched.

In the past, I would go to a local sporting goods store near my racquet club to buy more. The last time I did so, perhaps 5 years ago, they had a decent selection of styles and sizes. When I returned last month to buy several supporters, I was told they had none. Zero. Zippo.

"It's baseball season. We don't have any! Come back later and maybe we'll have some."

Okay. So I returned this week. They had one. One supporter in my size, although not the style I prefer. Upon asking them to order more, I was told,

"We only have one. We may not carry them anymore. Nobody comes in to buy them anymore."

I opined to the owner, apparently the son of the esteemed founder, that maybe he had it backwards. Maybe nobody came to buy supporters from him, because he had no inventory. His blank look told me I was wasting my time. But, for good measure, I uttered a prophetic,

"It's ok. Whatever you want. If you want to send me to Sports Authority, I'll go there."

Next, I visited my local sporting goods retailer, down the street from my home. Bob T's shop is the sort you remember from your childhood. Bob is a kindly, terrific guy. Like an old shoe. Perfect for the business of local sporting goods sales. He takes used ice skates on consignment. He provides the local high school uniforms, and various staples for children's and youth sports. I like to give him business when I can. So when a friend reminded me of Bob T's place, I went there the very next day. In search of supporters.

"No, sorry. We don't have any. Come back in a few weeks. We are backordered. Everything we have has cups."

When I remarked that I wanted to give them a chance, before going to Sports Authority, the woman at the counter smiled and simply repeated the facts of their inventory problem, how they'd be closed for a week, etc. Apparently, no worries over sending me to Sports Authority, either.

So, now, I've tried two friendly, local, family-owned sporting goods stores. Neither has an inventory of the rather basic piece of athletic clothing, a man's athletic supporter. Mind you, I live on the east coast of the US. Not Tibet, nor Nigeria, nor Croatia. I would have thought this search would be easier.

Today, I ran some errands. On my list was to visit another local shop. This one is a swim shop located about five miles from me. If Speedo makes it, they carry it. But before then, I found myself up on a local state highway, amidst the big box stores. So after concluding my business at ToysRUs, I decided to head for.......

Sports Authority!

As I was musing about driving to the swim shop, it occurred to me that there is a bit of a mystery in this story. Where are the nation's athletic supporters? Who has taken them, and why?

Surely, our nation's, nay, the world's athletic supporter manufacturer's and distributors cannot be leaving men "hanging out," or, well, you know what I mean.....

I formed a hypothesis on my short drive up Route 10 to Sports Authority. Perhaps SA has monopolized the provision of athletic supporters. If they had none, then, truly, there was a mystery. But if Sports Authority had supporters, that would suggest that vendors now found it difficult to bother with smaller retailers, when SA probably accounted for so much more volume.


I entered the huge store, got directions, and walked to the display of men's athletic supporters.

WOW! Mecca! The missing athletic supporters.....they were all there...at Sports Authority! All along!

They had it all. They had brands I hadn't seen in years. In all sizes and styles. Styles I was told at the small shops could not be had anymore. Bike, for one. And for the most popular style, SA sells them 2-for-1, at about half the price of the off-brand Martin supporter I bought at the first local sporting goods shop.

Now I see what has occurred with the entry of Sports Authority into my local market. I would guess it's similar for many other big box retailers in their respective product spaces. SA seems to have become a giant sponge for inventory of basic sporting goods. Your local sporting goods shop can't even get inventory on basic goods anymore. The manufacturers and distributors probably cannot afford to short Sports Authority, so they simply don't respond to requests from the small retailers.

I think that most manufacturers and distributors direct their product and inventory flow to SA not just for the volume, but for the relative lack of volatility of their demand.

Think about it. Sports Authority must be the size of about 10 local sporting goods shops. They concentrate the volume of all sorts of equipment, and by virtue of accounting for it in one store, reduce order volatility immensely. That has to be valuable for the vendors and distributors. By being so large, SA draws a huge flow of local shoppers. Their prices and assortments of basic goods are better than the local shops, so the circle becomes virtuous for SA.

The result, I believe, is that distributors don't even bother filling orders for a lot of basics in the small quantities that local sporting goods shops order. Where's the benefit? The volume must be microscopic, next to that of Sports Authority. The cost of sending small lots, and handling the varying order sizes and frequency, can't be profitable, relative to handling a constant flow of product for Sports Authority.

So, there you have it. Athletic supporters galore! They were always "there." Just not in the usual places I had learned to look. In only about five years, Sports Authority's one store in my area has altered the entire complexion of buying basic sports clothing. They so dominate the market that you literally cannot find an athletic supporter anywhere else within 10 miles of their store.

So I don't live in Croatia after all. I just have come to the realization of what big box retailing does to even those small retailers who find niches that allow them to hang on in the face of outfits like Sports Authority. The supply of basic goods dries up for the small guys. They don't even get deliveries of products like athletic supporters anymore.

Welcome to the new world of retailing.

Monday, July 24, 2006

On The Recent Decline in Equity Markets

Last week's .3% return for the S&P 500 index was the first positive weekly return in the last four. However, the total return for the week is somewhat misleading, as the index plunged roughly 1.6% over the last two days of the week.

The usual culprits were implicated: worries over current interest rates; concerns over energy prices causing economic growth to abate; some unexpectedly weak corporate earnings reports, and; continuing violence in the Mideast, leading investors to worry that energy supplies will be affected, thus affecting prices, and, again, economic growth, possibly leading to recession.

In equity market conditions like these, growth stocks typically take the first hit. Technology stocks, being focused on innovation and growth, are especially vulnerable. A Wall Street Journal article focused on this aspect of the recent market declines. However, by highlighting Dell and Microsoft, I am caused to wonder if they are truly "tech" stocks anymore. Both are large, sluggish, derivative purveyors of "technology" wrapped up in consumer-oriented boxes.

On the other hand, AMD was reportedly suffering from a price war with Intel, and saw its share price slide 16%.

Nevertheless, I think it's worth pausing to consider the long term perspective for equity markets right now.

First, as I learned on a recent CNBC report, most large-cap companies reporting earnings this season, for the 2nd quarter, are meeting or exceeding analysts' "expectations." Some of the major names cited as disappointments have already been in trouble, e.g., Dell, Yahoo and Ford.

Second, interest rates, while having risen, are still not yet high by historical standards. Money at 5-6% hardly constitutes a reason to believe the economy is shutting down.

Third, real gasoline prices are still below those of several decades ago. Admittedly, crude oil is not. However, as the accompanying chart shows (click on it to view the enlarged version), it's not astronomically higher than it was, on a real basis, during the 1973-74 Arab oil embargo. At today's $75/bbl price, oil is roughly $72 in 2004 dollars, as displayed on the chart. Our economy produces much more GNP per barrel of oil today than it did in 1974. If I'm not mistaken, as much as 4 times more.

And this higher price has already triggered investments in alternative energy sources of more traditional means, as I wrote
here recently. It's likely that demand and supply will continue to move about before settling at a level that fosters continued global economic growth.

I think that what we are seeing right now is the usual lemming behavior of many average investors, both institutional and retail, heading for the sidelines, and cash. They cannot see the underlying strength of the US economy, nor the relatively benign nature of current interest rates, which should forestall future inflation.

My proprietary market signaling methodology continues to register a healthy "long" position. As yet, I do not see a reason to panic, sell, or otherwise lose faith in the superior management of those companies which have shown track records of consistently superior performance.

Saturday, July 22, 2006

Intel's Big Review Completed

Back in May, I noted that Intel's CEO, Paul Otellini, was conducting a major review of Intel's troubled operations. In this post, and this one, I opined that perhaps Intel is the victim of its considerable success of the past 20 years. And that its current sales and marketing troubles are quite possibly a natural result of too much growth, diversification, and loss of detailed customer focus over the years.

Now comes a piece in the Wall Street Journal announcing Otellini's fixes for the firm. Apparently, two and a half months of soul-searching and deep analysis at Intel has resulted in a senior management reorganization of roles. Two retirements, no firings, and, otherwise, just a shuffling of spans of control, reporting lines, and such. The stated goal of all this shuffling is improved efficiency.

Given that Intel's problems seem to stem from not listening to customers, I'm a little puzzled to read that their solution is to rearrange current senior managment, but not directly address competitive marketing and product development. If anything, the apparent assignment of development and pricing activities to single senior executives would seem to make those functions even more abstracted from individual customers and business units.

Maybe I'm wrong. Time will tell. But thus far, it's fairly disappointing to see Intel limit its rehabilitation to essentially rearranging deck chairs, while AMD continues to surge forward with sales and market share growth.

Friday, July 21, 2006

Searching for Patterns in Financial Information: Part 1

Lately, my business partner has been reading about the similarities between the development of entropy theory in physics, and Claude Shannon's development of information theory. The parallels are striking, down to the similar forms of the equations for calculating the amount of entropy in a container of gas, or the amount of information in a set of symbols.

As we discussed this, we realized that, in an abstract form, "efficient market" theory is a crude way of approximating the same result. That is, a very efficient market would have little differentiation in prices for a security, much as an end state of a gas in a container is total dispersion to a (largely) uniform density.

However, of some interest to him, and me, was the development of probability distributions to account for the non-uniform density of dispersed gases. In a similar way, one might observe distributions of prices for a given security within a short period of time.

We realized that, according to efficient market theory, absent new information, the investors in a market are assumed to act in such a way as to arrive at a state of price entropy. Just as there is no more movement once a gas is perfectly dispersed, so prices are expected not to move, absent new information.

So far, an interesting comparison. But perhaps seen as just that, and of no particular value to understanding equity markets, or selecting equity portfolios.

As we discussed this further, he dwelt more on Shannon's information theory. Shannon focused on how to identify a signal amidst the noise of a stream of "information." This, my partner conjectured, is virtually identical to the task of a portfolio manager. The manager must attempt to identify relevant information, which is related to particular price changes, and ignore the noise in the distribution of information in the market.

At this point, I interjected that market information not random in the same way as naturally occurring phenomena may be. There are actors on each side of securities prices. Securities prices are not just streams of random numbers attached to a meaningless ticker.

Rather, there are real companies, composed of real people, behind each ticker. They are engaged in teleological behavior- hopefully, the production of profits, in order to increase total returns for their shareholders.

On the other side, there are real investors attempting to discern patterns from the torrent of market and fundamental information about the companies. These investors buy and sell securities, based upon their interpretations of this information, thus providing some goal-oriented impetus to prices.

I believe that because securities prices are, ultimately, the product of these goal-oriented activities, the process of identifying patterns in fundamental and technical market data, in order to find equities which have a high probability of earning consistently superior total returns, is actually easier than dealing with truly random data.

However, due to the differing abilities of the actors on both sides- company employees and managers, and investors- finding the patterns is not simple.


But, like distributions of energy levels in particles, or distributions of information content among symbols in a series, there are distributions of information with respect to equities selection among the fundamental and technical information available for observation. As a distribution, this means that there will be occasions in which information content is high. Meaning that not all the value in knowing it has been removed via discovery.

When this happens, portfolios of such equities can outperform the market averages, contradicting efficient market theory. Thus, in effect, we find that efficient market theory posits simple point-estimates of prices, whereas viewing the problem in the same manner as entropy or information theory allows for "tails" of value-laden information which can cause equities to be mis-priced, and allow for consistently superior returns to be earned.

Thursday, July 20, 2006

Revenue Growth Targets in Large Cap Firms

A recent article by Carol Hymowitz in her Wall Street Journal column, "In The Lead," which focuses on CEOs, featured Robert Lane of John Deere, the farm equipment maker.

The piece discussed Deere's commitment to R&D and innovation, though it cited no specific revenue growth target. By way of demonstrating that revenue growth is now a top priority among CEOs, Hymowitz quoted Jeff Immelt, CEO of GE, as setting an 8% annual revenue growth rate.

From my proprietary research, I can confirm that GE's sales growth target is too low to ever place it among the consistently high-growth, superior total return companies of the S&P500.

That is not to say that revenue growth below double-digits is useless. For those companies mired....er...positioned in largely slower-growth sectors, new products and services are necessary to offset the Schumpeterian effects of eroding value-added of older offerings. Rather like Lewis Carroll's "Through the Looking Glass, the Red Queen has characters run, and explains,

"HERE, you see, it takes all the running YOU can do, to keep in the same place. If you want to get somewhere else, you must run at least twice as fast as that!"

Just so. Without attention to innovation to drive revenue growth, even slower-growth companies will slowly experience flattening, then shrinking sales. Sort of like...GM.

It's great to see that even relatively staid companies such as farm equipment manufacturer John Deere is attending to innovation and growth. And it is also reassuring to see its CEO attending to revenue growth through innovation. However, targeting only 8-9% annual growth rates won't result in its escaping the gravitational-like pull of the large number of middling large-cap firms that experience inconsistent, or just slightly-above-average revenue growth.

And, thus, it's unlikely that Deere, or GE, will soon, if ever, be selected for our equity portfolios. It's hard work, but not exceptional, for a firm to generate consistent single-digit sales growth for years. Thus, the likelihood that such a firm will consistently outperform the S&P on total return is not as great as it is for consistently higher-growth firms.

Heavy Oil Reserves: Economics Still Works

There was a terrific article in the Wall Street Journal the other day describing Chevron's work on the recovery of heavy oil in Saudi Arabia.

What I found reassuring about the piece is that it reinforces my faith in human behavior and economics, which studies that behavior in the area of value exchange.

Basically, as light-oil reserves are drawn down, and crude oil prices rise, the incentive to recover deposits of heavy oil has risen. Chevron is working to recover the substantial Saudi reserves of this molasses-like material. According to the piece, including heavy oil reserves to the Saudi offical reserves would add "tens of billions of barrels" to their current 260 billion barrel estimate.

Buried in the article was a passing reference to the "peak oil" theory. According to the WSJ piece, adding recoverable heavy-oil reserves to the world's oil supply would put a major dent in the theory that we are on the brink of pumping ever-declining amounts of crude each year. This would appear to be no small thing. With India and China bidding up the price of existing supplies of crude in the past year, the prospect of declining crude supply would be a potentially civilization-altering phenomenon.

It's nice to see economic theory still describes how humans react to shortages. As crude prices have more than tripled since 2002, alternatives such as gassified coal, liquified natural gas, tar sands, and, now, heavy-oil are coming onstream to compete with the higher-priced light crude supplies.

Even at $3/gallon, gasoline is cheaper on a real basis now, in the US, than it was at the height of the Arab oil embargo of the mid-1970s. It remains to be seen if these admittedly-higher gasoline, and related, energy prices cause a global recession, but it is by no means at all certain. Recent estimates by economists put the chances at perhaps as high as 36%, up from 17% six months ago. When I read that, I thought it made sense. With higher energy prices and mideast violence, there is a natural concern that energy security issues will contribute to higher prices, and, thus, economic slowdown.

However, as recently as yesterday, Fed Chairman Bernanke reiterated Greenspan's comments of last year, that the US economy has displayed amazing resilience in the face of higher energy costs.

With the price signals of higher energy costs, new supplies are predictably coming onstream. Julian Simons would be so pleased to see his beliefs once again sustained. When these various alternative energy sources provide supply to the market, we should expect to have a near-term ceiling on energy prices and more supply for some time to come.

Crisis identified. Crisis resolved. Free-market style.

Like other resource supply issues of the past, such as silk (nylon, et al), rubber (synthetic rubber in WWII), and steel (minimills), energy, too, will fall to human ingenuity and the desire of people to make a buck solving economic problems.

Tuesday, July 18, 2006

Home Depot Revisited: Before Nardelli

Yesterday, I compared the recent performances of Lowes and Home Depot, in an attempt to understand the accolades given Bob Nardelli for allegedly "turning around" the fundamentals at the latter company since his arrival in late 2000.

In that piece, I found, using the data in the table above, from Compustat, that Nardelli does not seem to have outperformed his main competitor over the last 5 years. Home Depot's sales growth rate is not so impressive and is inconsistent as well. From my proprietary research, I would conclude that these operating characteristics alone account for Home Depot's dismal total returns since Nardelli's taking the CEO position. NIAT performance isn't much better, confirming the low regard in which investors seem to hold the company now.

It wasn't always thus. Back in July, 1999, I held Home Depot in my equity portfolio. It's performance was so strong and consistent, among that of the S&P500 field, that it was selected for inclusion, among other consistently superior companies. It subsequently returned roughly 60% from July to December, 1999.

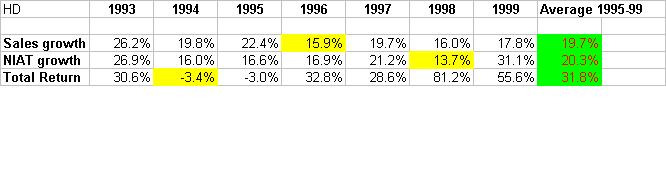
As the table at the left shows, the Home Depot of that era was a much differently performing company. Note the much higher growth rates for sales and NIAT. The green backgrounded column provides the simple averages for sales and NIAT growth, and total returns, for mid-1993 to mid-1999. The yellow highlighted cells indicate the minimum value for the measure during the period shown. Clicking on the table will bring up an enlarged view.

Comparing these values to the ones describing Home Depot recently, one can see why the firm was much more highly valued seven years ago. It was a consistently superior, growing large-cap firm.

It's total returns were correspondingly above-average. This type of performance of a large-cap company should earn the CEO extraordinary compensation. By contrast, Nardelli's 5 year record justifies nothing even close to a compensation package suggesting he has brought success to Home Depot.

Whether Home Depot's performance was bound to decline, due to time and probabilities, is arguable. But, if it were, even more reason not to overcompensate the next CEO for failing to offset those odds. However, what is curious to me is that Home Depot hasn't underperformed on total return because investors learned to expect excellent fundamental performance from the firm. Rather, its fundamental performance simply fell apart. And that has nothing to do with "uncontrollable market forces." Those are the types of problems CEOs are well-paid to fix. And Nardelli has not done that during his five years leading Home Depot.

Monday, July 17, 2006

Lowes vs. Home Depot: Nardelli's Performance

There has been considerable discussion of Bob Nardelli's performance and personal behavior during his stint as CEO of Home Depot. Nardelli arrived at HD in late 2000, fresh from GE, where he was also known as, I learned recently, "little Jack." I'm not sure one can say it was affectionately, unless perhaps by Welch.

While discussing the Nardelli/Home Depot flap with my partner yesterday morning, I contended that the reason for Home Depot's lackluster total returns under Nardelli are probably accounted for by the pattern of sales growth during his reign. My partner asked me to compare Lowes and Home Depot to see if my contention is correct. During the recent flare up of criticism over Nardelli's handling of Home Depot's annual meeting, several people commented that Nardelli has turned the company around, in terms of fundamental operating performance. He is apparently pitied for doing the right operating things, but getting "no credit" from the market, in the form of total returns for his shareholders. I wanted to see if this is, in fact, true, as did my partner.

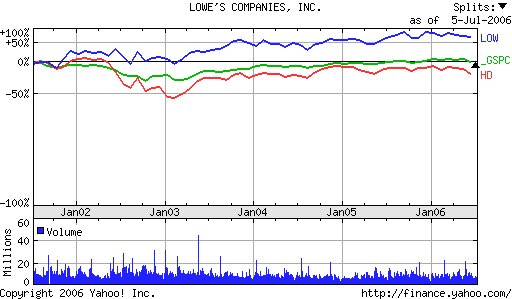
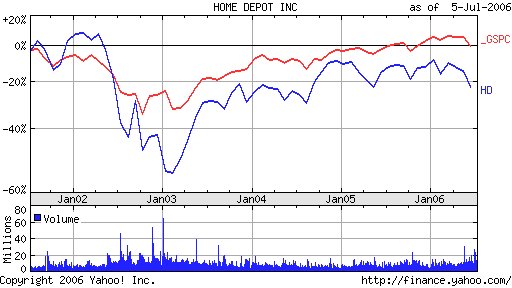
In order to evaluate these comments, I first looked at a Yahoo chart of Lowes and Home Depot's stock prices over the past 5 years. As I mentioned in a prior post, Lowes has clearly outperformed over this recent period.


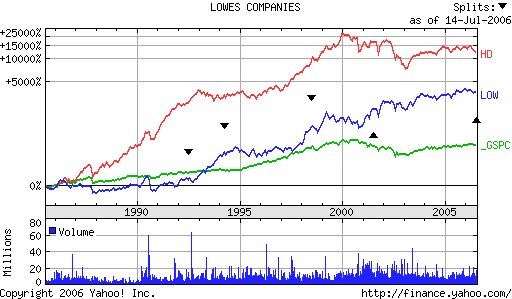
This is in stark contrast to the longer term performance of the two companies' stock prices. The Yahoo price chart at the left, going back to 1985, shows a much different picture.

Here, we see that Home Depot was on a tear, until ....oops...2000. Just before Nardelli took over, the company hit a flat spot, from which it has yet to recover. In fact, it's stock price has actually declined since Nardelli took the helm.

Lowes, on the other hand, has had a rather constant, although slower, stock price rise over the last 21 years. It was a little flat in the late '80s, then began a reasonably monotonic rise in stock price that continued until very recently.

Over the entire period, Home Depot was the better investment, and both Lowes and Home Depot outperformed the S&P500 Index. But, these views don't include dividends, in case they make a significant difference, nor fundamental data, such as sales or profit growth.

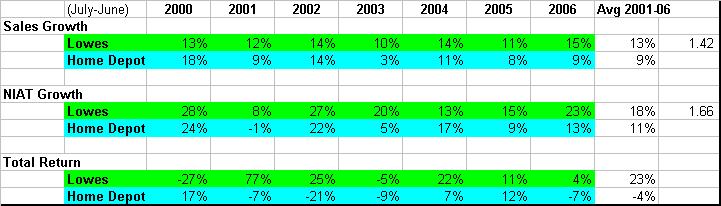
For that view, I went to my Compustat data and retrieved the total returns, sales and NIAT data for Lowes and Home Depot from July, 1999, to June, 2006. The table at the left displays the performances for the two companies on these fundamental and technical dimensions. You may click on it to see the enlarged view.

The top two rows display the annual nominal sales growth of the two companies since 2000. Leaving out 2000, in order to only measure the Nardelli years, we see that Lowes has an average annual sales growth of 13% during the period. This is 1.42x that of Home Depot's average annual sales growth of 9%. That seems to be to be a good reason why Lowes has done better for its shareholders lately. But look at the worst sales growth years for each firm. Lowes never dropped below 10%, while Home Depot had two years in which its sales growth was 3% and an 8%. And these were after 2002, well into the Nardelli era.

If Bob Nardelli has turned Home Depot around, we haven't seen it in the sales growth numbers.

Looking at NIAT (net income after tax), we see a similar pattern. Lowes' average annual NIAT growth is 1.66x that of Home Depot, or 18% vs. 11%. Again, Lowes' worst year featured an 8% growth rate, while Home Depot's was -1%. A decline. Not good for investor confidence.

Here, again, we see no evidence of the 'Nardelli operating turnaround' at Home Depot. I have to confess, I just don't see what Welch, Maria Bartiromo, and others are squawking about. Nardelli's company has lousy stock price performance because its operating performance is uneven and below that of its major competitor.

But, just to be thorough, let's take a look at the actual annual total returns since 2001. That is the third set of paired rows of data in the table. Home Depot's simple average annual return for the period is -4%. Lowes earned an average annual total return of 23% for the same period. Neither company has had a very consistent total return. Which would be at least one reason why neither would be among my equity portfolio selections for the past few years.


However, it seems pretty clear to me that, since 2001, Lowes has exhibited higher and more consistent sales and income growth than has Home Depot. The data doesn't seem to support a "turnaround" by Nardelli, unless his company was doing even worse before he got there. But the stock price data suggest that isn't true.

When you look at the data, Nardelli hasn't performed well for his shareholders on fundamental operating measures like sales and income growth. Is it really surprising the stock price is down, and the company's total returns have trailed both its major competitor, Lowes, and the S&P?

Friday, July 14, 2006

Carlos Goshn Speaks Out On CNBC

Carlos Goshn, CEO of Nissan and Renault, appeared yesterday in an interview on CNBC with that network's talking head, Maria Bartiromo. His visit was no doubt a coup for the network, as Goshn is now the most sought-after executive in all of the automotive sector.

Kirk Kerkorian, GM's largest, and predatory, shareholder, is desperately trying to find a way that Mr. Goshn can, effectively, run GM. To that end, Kerkorian and his associate, now GM board member, Jerry York, have proposed that GM enter an alliance with Nissan/Renault, thus hopefully securing Goshn's services on GM's behalf.

Judging from Goshn's statements in the interview, Kerkorian had better start praying that something else comes along to help GM and its stock price. Because Carlos Goshn made it crystal clear that he had no spare time for GM. However, most interesting were his remarks on what an alliance does for the parties involved.

Goshn explained that while such an alliance might help GM with shared parts, engines, perhaps platforms and designs, each alliance member is responsible for fixing their own company's problems.

Thus, Goshn ruled out being the white knight to come riding in, replace Rick Wagoner, and rescue GM. At best, he left the door open for GM to join the Nissan/Renault alliance, swap equity stakes, and help itself with access to knowledge from the other two members.

I'd say this puts another nail in GM's coffin for the long term. While Rick Wagoner may not be out of a job because of this proposed alliance, he may well be out of a job due to continued unsolved problems and lackluster performance at GM.

Goshn came off as a very resolute, no-nonsense, pragmatic and realistic executive. Pretty much the opposite of Wagoner. I can see why Goshn solved Nissan's problems. And from some of his remarks, I think, were he to actually assume the title of GM CEO, he'd "rescue" GM by carving out a much-reduced core company of decent products and cost structures, while summarily shedding much of the giant's outmoded asset and personnel bases.

It should be very interesting to watch Kerkorian's moves during the rest of the summer, as the alliance discussions and subsequent maneuvers pan out. But, suffice to say, I wouldn't go buy GM stock based upon what I heard from Goshn yesterday.

Thursday, July 13, 2006

Free Media Publishing Leaps Into Video

Bill Gates Praising the Mac


Here's a little example of why Time Warner and other "old" media conglomerates are in trouble. It's a video clip of a much younger (than now) Bill Gates at an Apple developers conference. I found it on YouTube, and linked it to this blog post. Mostly just to demonstrate a point about technological advances in free online publishing.

I wrote a
piece about YouTube recently. It's the online video clip site which functions somewhat like ShutterFly or PhotoBucket. My consulting friend S remarked to me the other day that YouTube allows clips to be linked to blogs. In her words, now "everybody is a star." Or soon could be.

She and I have debated the coming integration of online video entertainment and broadcast/cable content. YouTube adds another interesting bit into the mosaic.

Consider what has now happened.

This blog is free to you and me. Google supplies Blogger for free, even without the ads. Dominating more content in a surging product/service space is reasonable strategy, if the basic cost of doing so is buying more servers. I eventually realize something like the price of a cup of coffee for any click-through revenue from the ads on this blogsite.

Now, YouTube seamlessly links its clips to Blogger. Anyone who shoots digital video of interest can post it for free on YouTube. Competition for content has become so stiff already, that YouTube's competitors, such as Revver, are paying people larger slices of ad revenues to post videos on their site.


This morning, the on-air staff of CNBC held a hand-wringing debate over blogs. Apparently, there was a recent incident in which some blogger posted false information about a company, and its stock price suffered.

Aside from the hilarity of an entertainment show like SquawkBox, the show on which the 'debate' aired, treating blogs from a 'news' standpoint, their discussion demonstrates how much reach independent, "free" published media now may have.

Commentary and editorial blogs, such as this one, are unlikely to be running afoul of any laws regarding insider trading. With increasing amounts of online media available on which to comment, and a free base of operations, how much value added can large media conglomerates create anymore, outside of pure entertainment? It seems even they can't make their news operations pay for themselves. And commentary can be published by anyone for free.

Granted, distribution is a challenge. But it's a far cry from a decade ago, when it wasn't even feasible for someone to write a daily "column" without a syndicated deal with a newspaper chain.

If I wanted to, I could "cast" this blog in video, and post it, without cost, on iTunes or YouTube. In the case of YouTube, I can automatically link my video back here to a post. Somebody else's business model is paying for all the transmission bandwidth, disc storage, and server processing to make this happen. In fact, Google's, and other new media firms' business models are all about generating revenues from viewers, not providers. And not even making the viewers pay directly or explicitly, but, rather, through advertising.

Now, where did I see this before? Oh, right. It's the new version of the "old" televsion business model. Except, this time, it's eviscerating broadcast television.

With the arrival of direct viewing of media content on your television, from the internet, cable revenues from "repackaging" content from "channels" and networks will begin to suffer as well.

My, how times have changed. Now, I can read or hear a story, or view a clip, and write about it the same day. Even link, in many cases, to the story or clip. As I did in my recent piece about Jack Welch in Fortune Magazine. Or downloaded this Bill Gates clip from YouTube.

In a world that supports and embraces this sort of inexpensive integration of multi-media, editorializing, and analysis, what does that portend for the media giants of our time- NewsCorp, Time Warner, McGraw-Hill?

Consider what this integration means to the music divisions of media conglomerates, such as Time Warner. Would a new band not now be able to digitally shoot a video of their performance, and post it free to YouTube? Then link the video(s) to their website, and publish the website URL at their concerts? Then go straight to iTunes with the content they record from digital tools on their iMacs, and....voila! Where's the big publishing giant in the middle? Gone.

Suffice to say, I'll be surprised if any of them appear in my portfolio's selections of consistently superior, high-growth companies.

Stop the Presses: Goshn & GM

Yesterday's Wall Street Journal carried a very illuminating piece on Carlos Goshn, Renault, and the potential alliance between Renault, Nissan and GM. This is Kirk Kerkorian's hopeful gambit to exit his considerable position in GM stock at a profit.

What the Journal pointed out, however, is that, while Goshn did turn around Nissan, as he promised, he hasn't yet succeeded with Renault. After 18 months of work, according to the article, Renault is still valued at zero, awaiting Goshn's magic touch. The other pieces of the alliance allegedly comprise the value of the outstanding stock, indicating that investors are awaiting Renault's rehabilitation.

What this means, as the article pointed out, is that GM & Kerkorian may have to wait in line for quite a while for this alliance to develop. Or to show results, if it does develop.

Maybe Rick Wagoner doesn't have much to worry about from Goshn & Co. just yet. And maybe I was premature in suggesting, earlier this week, that my prediction of one less CEO in Detroit is nearing reality faster than I had expected.

Still, it's not good news for GM's shareholders. I think the suggestion of the alliance simply puts GM in the "intensive care" unit for the forseeable future. And as I've written before, I would not look to the prior and current management team to fix what they messed up, on such a large scale, to begin with. My guess is that this new revelation about Goshn's capacity to help GM means the latter will likely be foundering a while longer.

In any case, it highlights a potential pitfall in GM's path out of its misery. And its shareholders are by no means out of the woods yet, by a long shot.

Wednesday, July 12, 2006

Jack Welch's "Way" Returns to the Spotlight


Today marked the first time in ages that Jack Welch has made an appearance on CNBC.

The occasion was to discuss this article, recently published as the cover story in Fortune magazine. It contends that Jack Welch's "rules" are now out of fashion. That he was a star CEO for the 1990s, but is now passe.

This morning, Welch appeared on CNBC, in a polo shirt, with a lush pastoral scene as a background, from Nantucket. Clearly, Welch chose to rebut the article in the role of retired, wise ex-CEO, rather than suited defender of a track record.

There are several aspects to this topic. One is Fortune's article. The next is Welch's rebuttal. And, finally, there is Welch's actual performance, which is purportedly the basis on which his now controversial views were built.

Betsy Morris' piece is of a mixed nature, in my opinion. While some of her "new rules" are different than Welch's explicit pronouncements, they are not necessarily things with which he would have, or now does, disagree: organizational agility, focus on building niche markets, hiring passionate people, and looking outward from the company.

Morris' "old rules," attributed to Welch, smack of being straw men. I don't personally recall Welch saying any of them verbatim as presented, except for the time honored, still-relevant advice to be #1 or #2 by market share, rather than compete as a distant also-ran. So in this case, Morris probably overstepped herself.

In the main, though, I think her points are well taken. She restated and sharpened them on CNBC this morning, appearing about 20 minutes before Welch did. She essentially noted that Welch and his 'six sigma' preoccupation tended to focus on wringing efficiency from existing businesses. She opined that today, popularly-lauded companies such as Apple and Google rapidly design and release whole new categories of products and services, whereas GE tended to carefully crawl along, grinding out steady earnings increases, rather than torrid product change and revenue growth.

Now, to Welch's reply. He first dismissed the whole matter as directed 'against my wife, Suzy, and me, because we write a weekly column for BusinessWeek, Fortune's competitor.' Then he also dismissed remarks by United Technologies CEO George David, reputed to rebuke Welch, as taken "out of context."

After these qualifiers, Welch essentially lampooned Morris' list of "old rules," and claimed that, in fact, her "new rules" are, in reality, his. And were all along. Welch steadfastly disputed that 'his era' is over, or that his approaches, as CEO, would no longer work, 5 years after his retirement.

A few comments on the matter thus far. Nobody but Jack Welch mentioned his current wife ( #3?) in all of this. Suzy didn't run GE for more than a decade- Jack did. Frankly, I don't really believe anyone else cares what Suzy Welch does or does not think about management.

It's unlikely that Jack Welch would have been against Morris' "new rules," provided that they ground out earnings which fit Welch's GE management style. However, they clearly were not his major foci while leading GE.

My revered mentor, an ex-GE senior planning exec, and Chase SVP of Corporate Planning, used to say, "there are hundreds of business aphorisms, some contradictory. The question at hand is, which are relevant in this situation, for this business."

That's really the nub of the Welch tempest right now. Morris is trying to say, 'Welch never said 'nimble,' so he's against it, and now it's important.' Welch is saying, 'only an idiot would be against a nimble company- I was always for 'nimble.'

Frankly, neither is totally correct. But, on balance, I think Morris is right.

Despite Morris' citing companies which are, themselves, not consistently superior in growing and delivering total returns to shareholders, I believe she is right in applauding the focus on raw revenue growth and market creation which is shared by companies like Apple, Google, or Gilead.

As I have written before, in this blog, size, by itself, is of little value anymore. Witness GM and Ford. IBM and Microsoft. Intel.

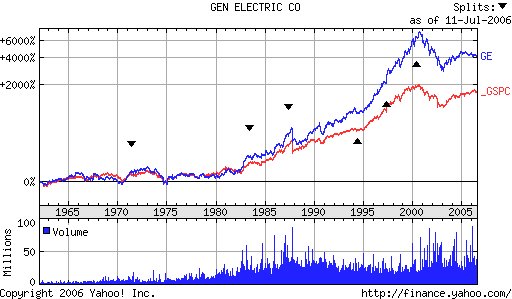
As the chart at the top of this post illustrates, even Welch didn't really manage GE to consistently outperform the S&P over his tenure, from 1981 to 2001. He had a few brief periods of radical outperformance, notably his restructuring of the firm upon his accession to the CEO post. For the most part, GE has never been a highly-consistent growth company which has outperformed the index (GE has never made my portfolio's list of consistently superior performing companies among the S&P500 candidates). I pointed this out to Welch, in person, in a meeting in the mid-1990s. He was shocked, and, literally, speechless for a few minutes, as he studied a chart I presented which showed GE's share price against the Dow-Jones since he took over GE. His comment, when he next spoke, was, "nobody's ever shown me this chart before." Suffice to say, the chart demonstrated that Jack had not added all that much comparative value for his shareholders over his tenure to that point.

As I wrote in a prior post, the most value Welch ever created for his shareholders, comparatively, with the market, was his brilliant triage of the sluggish firm he inherited from Reg Jones, amidst the worst inflationary environment of the modern US business era. The Jones era, for GE, was, as the chart above shows, dismal. Welch revitalized a tired company which had lost its focus and direction. However, owning GE didn't reliably provide equity investors with consistently superior growth and return prospects, as holding many other S&P components would have, over the past 20 years.

Among all of Welch's portfolio of businesses, GE Capital was the only really reliably high-growth unit. Upon taking over GE, Immelt was assailed by critics who suddenly had the scales fall from their eyes, and realized how heavily leveraged the unit was. Somehow, Welch managed to sprinkle magic dust over this easily-observed fact, during his tenure as CEO. Immelt suffered for the clever diversion of analysts' attention to predictable quarterly earnings sans consistently superior topline revenue growth for the firm.

So, for me, this whole episode, while entertaining (hey, it's on CNBC- what'd you expect?), is moot. Welch's GE was never one of those rare, consistently superior growth and return companies which are the hallmark, and components, of my investment portfolios. Arguing over "his rules," is, in my opinion, totally beside the point. If he'd run a more impressively-performing company, I'd feel differently.

But Welch didn't, so I don't.

Tuesday, July 11, 2006

Ford's "Way Forward" in Brazil

Yesterday's Wall Street Journal featured an article about Ford's "Way Forward" program successes in Brazil.

I have to say, I was unimpressed with what it portends for the giant auto maker.

To distill the well-written article to its essence, the Brazilian unit of Ford has scored major gains with a new SUV model by doing two things: sensibly restructuring the physical manner in which they produce the car, and doing intensive consumer market research to design a car which the relevant market segment will buy, at a profitable (to Ford) price.

The good news, of course, is that some people at Ford down in Brazil, led by one Luc de Ferran, pulled this off. It's inspirational, and certainly better, as the saying goes, "than a sharp stick in the eye."

However, the bad news is that this "turnaround" at Ford Brazil is nothing fancy. Basically, the unit had fallen on extremely bad times, and simply rediscovered what, I believe, intelligent business people everywhere would acknowledge are obvious maxims.

They redesigned manufacturing to adapt to current realities, thus cutting wasted time and expense. They returned to classic marketing in the design of a new vehicle, using consumer research to uncover wants and needs, the incorporation of which, in the new Ecosport SUV, caused the car to gain an 80% market share.

This anecdote brings me to recall some of my prior posts regarding mediocrity and ineptitude in the general business environment. Specifically, this post about UAL, this one about Starbucks, and this one about Intel v. AMD.

Why is that Ford's Brazilian unit, or, for that matter, Ford itself, globally, must have its back to the wall in order to rediscover basic business sensibilities?

I suspect that the reason boils down to one word- discipline.

In a process which parallels Aristotle's thoughts on the decline of governmental systems from the pinnacle, the 'philosopher-kin' phase, I think corporate leadership/management undergoes something very similar.

When a company is "on top," competitively and in terms of consistently delivering superior total returns for shareholders, a sense of complacency begins to set in. The questioning, innovative behaviors which probably drove the company's success, begin to be institutionalized by a second tier of acolytes as 'revered processes.' The originators of the initial success move on- retirement of the lauded CEO, perhaps a few SVPs move to head other companies. Too, some of the wizards of the successful change are promoted, focus upward, and leave the nuts and bolts continuation of the success to less-capable subordinates. The new generation of leaders begin to do two things: view the changes wrought by the earlier successful managers as 'codes to live by,' missing the fundamental value of the changes having led to success, not the particular endpoint of the organizational, product, etc, changes, and; beginning to introduce some of their own changes.

Truth be told, management teams that drive companies to truly excellent, consistently superior performances, are pretty rare. Whomever comes after them, like Paul Otellini at Intel, faces are daunting, and, essentially, more difficult task.

In time, the company begins to fill with lesser-talented management, its performance coasting to 'good,' from 'consistently superior.' The focus on prior methods and successes makes it hard for a less-talented group to recapture the successes of an early management generation.

If the company is lucky, another group will rise and repeat the earlier fundamental business practices that, once again, restore manufacturing, production, and/or service delivery to more productive levels, while introducing more relevant new products and services.

In short, it seems that, in large companies, there is simply a lack of discipline, over time, of management to value and retain a focus on 'purposeful change' of the company and its practices. It's as if nobody watches the measurements of performance which might signal that it's time for the company to innovate and change once again.

So, in a sense, Ford is no different, I suppose, than the average US company. And that's both a pity, and, I think, my point. The WSJ piece merely confirms that Ford is a normal US large-cap manufacturer that loses its way more often than it finds it.

Trouble is, today, it may have much less time and financial leeway to recover one more time.

Saturday, July 08, 2006

Why Consistency?

At lunch with my partner last week, we discussed why we have a long-term approach, in a market of frequent trading. We hold portfolios for months, rather than trade monthly, let alone weekly or daily. And our analysis takes into account several years of performance, in order to find consistently superior performers to buy and hold.

This market demonstrates why. Volatility is very high over short periods of time. Given the various forces and factors influencing investors- Fed rate hikes, oil and natural gas supply, Mideast oil supply worries, and, now, North Korean aggression- market prices in various equity sectors gyrate swiftly.

In my proprietary research, I found that many 3-year phenomenons are not 4 year successes. While the average returns for the market is remarkably stable over various timeframes, the standard deviations of those returns are markedly higher for relatively short time periods- less than 4 years.

In fact, some returns which are not even beyond one standard deviation from the market average return at 2 years will be well beyond that measure at 4 years. This means it is a much less rare event over a short timeframe, and a much more rare event over the longer timeframe.

Thus, the loss rate would be high for equity selections, based upon extraordinary 2-year returns. Seasoning the selections for 2, or even 1, more year, knocks out quite a few of them.


What it boils down to, from my research, is that the best way to select for consistently superior performing companies in the near future, is to find which ones have already been doing it in the past. From various prior posts on this blog, it should be evident that I do not hold out much hope for the broad mass of average employees, managers, CEOs and companies to change their behaviors and suddenly become above-average. It is much less risky to find companies which already display consistently superior performance, and simply expect a little more of it over the coming months.

Friday, July 07, 2006

Kerkorian's GM Alliance: Almost Time for a Victory Lap

Two articles in this week's Wall Street Journal, plus extensive coverage on CNBC, have laid out what Kirk Kerkorian has planned for GM. He's aiming to engineer GM's entrance into the Carlos Goshn-run alliance of Renault and Nissan.

Holman Jenkins wrote very succinctly about exactly what is going on here, in his regular weekly WSJ column. In effect, he said, Kerkorian is prepared to offer GM to Goshn, to finally get Goshn to run the place, since he couldn't lure Goshn to GM outright.

With the added talk of GM CEO Rick Wagoner's departure, should this occur, it demonstrates that there is a more serious approach to fixing GM. Wagoner is written up as the champion of a 'slow and steady' turnaround. Goshn has credentials for having actually succeeded in a rapid, well-motivated restructuring of his car company alliance. Rather than creep along with half-measures, Goshn confronted and acknowledged the severity of his situation, and moved adroitly and quickly to save his firm from collapse.

I wrote here, here, and here, back in the fall of last year, about GM's serious likelihood of losing its corporate life, and/or its independence. I see that I gave the company until the end of the decade, whereas I thought I had predicted this end within 24 months.

In either case, while it's too early to take my victory lap now, for being right, I'll get the track shoes out and begin stretching.

Reading these prior posts I have linked above, it reminds me of how much in denial the analyst media and consulting community have been about GM's and Ford's actual peril. They all seemed to worried about angering a still-spending auto giant to do their jobs and tell the truth.

Well, now they are reporting the truth, as it happens in front of them. Rather like the brokerage firms that downgrade a stock the day after it drops 20%.

You heard a warning of the fatal condition of GM here first. Having nothing to lose, it seemed easy to me to call what I saw, and reason that GM does not have long to live as an independent auto producer. Above all else, their long-running inability to design and market cars many people will pay sufficient prices for, has doomed the company. It's simply too late for them to overcome years of bad leadership and management.

Between economic uncertainty, energy prices, and competitive pressures, GM can no longer afford even one misstep. That's just too much risk for Kerkorian to take on his substantial investment. You have to hand it to the wily old guy. He has totally outsmarted the corps of analysts and media onlookers who have been clucking at Kirk's loss of touch in the GM caper.

This past week, all I hear and read about is how Kerkorian is slyly engineering a no-premium takeover, sans proxy fight and board battle. And he's even brought allies to the table that nobody had dared consider even a month ago. Talk about insight, discipline and fortitude. Kerkorian would seem to have earned every cent he's made with his bare-knuckle investing style.

If all goes well, Kerkorian will let common sense and fiduciary duty pressure the GM board into accepting his recommendation for the three-way alliance, run by Goshn. Wagoner will depart. And my prediction about GM or Ford leaving the field of independent car makers will come true way ahead of schedule.

Thursday, July 06, 2006

Corporate Governance: Bob Nardelli's Interview on CNBC

As I write this post, I am listening to/watching Maria Bartiromo's interview with Bob Nardelli, CEO of Home Depot. Irrespective of my prior remarks about Bartiromo, she is certainly giving Nardelli a fairly "hardball" interview. To my pleasant surprise, she has asked direct questions about Nardelli's annual meeting fiasco.

As for Nardelli, his performance in the interview's opening moments is nothing short of robotic. Clearly, Home Depot hired the best public relations talent they could find to carefully script his remarks about the annual meeting. Nardelli was obviously told to "stick to the script," period. No deviations. No ad libs.

That script consisted of simply saying, to paraphrase, "We tried a new style of annual meeting. I take full responsibility. It didn't work well. We will return to our prior format next year." When Bartiromo pushed him for an answer as to why the director-less format was tried this year (and, to her credit, she actually asked, verbatim, "what were you thinking?!"), he repeated, several times, again, to paraphrase, "We are a society that likes to ask questions and blame. This is in the past. We won't do it again. We'll go back to our prior format next year." Meaning, he is not about to discuss the highly probably reason for the attempt to muzzle shareholders- his egregious pay package in the face of consistently poor shareholder returns for the 5 or so years he has run Home Depot.

As to the matter of his options, he avoided admitting the rules were changed for him, to his benefit, regarding the awarding of the options. Rather, he kept stressing that, if he doesn't get the stock price above the strike price, he receives nothing. Again, ducking the "why" and focusing on the "what if?"

Nardelli then went on to extol his supportive board. Yes, with the compensation treatment he's gotten, what else would you expect? Further, he spoke of their patience and support for his strategy. Meaning, I guess, that he's happy they haven't noticed that, under his leadership, Home Depot's total returns have been abysmal. According to Bartiromo, the company's stock has plunged 30% during his tenure. And 20% over the last 5 years. Lowes has done much better for its shareholders over the past 5 years.

His clever attempt to dodge responsibility is to lay it on....his board of directors. According to Nardelli, since his board has continued to employ and pay him handsomely, he must be doing alright. Nevermind that, like most boards, they would be beholden to him for nomination and continued membership. Nice 'virtuous' circle for Bob and his board- not so nice for the company's owners.

In his "final remarks," as solicited by Bartiromo, Nardelli sidesteps the poor total returns, and hammers away at the fundamental financial results, and, in his opinion, the company's 'solid commitment to corporate governance.' In short, he's being paid millions of dollars, but hasn't a clue how to affect his company's performance in ways which will result in consistently superior returns for his shareholders.

It was an interesting experience to watch a very nervous CEO bob and weave his way through a minefield of negative topics without departing from his carefully rehearsed script. He simply denied that Home Depot has problems which he is capable of solving. That is, something outside of his control is responsible for all their woes.

If I were a Home Depot shareholder, I'd want a new CEO, effective immediately. If the CEO doesn't see himself as responsible for the mediocre returns of the company he leads, and has no ideas on how to affect that performance, how can the company go wrong replacing him with someone who will try to boost the company's total return performance?

Time Warner and AOL Give Up on Marketing Management

Time Warner's latest plans for its AOL subsidiary are curious for their abandonment of marketing management principles. As I understand the plan, they are considering giving the entire AOL package, including email, free, to anyone with a high speed connection, just like yahoo, msn, and google.

On one hand, this may seem like a recognition that AOL really offers little of value for which people will pay, when the aforementioned alternatives are available.

However, AOL does earn revenue from users, despite the alternatives. Some people probably have both- an AOL account for which they pay, and use as an ISP, as well as free email accounts with one or more of the other providers.

Is it really smart to paint all of your customers with the same brush, and offer any of them who have their own access a 100% discount on the service? Are there not any user segments who will remain with AOL on a paying basis? Since they have that $2B of annual revenue already, why prematurely and voluntarily refund much of it? Why not raise prices on the most primitive, dial-up users, and maintain prices on those who, for whatever reason, still don't move their high-speed accessed accounts elsewhere?

Thinking back to my
prior post, about Wal-Mart's foray into financial services, it seems that Time Warner is taking the opposite tack. Whereas Wal-Mart focuses on how to segment its customers, and better serve them through that understanding, Time Warner seems to be going the opposite way. They just lump most of their customer base into one bucket, and give their service to those people. Whomever they are. AOL isn't even talking about, say, developing customer profiles to use in making offers of reduced priced services to those most likely to leave AOL.

I think this reinforces the view that AOL is mismanaged, and Time Warner is compounding the problem with another layer of inept management on top of the online unit.

Carl Icahn, please call home......

Wal-Mart's Big Financial Services Dreams

Today's Wall Street Journal contains a story about Wal-Mart's planned big push into low-end financial services. We are talking here about payroll check cashing, wiring money, and bill paying.

From reading the article, it looks like Wal-Mart, with its size and diversified business lines, will be able to offer these services at a significant discount to the prices typically charged by those vendors who prey on low-income financial services customers. Perhaps the best example is payroll check cashing. Your typical local 'service' provider will charge a user 2-3% of the face value of the check. Wal-Mart charges a maximum of $3/check. Do the math, and for a blue-collar worker who earns $20,000/year and is paid something like $650, net, every two weeks, the average current check-cashing fee is nearly $16. So Wal-Mart will be providing enormous value to low-income consumers, who also happen to be its major target market. The company noted that it also currently processes 1.5-2MM money-services transactions per week.

On first glance, I thought Wal-Mart might get tarred for this business expansion. You can just imagine some consumer advocates picketing the big-box giant, charging that it is merely jumping in to get its share of vigorish from its financially struggling customer base.

But that doesn't seem to be the case at all here. Wal-Mart's money orders cost $.46, compared with $1.30 at the US post office. The company appears to be delivering substantial value to its customers with this suite of services.

However, that said, I don't think it's going to do an awfully lot of good for Wal-Mart over the long haul. In response to charges by a spokesman for the Massachusetts Bankers Association that "Wal-Mart wants people to cash their checks in their stores so they can then make impulse purchases in the store," the company replied that only 'about 14% of people who cash checks at the store make purchases at the same time,' according to the WSJ article. That would work out to about one collateral purchase trip for every 7-8 financial service visits. In effect, 6 times per year.

And, by the way, kudos to the bankers in Massachusetts for managing to come off explicitly as a group of bloodsuckers. By saying it's ok to charge egregious fees on check cashing for poor people, but heaven forbid those people save on the fees and spend some of that extra money on real goods they can take home with them, this group appears to want a monopoly on taking advantage of the least-well off in our society. At least Wal-Mart has demonstrated that, by intervening, they will actually give these poor people real benefits that they can't get from today's banking sector.

So, essentially, what we have is the Schumpterian phenomenon of Wal-Mart weighing in to gut value-added dollars in the low-end financial services sector, in order to transfer some of that value to its customers, thereby strengthening the company's position in that segment. I don't think Wal-Mart will profit, per se, from this move. It is mostly defensive.

In fact, it kind of makes you wonder what happened to Wal-Mart's purported move, last year, upmarket. Isn't this financial service expansion at the low end going to blur that repositioning?

It seems kind of ironic to me, by the way, how things have come full circle. Back in 1974, in my very first marketing class, I learned that Sears was then earning more gross dollars of revenue on the interest in charged on customer credit card balances, than it earned on merchandise margins. Of course, in the intervening 32 years, that has been radically changed. Retailers lost the entire captive financial services business to GE and the banking sector. Now, a large, cost-effective retailer comes back in to underprice the financial service sector on low-end services, in order to build more customer loyalty and, probably, gain some extra margin/square foot of floor space.

More on Corporate Governance: Executive Compensation Continues to Rise

The Wall Street Journal recently used the occasion of Pfizer's annual meeting to run yet another piece about exorbitant CEO compensation packages. Carol Hymowitz wrote a very nice piece detailing the realities of this problem.

When asked to defend Pfizer CEO Hank McKinnell's compensation, Dana Mead, head of the board's compsenation committee, did so by saying, '....Mr. McKinnell's pay was based on market forces and reflected his responsibility overseeing 110,000 employees."

The article notes that "disgruntled shareholders even tried to unseat Mr. Mead and another director this past April but failed."

What is irksome to me is that Mr. Mead didn't say something like, "Mr. McKinnell has the responsibility to earn above-average total returns for you shareholders. In hopes of attracting talented leaders to be our company's CEO, and make that happen, we need to offer a competitive compensation package. If Mr. McKinnell proves unable to meet this responsibility, he will be replaced with someone in whom we, your board members, feel is better-equipped to carry out this responsibility."

Ms. Hymowitz quotes Lucian Bebchuk, a Harvard University law professor, who notes that the board is beholden to the CEO for their membership and, thus, pretty much have to repay him/her with bloated compensation packages, and that "they don't have an incentive to change those arrangements."

Well, that really says it all, doesn't it? You have a board charged with CEO oversight, but who nominates the board? The CEO. Wonderful! I guess having no board is marginally more corrupt, but, judging by modern CEO compensation and corporate total return performances, not by much.

Though the article closes with comments on the competition for good CEOs as the reason for excessive compensation packages, I have my doubts about that. Look at corporate performance, and you'll see that very few CEOs seem to be able to achieve consistently superior returns for their shareholders. It should be fairly easy to design a CEO compensation package with the predominant proportion of it structured as variable, and payable upon attainment of consistently superior returns for the shareholders. That way, shareholders only pay for the performance. As I have written elsewhere on this blog, why would you want a CEO who doesn't think s/he can do this in the first place?

Sunday, July 02, 2006

Ford & GM: Recent Developments


Ford and GM's recent developments were the subject of a short piece in this week's Wall Street Journal. The author of the piece only went back to January of this year to issue his opinion. His verdict was that GM is in better shape for a "turnaround" because of outside pressure from Kerkorian, while Ford's two-class stock structure kept its value from rising due to the founding family's insulation from common investors. His conclusion is that Ford is less market-sensitive, due to the Ford family's near-controlling 40% voting stake in the firm.


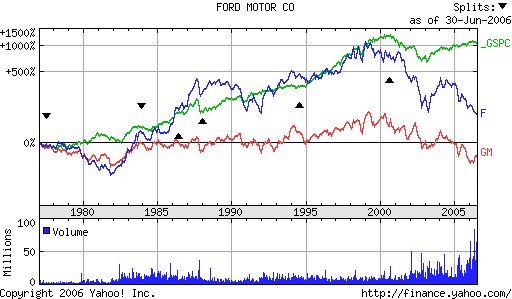
I find this a touch myopic, as the longterm Yahoo chart above shows. Comparing the S&P500, GM and Ford since 1979, it puts the lie to the notion that Ford has typically been slow to respond to market forces, due to the Ford family's control of the firm. Sure, in 2006, GM has displayed a better shareholder return than that of Ford. No question about that. Just not being in Chapter 11 yet is probably a big boost for GM.

However, if you look carefully at the chart above, it continues to echo what I discussed in a recent post about these two firms. While Ford's voting structure may shield it somewhat from market forces, it still has outperformed GM over the past quarter century. And by a rather handsome margin, as GM has been negative, while Ford looks to have returned something in the neighborhood (interpolating on the chart above) of 100%. The S&P returned roughly 1000% over the period.

That Ford had some significant "up" periods, from the early 1980s to 2000, suggests that they were, in fact, quite sensitive to shareholder returns. GM, by contrast, rarely broke out of a flat return curve, save for a few years in the late 1990s.

My point is that, due to an unnecessarily short analytical time horizon, the WSJ has summarily judged Ford to be too insular to save now. While GM, through the mixed blessing of attracting Kirk Kerkorian, and his lieutenant, Jerry York's advice to find a global partner, has temporarily surged ahead of the former in total return terms.

I don't necessarily believe Bill Ford is turning, or will turn around Ford. His "way forward" seems "way too optimistic," in my opinion. If only because the management team that got you to where Ford is now, is unlikely to take you somewhere else, as a shareholder. But the company is sensitive to market pressures all on its own.

I don't think GM is more "investor sensitive." Instead, it has to deal with a veteran value shopper, in Kerkorian. As the WSJ, as well as CNBC, articulated, what's good for GM shareholders, the prospect of a partial rescue in the form of some global tie-up with the likes of Nissan, is probably not good for CEO Wagoner. If anything, Wagoner put GM where it is today through his learned insensitivity to market forces, as a result of a long tenure at the stumbling auto giant.

Yes, GM may well have marginally brighter prospects for its shareholders. But don't attribute GM's idiosyncratic fortune to Ford's share voting structure. Ford is in trouble due to inept management that has tried to grapple with global pressures on an aged, badly-led competitor. Not due to an unwillingness to acknowledge the problem.

YouTube Comes Out of the Garage

YouTube must be nearing a significant milestone of some sort. The Wall Street Journal mentioned it in two different pieces in the last two weeks.

One piece covered a multitude of approaches being developed to provide video from the web to the home. YouTube doesn't address the last few feet, from the cable to the TV. But it is far and away the most visited video website, according to the WSJ's article.

What is remarkable about YouTube is that you can see it visibly following in the footsteps of Microsoft, eBay, Yahoo and Google. It was fashioned as a personal solution to a problem- sharing large video files between friends and acquaintances.

It's now become larger, gotten VC funding ($3.5MM from Sequoia), hired a Yahoo veteran to build their sales team, and begun to explore longer-term profitability models linked to their core service.

Along the way, commenting on these points, and the huge traffic YouTube boasts ( 3 million videos viewed daily, as of Dec. 15, 2005), the Journal pointed out that the two founders, literally in the apocryphal garage, had out-innovated a host of existing, large media companies ( e.g., see my recent post on moribund Time Warner). Now, several large media corporations are rumored to be sniffing around YouTube, looking to acquire it.

It's truly gratifying to see this type of company develop as it has. For me, it maintains and nourishes my faith in enterprises which begin with keen consumer behavioral insights and a savvy, gritty sense of implementation. Rather than oozing forth from the likes of Disney or Time Warner, this type of high-energy, edgy operation springs up from virtually "nowhere." Mainstream media firms would probably bog down over the copyright issues that YouTube has from user-posted content that is inappropriately published, resulting in their legal departments becoming profit centers due to bizarre time and cost-allocation methods. Instead, YouTube deals with these matter with alacrity, gently letting its popularity and 'cool' image persuade some of the larger copyright holders to look for ways to work together, rather than try to stomp YouTube out of existence.

I have no idea where these two guys and their firm will end up. But it's a lot of fun, and instructional, to watch them rip through the electronic media world, successfully meeting needs and attracting customers, while overpaid suits in the suites of a variety of larger competitors sit and stare at their coming downfall. I have to believe that Joseph Schumpeter would be extremely proud and not at all surprised to see YouTube rocketing across the online video publishing sky, threatening established vendors across the media sector.