Today's Wall Street Journal featured an article in the first column on page one, concerning the newest trend in corporate motivational speakers- disabled people who survived personal trauma.
I won't go into details regarding the various people with physical or other handicaps who are making substantial amounts of money on the speaking circuit. And I don't wish to make light of their very real infirmities, disabilities, etc.
However, I'd like to focus on what the employment of these people by corporate leaders, for motivational purposes, implies.
To me, it's essentially saying to a company's workforce,
'Dear employees...we've dealt you a sorry corporate hand....live with it..no, wait, better yet, let's get someone in here with a personal tragedy which they had to overcome....now, maybe you will feel that the situation in which we pay you to be, is, in fact, your own personal life tragedy, and you'll move heaven and earth, for no more money, to make our corporate objectives feel like your own personal life struggles.'
If this were done to me, I'd be furious.
Coming from senior managment, it would further make me feel that they were, in effect, delivering this message, too,
'Never mind the options and terrific pay we, your senior management, receive as compensation. You should feel personally challenged to meet the unreasonable goals we've set for you with too-little support, mediocre strategies, and/or products and/or services with no competitive advantage. Never mind the promotion of politically-motivated colleagues above you, or the niggardly compensation increases we give you. Instead, please try to place yourself in the position of this person with a genuine, unavoidable personal handicap, learn from her or his life story, and then treat your employment situation with the same kind of gravity as this person handled her or his life.'
How cynical is that?
Hopefully, this is one of those trends, like "team building," which turn out to be just a passing fad. It seems to shift the focus for corporate performance from a realistic appraisal of a company's or business unit's situation, goals, resources, etc., to a campaign that simply instructs employees to forget all of that, and behave like the only thing that matters is personal motivation.
It reminds me of the real activities of the Soviet Army's NKVD squads in WWII. They would liberally dispense vodka to the infantry troops the night before a mass human wave attack upon German positions. Sober troops might think twice about attacking fortified lines with light infantry arms, but drunken troops could be motivated to make the ultimate sacrifice for the Motherland.
Unfortunately, corporate employment isn't combat, and it's also not a fight for one's homeland. Instead, using handicapped motivational speakers to inspire employees who have been, over the past decade, down-sized, right-sized, sigma-sixed, etc., and had their compensation squeezed as well, is misplacing the responsibility for corporate performance.
If a company is doing well, one would hope these tricks would be unnecessary. If it's doing poorly, should the CEO and his management team not analyze their strategic situation, competitive position, etc, before simply assuming the problem is insufficiently motivated shock troops?
Is it really necessary, as the WSJ piece mentions in one example, to 'inspire' internal finance managers by one handicapped person's personal story of overcoming adversity? How much adversity can there be in a finance function?
When I read this story, I was reminded of a comment made to me by my very first manager at AT&T, over twenty years ago,
"Sometimes I don't know whether to laugh or cry. But I laugh, because it hurts less than crying."
After reading this article, I found myself laughing, because it hurt less. And resolving to read Dilbert, which was motivated by this sort of corporate managerial nonsense, a lot more often.
Friday, October 13, 2006


Thursday, October 12, 2006
EBay and China Again: More Troubling Signs
The Wall Street Journal's Money and Investing section carried a piece about EBay's recent troubles in China. That is to say, it was an 'investing' story, not a 'strategy' story. However, it reminded me of a similar story about Amazon in the WSJ in August, about which I wrote a piece, here.
EBay is now in trouble in both China and Korea. Although the EBay spokesman attempts to paint a rosy picture, in this case, I think one should trust the numbers, not the PR prouncements.
For instance, according to the Journal piece, EBay's market share in China is 29%, a distant second to market leader TaoBao, with 67%. And the former's listings growth has slowed from 300% year-to-year, to a much lower 127% in the recent period.
Here's EBay's spin on the Asian situation. Regarding China, they are “very happy” with business there and are “well positioned” to succeed there over a 5-10 years period. Their spokesman, Mr. Durzy, further says that their Chinese site “is comparable- if not better than- rivals’ sites, because eBay offers communications tools such as Skype and PayPal.” Quotes are of the WSJ article.
The reason for the piece is the 30% decline in EBay's stock price this year, and longer-term decline as well.
In this case, I'd go with the market share and market price numbers. EBay is clearly in trouble in both China and Korea, and the anemic growth in those markets has affected its total returns to shareholders.
As I discussed this piece today over lunch with my partner, he asked if I had reflected this in my recent piece on female CEOs. I had not, since I was focusing that post on Carol Bartz.
However, upon further reflection of EBay's performance since it went public, and this WSJ article, I am beginning to wonder if EBay's early total return performance was not almost pre-ordained, given the environment of that era. It was a new issue, in a hot product/market space. Could it really have taken all that much to simply maintain the early momentum when online auction sites were so new?
Well, we shall soon see. Because it looks like it's crunch time for Meg Whitman and her team now.
I used ebay. I’ve never used skype. I think ebay is probably in serious trouble, because what they offer, and think matters, does not matter to customers.
Wednesday, October 11, 2006
Female CEOs: The Unheralded Carol Bartz of Autodesk
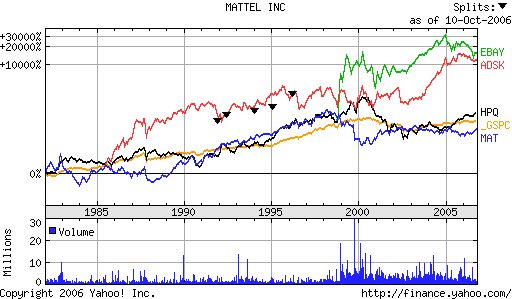
Alan Murray of the Wall Street Journal wrote a fine article in today's edition, discussing the behaviors of HP's two most recent, most senior female officers, Carly Fiorina and Patty Dunn.
His point is that both women did their gender a disservice by ducking for cover and choosing to be victims in their individual stories of strife and loss at the computer and printer manufacturing company.
Mr. Murray is, I think, entirely correct in noting that both women protest that nothing was their fault, and that they bore no responsibility for anything that happened to them. And HP certainly has suffered for their actions, inactions, and failures while they were affiliated with it.
What I don't understand is why more attention isn't showered on at least two more successful and stable female CEOs: Meg Whitman of eBay, and Carol Bartz of Autodesk.
The chart at the top of this piece displays the stock price performances of four companies that have been led by women for at least several years. Jill Barad was CEO at Mattel during 1997-2000. Meg Whitman has headed eBay since 1998, while Carly Fiorina was CEO of HP during the period 1999-2005. Carol Bartz has been CEO of Autodesk since 1992, only stepping down from active leadership of the firm earlier this year.
While Barad and Fiorina destroyed value at their companies during their tenure, Whitman and Bartz have had longer tenures and presided over significant wealth creation for their shareholders. Although Whitman's eBay has slumped recently, it still has an enviable record during her tenure, roughly equaling that of Autodesk for the period in which eBay has been public.
In my opinion, however, Carol Bartz is the class of the class. She has created value consistently at Autodesk for 14 years, with the exception of some rough years in the late '90s. Even then, however, the company tended to tread water, and not lose substantial value for long time periods.
I think it does seem unfair that Bartz is not accorded the type of press that GE's Jack Welch received for his long-term performance. Blogger is not cooperating with the uploading of a price chart comparing GE and Autodesk over many years, but suffice to say, Bartz looks as good as Welch, when the two companies' performances are compared for the years in which they both were CEOs of their respective companies.
If Bartz is being ignored because of her gender, then that's even more bad news to add to Alan Murray's contentions. Not only do poorly performing female CEOs, like Jill Barad, get spotlighted, but the rare excellent performers, like Bartz, are conveniently forgotten.
Personally, I believe that good leaders of either gender are more like each other, than they are like non-leaders of their own gender. Bartz is a great CEO who happens to be a woman, not vice versa. In this case, I'd like to learn more about how Bartz ran Autodesk so well in a tough, single market business. Welch had the luxury of multiple businesses driving GE. I think we all lose a lot when successful CEOs like Carol Bartz go unstudied and unrecognized.
Tuesday, October 10, 2006
YouTube & Google
Well, it's official. Does any business pundit, media personality, or publication not have an opinion on this recent tie-up?
Probably not. So here's mine.
I think the most unique value I can add to assess Google's purchase, for $1.65B of stock, of YouTube, is to suggest that the value to Google of YouTube is a binary proposition. Either the online ad business is stable and continuing to grow, does not collapse as Net Bubble II, and YouTube is a smart move, or, we are living amidst the second internet bubble, it will "pop," and Google's purchase of a profitless online company with virtually no proprietary content, will look silly.
I doubt the result will be anything in between.
The CNBC pundits, and their guests, pretty much shake out into the two camps you'd expect.
On one hand, you have those who (correctly, I believe) see this as Google paying $1.65B to deny Microsoft, Amazon, Yahoo, News Corp, TimeWarner, Comcast, et.al., the hottest, largest video content destination in the online world at present.
Given Google's current $130B market capitalization, YouTube cost barely over 1% of their value. And latter's stock rose $4 yesterday, on the acquisition news, or roughly $1.2B. Yes, if you're waggish, you can say, "look, the damn thing almost paid for itself in one day!"
But, seriously, if we are all drinking the Kool-Aid, this deal made sense. It is Google's wise use of its almost untouchable market value to pay up for a unique online asset, and also deny it to any potential competitor. Very shrewd. Very aggressive, using one of their unique advantages, the ability to fund large acquisitions, and outspend, outmaneuver, any would-be challengers to Google's ability to blanket everything online with ads.
In a way, it meshes with my thoughts about Google from last year, as well as earlier this summer, found here. Basically, Google's leaders know they can no longer re-Google their own firm. They are simply already to large. But they do own market value. And they have made so much money, that they can literally afford to begin to spread that largesse around, forward, to new challengers who might unravel Google's carefully-sewn blanketing of the online market for ads and searches. By not being too greedy, and seeing their incredible market cap as a piggy bank sort of found in the brush, to be shared with deserving other innovators, Google may well extend and expand its market dominance for some time to come.
On the other hand, many analysts note that YouTube has no profits. It is a total hedge purchase by Google, and will never justify its price.
As I noted up in the early paragraphs of this post, I think it's an either/or sort of situation. Either Google, in general, is valuable, and, thus, by extension, so is YouTube. Or it's a blip, another AOL, and when it dissolves in one, huge online bubble-burst, YouTube will look like a foolish move.
By the way, in that regard, consider this, if you will. YouTube has fewer than 70 employees. Suppose the two founders only keep half of the $1.65B in stock, and give the rest, net of Sequoia Capital's 30%, to their employees. With $825MM left, Google's value could plummet by 99%, and the founders would still enjoy a payoff of $8.25MM, or over $4MM apiece. Is that so bad for a year's hard work and a little imagination?
However, back to the pessimistic view. Back in the late '90s, when clicks were supposed to replace bricks (and mortar), the items in question were physical goods. Online pet stores, etc, could not, in the end, sustain sufficient sales volumes to justify their market values.
Now, however, the material in question is entertainment. Digital entertainment, to be specific. It's all over the place, so finding one place where millions of people concentrate to find and view the digital video entertainment is extremely valuable.
Nevermind CNBC's Bob Griffith's inane question, something like 'couldn't I start a video website with $1.65B?' Sure he could, and so could I, and so could you.
But it wouldn't be YouTube, now, would it? It might look the same, but if people don't put up their video content, you're just not "there."
True, YouTube owns virtually none of the content it hosts. Now...wait a minute...let me think.... That reminds me of....eBay! They don't own the merchandise they intermediate, either, do they? Their best days might be over, but they, too, had a good run at the top, when online auction was a fresh business model.
I think the bottom line this time is that the acquisition of YouTube by Google, in the competitive context of today's online digital content business, is a cheap defensive tactic, and perhaps a profitable offensive strategy, as well. Old media is going to have to continue to use new media as its distribution channel onto the internet. They just don't have the mindset to invent or grow their own YouTube, Bob Griffith's opinion notwithstanding.
Monday, October 09, 2006
GM & Nissan's Failed Alliance Talks: Wagoner Wins Round 1
This weekend saw the further development of two major business news stories. One culminated this afternoon, but the other will probably run for months, if not years.
On Friday, Jerry York, Kirk Kerkorian's agent on the GM board, announced his resignation from said position. Round one has clearly gone to Wagoner, but I suspect, in the end, that it will be a pyrrhic victory.
Now that York has left GM's board, Kerkorian has withdrawn his offer/plan to raise his stake in the company. Upon learning that, investors sent GM's shares down sharply Friday afternoon.
At this point, many are speculating on Kerkorian's next moves, and the timing thereof. CNBC's official "car guy," Phil Lebeau, preaches that Kerkorian will now sit back and wait, as he and York did with Chrysler.
However, that was then. "Now" is different. I don't think so much of the American auto sector was in such dire straits back then, as it is now. Ford, and even GM, probably don't have as much time as Chrysler did, with guaranteed funding, to regain their health and competitive strength.
My own guess is that Kerkorian, who, in my memory, has not lost money on a major investment since at least 1979, will move to take over the GM board in the spring, and then move quickly. Personally, I think he and York plan to emulate the late, great, J.P. Morgan, and single-handedly restructure the remaining US auto makers into one firm, allied with Nissan/Renault.
One thing Kerkorian and York are not is sentimental. They realize that, regardless of the brand names, Ford and GM essentially still, for a little while longer, have some residual market share and loyalty on which to build. This needs to be cut loose from moronic, myopic management, and inefficient production modes, in order to be served by the better management of Nissan. I think the two takeover veterans have more than just GM in their sights. After they unseat Wagoner, they can approach Ford, regardless of whether it has joined up with Ghosn and Nissan.
I would not bet on this, yet, per se. But neither would I be at all surprised. Ford clearly has to have a partner now. Kerkorian wants Ghosn to manage GM's assets. If all three, or four, with Renault, can play, so much the better. Kerkorian and York understand that scale and depth of talent will be needed to prosper, let alone survive, competing with Toyota in the years ahead.
Friday's events did not surprise me. It just demonstrates how insecure and small-minded Rick Wagoner really is. And how dismissive he is of, and insensitive to, the needs and obligations of his shareholders. These days, that is probably a terminal mistake for a CEO to make, especially on the scale Wagoner has made it.
Friday, October 06, 2006
Patricia Dunn's "In"credible Testimony
Here's the YouTube video clip of a part of HP's former Chairwoman, Patty Dunn's, testimony before Congress a few weeks ago.
I love how incredulous Greg Walden, the Rep. from Oregon, is, when Dunn asserts that she thought anyone can just call up the local phone company, request, and receive, anybody else's detailed message unit call information.
It is truly hard to believe that someone who could qualify as the Chairwoman of a major US company would be this gullible or naive.
The Wall Street Journal ran a piece yesterday discussing how Dunn's testimony has already "boxed her in," regarding her recent felony indictment over this case, in California. With this video available, what judge or jury is going to believe Dunn wasn't either lying under Congressional oath, or is lying in court if she testifies and reaffirms her belief about the availability of such private, detailed phone records?
Let's not even get into what happens if she changes her sworn testimony in subsequent legal proceedings.
It's just a very sad commentary on the caliber of senior leadership in large US companies, that Patty Dunn is either without scruples, and lying to cover up her knowledge of the use of questionable tactics by HP to find the board-level leaks, or she is truly so naive as to think your and my detailed phone records can be had for the price of a local call to our landline phone service provider.
Thursday, October 05, 2006
Apple's iPod & iTunes Overhauls: Schumpeter Would Be Proud
Walt Mossberg of the Wall Street Journal reviewed the new lineup of Apple's iProducts and Services in Wednesday's edition of the paper. He notes that, with the advent of Microsoft's Zune, and RealNetwork's Rhapsody, Apple has completely overhauled it's offerings.
Even if I did not own Apple's stock in my strategy's portfolio, I would appreciate the company's very aggressive product/market management.
Given the quickly-shifting sands of competition in this arena, Joseph Schumpeter would be very proud to see how Apple has rapidly cannibalized its own product line, in order to meet new competitive threats.
For instance, they have redesigned the low-end Shuffle, and pared the number of now mid-range offerings of the original iPod, and eliminated the iPod Mini altogether. Through a combination of pricing and product repositioning, the company has made room for new, higher-functionality entries in its iPod line.
It has also upgraded iTunes, the online entertainment content management system which is the companion to its iPod line, in time for the entry of the two new competitors' products.
The vagaries of consumer tastes may result in the loss of significant market share for Apple's products. Or it may result in the firm's continued dominance of the product/market. Either way, Apple won't lose share and growth because it stood still, became complacent, or milked the business.
It's a pleasure to see a leading company, like Apple, do such an admirable job in a key business, such as digital entertainment content, of moving ahead to change the competitive environment while it still can significantly effect that environment, rather than rest, and let new competitors control the terms on which competition will play out over the next few years.
New Pension Liability Effects: Bracing for Negative Shareholders Equity
In a story with potentially large effects on the financial services sector, the FASB recently ruled to require the charging of pension obligations directly to equity. This is, according to observers of the situation, going to result in some major companies having negative equity.
To read more about the changes, you can go here. To quote from that site's article,
"That means huge liabilities could suddenly drop like a bomb onto balance sheets, putting any deficits squarely in the public view and possibly throwing some lending agreements into question because it may lead to sharp drops in corporate net worth.
Figuring out if any maneuvering is going on won't be an easy task. Investors will have to closely watch companies' assumptions for such things as health care and wage inflation that are used to determine the costs of defined benefit plans, which promise retirees a monthly check and often medical coverage.
For years, companies have gotten off easy by agreeing to such benefits without having to immediately set aside ample assets to cover them. Standard & Poor's estimates that the companies in its benchmark index offering such benefits held assets worth only $1.409 trillion in 2005 to cover $1.870 trillion in pension and other retiree-benefit obligations, resulting in a record deficit of $461 billion."
A Reuters article further noted,
"Investors may see some of the biggest changes in the balance sheets of companies like General Motors Corp., Ford Motor Co., Goodyear Tire & Rubber Co. and Exxon Mobil Corp., which maintain some of the largest U.S. pension and other post-retirement benefit plans.
Automakers, airlines, steelmakers and other manufacturing companies are likely to face the biggest obligations because of histories with unions and legacy costs, according to accounting analysts at Bear Stearns."
Let me note that all of this harks back to one of my earliest posts, from last September, about the long-lasting effects of the mutually-flawed bargains struck beginning 50+ years ago between American corporate and labor union leaders.
If the companies in question see their stock prices change materially from this FASB decision, then it suggests that the analyst corps was never doing an adequate job of understanding the true financial positions of these companies. If, on the other hand, the stock prices do not change materially, then it suggests that the existing measures weren't really all that useful to begin with, because they were in error, yet still in cited.
Analysts can't have it both ways, can they?
Late last week on CNBC, in an interview with an equity analyst, the first effect mentioned was that of screwing up traditional stock evaluation measures.
My own early work on valuation taught me about the inadequacy of measures such as Price/Earnings and Market/Book ratios, and other point-in-time balance sheet or income statement measures.
Now, it appears that those measures will have a permanently disjointed history that cannot be smoothed or calculated away. Furthermore, their future behaviors may now result in calculation-inhibiting values. This was always the case with using earnings, which can dip below zero, making growth calculations effectively insoluble. Now, even some balance sheet staples like basic Shareholder Equity will be unusable.
This is why I use simpler scalers with a time dimension in my analysis of companies' performances. Specifically, revenue growth and total return. No ratios.
I learned years ago, grappling with the more conventional ratios and snapshot measures, that they are subject to incomprehensible results, and, sometimes, literally incalculable ones.
By focusing on the quantitative expressions of a company's ability to consistently acquire and retain customers, at appropriate prices for the products and services they sell, i.e., revenue growth, and matching these values with investors' judgments on the adequacy of the resulting financial results, i.e., consistently superior total returns, my methods free me from the risk of accounting distortions.
Rick Santelli of CNBC Gets Even Smarter: The Impact of Derivatives On Spreads
This morning, as I was reading the Wall Street Journal and watching CNBC's Squawkbox, Rick Santelli was debating the recent confusion in the debt markets regarding inflation, interest rates, and economic growth.
Joining the debate were Joe Kernan, Steve Leisman, the show's under-educated 'senior economic reporter,' and a guest host.
Kernan is always a level-headed, sensible, and smart commentator. Leisman is typically self-impressed, and blind to his own lack of basic economic education.
Santelli, the network's Chicago-based reporter from the options pits at the CBOT, is among the most intelligent, informed, educated, and plain-spoken bond market reporters that I have ever seen on television. Bar none.
This morning, Rick gave the most lucid example I've ever heard of how the existence of credit derivatives affects, and has permanently affected, bond market spreads. He explained how, when one can buy protection for the drop in value of a bond, it necessarily puts upward pressure on the price, because the lowest value it can now attain is much higher than it otherwise would be.
He then went on to note that many people have missed this important development in the bond markets. And that even Fed officials might be misinterpreting the meaning of the now-closer spread relationships, versus their historic wider margins.
Leisman asked, to paraphrase,
"can it now be that, and I don't really understand this, that the bond markets are existing on one plane, setting rates, and the Fed is on another plane, or level, with its rate setting views?"
Santelli responded that, yes, the two might not agree contemporaneously, but in time, would gravitate to the bond market's view. Kernan laughed, and Leisman sort of looked puzzled, which was to be expected. But Santelli clearly meant that, over time, the closer spreads for yields between various debt instruments are here to stay, and the Fed will have to adjust to this. The money markets will overwhelm the Fed's interest rate manipulations every time, until the Fed takes the market's judgments into account.
What really impressed me is Santelli's matter-of-fact command of bond market reality, and its impact on economic theories that others believe are governing that reality.
He is one CNBC correspondent who I could watch all day, and probably never feel I'd learned everything I could by listening to him.
Wednesday, October 04, 2006
Monday on CNBC: The Conflicted Trader
I saw interviews with two 'traders' on CNBC Monday morning which yielded diametrically opposite views
First, Art Cashen, the florid-looking mossback from UBS, said that interest rates and Bernanke govern the market now. Period. Nothing else mattered.
Then a trader for another large broker was similarly questioned. He waffled on every question, giving no solid opinions whatsoever, except to say 'it all comes down to earnings'
So, there you have it. It's all about interest rates. Well, except when it's all about earnings.
Gee- thanks guys. I didn't think about either of these.
Once again, this anecdote of the conflicted floor traders shows how inane talking to brokers is. For the most part, they trade for clients- insitutional managers, other houses, and large private accounts. For the most part, all the brokers really 'know' is instantaneous order behavior.
Of course, they like to personify the 'market' because it adds presumed value and glamor to a business going totally electronic. Seriously, how can "the market" really know or care about the level of a single composit index, and truly behave differently as that level's old, nominally-valued maximum is exceeded?
One thing the piece did demonstrate- it takes different views to make a market, and even interviewing only two brokers already did that.
Tuesday, October 03, 2006
Professional Fund Manager's Erratic Behaviors
Saturday's Wall Street Journal featured an article about a Lehman fund manager, Jon Brorson, fretting over the recently monthly performances of the market indices, his fund, and what can be gleaned of US economic activity.
The article states, in part,
"Mr. Brorson's worries served him in May. Then, he shifted toward "defensive" companies whose sales tend to hold up in all kinds of economies, such as drug makers, food producers and electric utilities. His May move was gutsy -- and right. The Dow got to within 81 points of its record and then fell 8% into July.....Now, as it rises, he's fighting the trend again. .... His travails over the past two months show just how hard it is even for dedicated pros to call the turns. It's especially hard at times like these when investors are debating whether a shifting economy will change stocks' direction."
I see in this echoes of 'the broad market has it wrong' attitude, as he holds and waits. In fact, I can identify with the sentiment.
However, I also note how Brorson makes snap calls on fuzzy, unclear economic information. In effect, betting on the come. Then people judge his guess for the month.
If this is really the stock in trade of the average fund manager, I wonder how any of them develop consistent track records.
Wait! They don't, for the most part! The number of public fund managers who consistently beat the S&P is incredibly small. Forget doing it every year- even most years, it's unattainable on a consistent basis. Maybe this monthly micro-managing suggests why that is the case?
I would imagine that the kind of guesswork, based upon shifting, often wrong economic insights and confusing data, cannot be sustained for more than, say, a year. That is, if it is just a string of lucky guesses.
For instance, recently, many investors seemed to be worried that softening home prices will drag the economy into recession. However, just a few days ago, the Wall Street Journal carried an article by one of its reporters, Greg Ip, which noted the following,
"The overwhelming majority of mortgage debt and home-equity loans are held by Americans in the upper half of the income range. Households in the top 10% of income hold 42% of the value of home-equity lines of credit."
Thus, much of the risk of real-estate-related bad debt is overstated. This is the type of economic information that seems to go unnoticed or misinterpreted.
It's one of the reasons I don't buy and sell portfolio positions every month. Even supposedly firm economic data can mislead, e.g., the infamous, but nonexistent, spring 2005 "softening." Now, it is the 'recession,' or imminent 'soft landing,' in the face of continued economic data suggesting continued healthy growth.
Jon Brorson's concerns are ones I share. But I just don't see how changing one's strategy and spontaneously attempting to take advantage of a short-term economic will o'the wisp can lead to consistently superior total return performance over the long term.
Monday, October 02, 2006
The Rush By "Old Media" To Offer Online Video
Recently, I wrote, here, about Apple's iTV announcement, and its probably effect on cable TV providers going forward. Subsequently, I wrote about the recent Goldman Sachs media conference, here, discussing the rush of existing content library owners to dump....er......make deals for the distribution of their libraries to any and all digital channels while they still have value.
Then, last week, the Wall Street Journal ran an article in the back pages of the second section discussing the rush by all sorts of companies to offer online digital video now. The piece was entitled, "As Internet TV Gains Popularity, Cable Firms Bulk Up Offerings."
A nice idea, but a little late, as indicated by this line in the article,
"Video Web sites now draw users in numbers that rival those of cable or satellite companies. YouTube, the country's No. 1 online-video site, had more than 34 million unique visitors in August, according to Nielsen/NetRatings. MySpace was second with 17.9 million unique visitors. In comparison, Comcast, the country's largest cable company, has 24 million subscribers, and DirectTV, the largest satellite-TV provider that is owned by News Corp., has 15.5 million U.S. subscribers."
So the hi-speed access that came along with cable-TV has now grown to undercut the latter by allowing free, independent production and distribution of video content which is growing to rival the paid content on the original cable pay-TV systems.
If this situation doesn't demonstrate Schumpeter's visions of creative destruction at the extreme, where a firm's own success creates the undercurrent that hollows out its competitive position's strength, what does?
In this case, though, I think cable companies are myopic. Consider this closing quote from the WSJ article. The source of the quote, Steve Burke, CEO of Comcast, said, in reference to his own idea of
"creating an extensive viewing guide that would aggregate Comcast's TV schedule with online clips and video-on-demand options, giving people a mega portal for one-stop viewing shopping,"
"We're not alone in our aspiration to be that one place."
Now, I think that's the problem with old media's viewpoint.
There is, in my opinion, no "one place."
YouTube is 'one place,' alright, but hardly the "one place." It may not even be king of the hill in another year. That, of course, is the risk a potential acquirer will have to take.
The essential concept of internet-based, free video content sites almost guarantees no single site will be "the" site. Wherever a critical mass of video content may be gathered and offered, a viable site may be created. The company that has really missed the boat on this is, of course, Amazon.
Amazon, with its broad array of storefronts for independent book sellers/shippers, could easily have offered the same type of home to indie video producers, becoming the internet's video 'general store.'
Not anymore. That opportunity is gone, and, with it, Amazon's ability to capture anything beyond "me too" traffic and revenues.
It's simply incomprehensible to me how, having seen the future, a la YouTube, the CEO of Comcast still doesn't "get it," and is throwing money at an attempt to create, much further down the road, an omnibus, ostensibly partially-paid video site, to challenge a free one. Between Comcast and TimeWarner, one wonders if any old media companies will be worth more than a fraction of their current market values in a few year's time.
Kerkorian's Bold GM Gambit
You can't say Kirk Kerkorian isn't a bold poker player.
Friday's Wall Street Journal details his bid to buy an additional six million shares of GM, and plans to perhaps buy another six million. These stakes, if purchased, according to the Journal article, would make Kerkorian the second-largest GM shareholder, with a 12% position.
Although it looked like a losing position this summer, Kerkorian's original investment has now gained about 14%, thanks to GM's recent stock price rebound, on the basis of cutting deals with its unions over buyouts and layoffs.
The Journal piece characterizes the GM situation as becoming a sort of show down between CEO Rick Wagoner, who wants to slowly rebuild the company, if there's time, and Kerkorian, who wants a much faster, thorough restructuring, including a three-way alliance between GM, Renault and Nissan.
My recent thoughts on the GM situation can be found here. Suffice to say, I don't think GM is a viable performer, in terms of consistently superior total returns, without some sort of outside help or alliance.
Kerkorian is certainly playing a bold game, though. He could take his winnings off the table at this point, and have outperformed the S&P for the period. However, he chose instead to double-up, indicating he's after a much bigger gain, and prepared to invest the time and effort to secure it.
By moving to take a larger position, the betting is that, in the language of his SEC filing, "there should be strong GM board involvement" in assessing potential alliances. Meaning Kerkorian wants to outmaneuver Wagoner's internal attempts to scuttle the alliance, and get it approved by the board, out of Wagoner's direct reach and control.
It's hard to guess what the outcome will be in this case. There are so many options for Kerkorian, and the rest of the GM board. However, I don't recall Kerkorian leaving a situation like this with a loss. If he's prepared to add to his GM stake, then he must feel very confident that he can force the alliance, and reap the gains he expects from a resultant higher GM stock price.
In a sense, he can't lose, in the long term. If Wagoner's alleged "turnaround" really is more than short-term cost cutting, then the shares will rise, and Kerkorian makes more money. If Wagoner is wrong, Kerkorian, as the second-largest shareholder, through his employee, Jerry York, can probably force Wagoner's departure, and proceed with an alliance for GM. The only question at that point is whether or not Ghosn's Nissan is still open to the alliance, or has already tied up with Ford.
Could it be that Ghosn, watching from outside, could now hold off from a Ford alliance, and simply wait Wagoner out, knowing that Kerkorian will eagerly come calling, with less onerous terms than Wagoner has demanded?
It continues to be a phenomenonally interesting end-game for GM and Kerkorian, as the time to demonstrate a believable, lasting reversal of GM's fortunes grows shorter.
Friday, September 29, 2006
More on the Current Dow Frenzy and "Cute" Tickers
Today I have two Wall Street-oriented topics to address. One involves the recent fervor over whether the Dow will post a new all-time high. The other is about a recent article in the Wall Street Journal regarding 'catchy' ticker symbols.
My puzzlement over the Dow level revolves around the mistaken impression by so many analysts, market observers and pundits, that the precise level of a composite index matters over so long a time, to individual investors.
Among the more bone-headed, indefensible comments uttered in the last few days is that, now that the Dow may rise above its prior high, some unnamed investors, who apparently had their prior holdings frozen in time, will promptly unload all of their holdings, to finally book a gain.
Run that one by me again, please? Just because the Dow hasn't risen above its prior high of some 5-6 years ago has no relationship with how each individual equity, or even mutual funds, performed. Let alone what investors did with those positions.
Is it reasonable to believe that most investors have been hanging onto the same portfolio they owned 5 years ago? That's the only way that a new Dow high would actually unleash a flood of sell orders to finally rescue distressed equities that were underwater all of this time.
It just seems too absurdly foolish for anyone to think this way, but Mark Hanes and several others articulated just that view in the past few days.
A composite index is, admittedly, a function of its component parts. In the case of the Dow, that's only 30 industrials. So what about, say, the other 470 that are part of the S&P500 (I haven't checked, but I'm reasonably sure the Dow is a proper subset of the S&P), let alone the other 3000+ equities with liquidity in the market these days?
That's why I think the exact level of the Dow or S&P is mostly moot. Rather, the rate of change of an index is more useful in suggesting how investors may react, as they view a steady, or unsteady, progression of monthly returns of "the market," as narrowly represented by the Dow, or, more broadly, by the S&P500.
The other financial topic which caught my eye this week appeared in yesterday's WSJ. Entitled, "Does Stock by Any Other Name Smell as Sweet," it cited 'research' purporting that certain stock tickers, simply by virtue of their 'name,' cause, or are associated with, higher average returns, than other stock tickers.
The tickers in question, such as YUM, HOG, BID, and EYE, are thought to trigger more awareness in investors' minds. According to the article, researchers Adam Aiter and Daniel Oppenheimer claim to have found that pronounceable tickers which were bought and held on their first day of trading earned $85.35 more, on a $1,000 portfolio, than other tickers. Further, Pomona College's Gary Smith alleges that portfolios formed from "clever" tickers, from 1984 to 2004, had a return of 23.6%, against 12.3% for a 'hypothetical index of all NYSE and Nasdaq stocks.'
In neither case does the article mention average returns, or standard deviations, or the significance level of the stated performance differences.
What's more, both 'studies' suffer from a more glaring error. By using only one predictive variable, and measuring the difference in returns, or stock prices, they implicitly assign all performance differences, or their variances, to the stock ticker 'pronounceability' or 'cleverness' variable.
Does anyone truly believe this? Would you drop all of your other equity strategies right now, and invest in one of these two?
More reasonable would be a study in which the authors included a set of commonly-used predictive variables, and the stock ticker variable. Then the variance in performance of stocks, or portfolios, could be allocated to each predictive variable, or the predictive variables themselves could be factor analyzed, to assess shared association.
Either, or both, of these approaches would yield more believable, defensible, and useful conclusions to the question of whether the 'cuteness' of a stock ticker actually adds to its return potential.
It's disappointing to me that the Journal even printed this piece, let alone without much in the way of critical commentary on them. It did include one remark by an obscure finance professor from the University of Utah, who did at least suggest controlling for, rather than actually assessing the predictive power of, other predictive variables.
After all that, the article concludes by noting that the researchers themselves do not "recommend that people make trading decisions based on our findings."
What, then, was the point of this piece? Just entertainment? That would seem to be the Personal Section, would it not?
Have a great weekend!
Thursday, September 28, 2006
Today's Dow Frenzy

Dow closed 33.74 points shy of a record yesterday.
Now, every financial media personality is crowing that a new Dow high is within reach. As if that really matters.
CNBC's resident (endlessly) talking head, Bob Pisani, went over the top, explaining that this new high is crucial for investor confidence.
Well, I think he's only very partially right. This year is already seeing a positive Dow and S&P. And, by the way, it's the S&P which has the largest fund presence, so that is the index which would really matter. But it is not anywhere near as close to an all-time high as the Dow is.
It's not clear that a new high, whether on a close, or intra-day, really matters as much as steady, quarterly positive returns for the index.
But, leaving these behavioral questions aside, I see that, as usual, the on-air media is back to personifying "the market." I wrote about this last June, here.
This morning, CNBC rolled out the moss-backed Art Cashen, a floor-based executive of one of the Street's brokerage firms, and caught NYSE CEO John Thain in passing, to solicit comments calculated to heighten the drama of whether or not a new intra-day Dow high would be made.
If anything demonstrates to what degree media coverage of the capital markets is more about entertainment than reasoned assistance to investors, today's sorry spectacle would be it.
More Automotive Developments: Toyota, GM and Nissan
The automotive sector is once again in the news this week.
A Wall Street Journal article earlier this week reported on the self-parking Lexus LS460. Toyota, its developer, demonstrated this amazing technology in a parking garage 'within sight of Ford's Dearborn headquarters'.
The story made, in my opinion, several key points.
One was the story of the crystal headlight glass. Evoking the attention to detail that was involved in the legendary development, over 20 years ago, of the original Sony Walkman portable cassette player, the car's chief engineer painstakingly redesigned the headlights to more accurately resemble fine crystal. To do so, he actually had a crystal headlight made, then sent this to the supplier in order to be sure the latter had the exact "look" desired, from which to manufacture the production-grade headlights for actual assembly.
Second, Toyota is now enjoying, and employing, the accruing benefits of success, including internal funding for growth. The article mentions many measures of Toyota's recent success: profits, size, hiring plans, etc. Suffice to say, their attention to consumer tastes, desires, and the fulfillment of those, has driven it past Ford and GM in terms of profitability and recent growth rates.
It should have. That's how markets are supposed to work.
The Journal story's ending comment is noteworthy. It comments on Toyota's continuing 'inferiority complex.'
To quote the piece, "Unlike baseball pennant races, contests for sales and dominance in the (auto) industry never end."
That's entirely right. Joseph Schumpeter taught us that "the race" never ends- anywhere, anytime. Thus my search for consistently superior performance, which, in a well-run, well-positioned company, can be the resulting hallmark of this healthy inferiority complex of Toyota's.
Next, we have yesterday's and today's coverage of the Paris alliance talks between Carlos Ghosn of Nissan, and Rick Wagoner of GM.
Between the WSJ piece yesterday, and this morning's continuing coverage on CNBC, it's evident that, for better or for worse, Rick Wagoner is rolling the dice now, with all of GM's shareholders' money on the line.
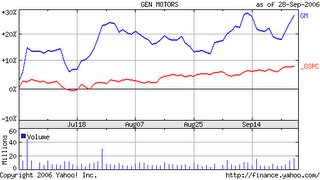 Personally, I find it laughable that anyone can call this year, based upon such brief and one-off events, a "turnaround" for GM. The chart on the left is what traders, analysts, and CNBC talking heads are all excited about right now. Over the past three and six months, GM's stock price is easily outperforming that of the S&P500.
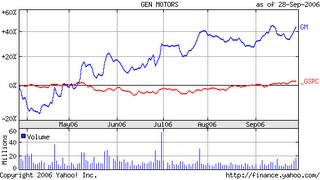 This, we are told, is the result of investors believing that GM is now in turnaround mode, and will return to automotive dominance imminently.
Not so fast....
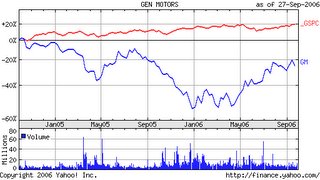 Here's what the charts look like for the past one and two years. Completely different, aren't they? GM is flat for the past twelve months, and down for the past two years.
Now I read, and hear, that GM's CEO is feeling so confident of his brief, one-time trick of shedding some labor costs, that he's decided to demand tribute from Carlos Ghosn and Nissan/Renault, should the two form an alliance. According to the Journal, GM wants a "multibillion-dollar payment" from Nissan and Renault.
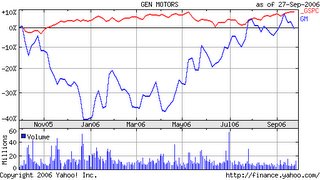 Wagoner is really a clever guy- give him that. He doesn't want this alliance. It was forced upon him by Jerry York and Kirk Kerkorian, his newest and most irksome board member and shareowner. How to evade the alliance? Loudly proclaim that a non-sales, non-customer-based, one-time financial cost reduction is, in reality, the much-heralded "turnaround," and then use that "fact" in order to make an unacceptable demand as a condition of any alliance with Nissan and Renault.
Yesterday's Wall Street Journal front-page piece, and this morning's coverage of the situation by CNBC, both cast doubt on the likelihood of any alliance being consummated. The most recent word is that the two parties have agreed to go away and reconsider terms, etc, for the weeks remaining in their 90-day alliance evaluation period which ends on October 15.
So Rick Wagoner is now "all in" with his shareholders' money. The Nissan/Renault alliance probably marks the last refueling stop on GM's uncertain road to recovery. If Wagoner successfully derails the alliance, then his shareholders better pray he has more up his sleeve than more job and cost cuts. And maybe Wagoner better check his own liability insurance for coverage from gigantic shareholder lawsuits for fiduciary breach.
Back to Toyota, though. Because that company figures in the GM alliance talks, too. According to Ghosn, Toyota is the company to beat, and he wants this alliance in order to have a decent chance of surviving that juggernaut's impending rise to global automotive dominance. Being a game of momentum and scale, Ghosn realizes that his companies have to be able to stay the course with enough capacity and design capability to match the Japanese giant, stride for stride, going forward.
Clearly, Ghosn isn't sure he has enough resources to do it presently. But GM may be demanding too high a price, and for an alliance that Ghosn doesn't even seem, based on his comments this summer, will even work effectively.
Once again, we see Schumpeter's theories in action. Wagoner is playing in his little Detroit fishbowl, and just wants Nissan/Renault, and Ghosn, to go away. Maybe to Dearborn, maybe back to Tennessee. Yet, GM can't really demonstrate a full-fledged, customer-based resurgence in its own fortunes at this time, nor, really, a very highly-probable scenario in the near future, either.
Ghosn, on the other hand, is running scared. Which is a good thing. He's competent, tough, and now, scared. Just like Toyota, his main adversary for the coming, pre-Chinese automotive sector rise, decade. That kind of healthy fear transforms companies into nimble, fleet customer-needs-serving, consistently superior total return performers. Not always, but it helps.
So now we have the lay of the land, in the microcosm of two of this week's automotive sector stories. Toyota demonstrates why it's the company to fear in the sector. Nissan's Ghosn demonstrates why he's the best bet for challenging Toyota globally. GM's Wagoner demonstrates that he's more interested in being left alone, to the potential detriment of his shareholders. And Ford is desperately hoping that maybe Ghosn will come back to call on them, and let them at least fight on the number two team, rather than alone, against Toyota.
A Wall Street Journal article earlier this week reported on the self-parking Lexus LS460. Toyota, its developer, demonstrated this amazing technology in a parking garage 'within sight of Ford's Dearborn headquarters'.
The story made, in my opinion, several key points.
One was the story of the crystal headlight glass. Evoking the attention to detail that was involved in the legendary development, over 20 years ago, of the original Sony Walkman portable cassette player, the car's chief engineer painstakingly redesigned the headlights to more accurately resemble fine crystal. To do so, he actually had a crystal headlight made, then sent this to the supplier in order to be sure the latter had the exact "look" desired, from which to manufacture the production-grade headlights for actual assembly.
Second, Toyota is now enjoying, and employing, the accruing benefits of success, including internal funding for growth. The article mentions many measures of Toyota's recent success: profits, size, hiring plans, etc. Suffice to say, their attention to consumer tastes, desires, and the fulfillment of those, has driven it past Ford and GM in terms of profitability and recent growth rates.
It should have. That's how markets are supposed to work.
The Journal story's ending comment is noteworthy. It comments on Toyota's continuing 'inferiority complex.'
To quote the piece, "Unlike baseball pennant races, contests for sales and dominance in the (auto) industry never end."
That's entirely right. Joseph Schumpeter taught us that "the race" never ends- anywhere, anytime. Thus my search for consistently superior performance, which, in a well-run, well-positioned company, can be the resulting hallmark of this healthy inferiority complex of Toyota's.
Next, we have yesterday's and today's coverage of the Paris alliance talks between Carlos Ghosn of Nissan, and Rick Wagoner of GM.
Between the WSJ piece yesterday, and this morning's continuing coverage on CNBC, it's evident that, for better or for worse, Rick Wagoner is rolling the dice now, with all of GM's shareholders' money on the line.
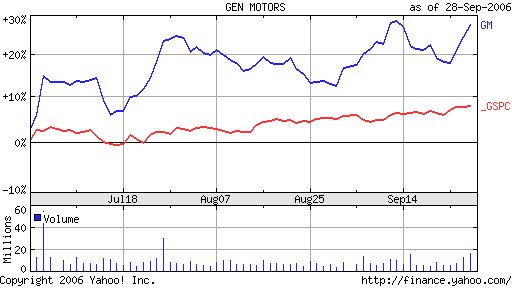 Personally, I find it laughable that anyone can call this year, based upon such brief and one-off events, a "turnaround" for GM. The chart on the left is what traders, analysts, and CNBC talking heads are all excited about right now. Over the past three and six months, GM's stock price is easily outperforming that of the S&P500.
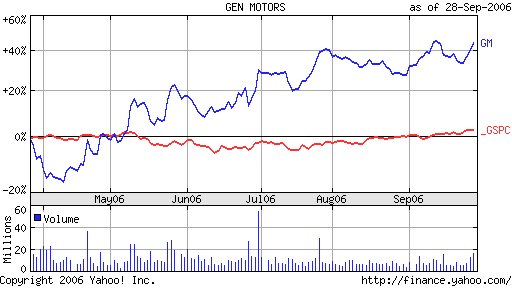 This, we are told, is the result of investors believing that GM is now in turnaround mode, and will return to automotive dominance imminently.
Not so fast....
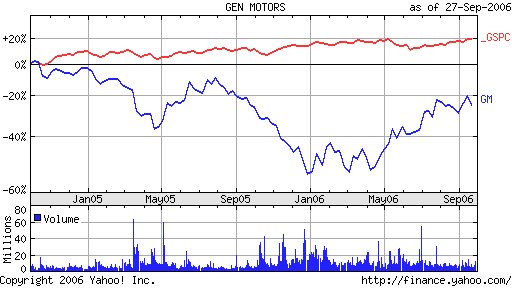 Here's what the charts look like for the past one and two years. Completely different, aren't they? GM is flat for the past twelve months, and down for the past two years.
Now I read, and hear, that GM's CEO is feeling so confident of his brief, one-time trick of shedding some labor costs, that he's decided to demand tribute from Carlos Ghosn and Nissan/Renault, should the two form an alliance. According to the Journal, GM wants a "multibillion-dollar payment" from Nissan and Renault.
 Wagoner is really a clever guy- give him that. He doesn't want this alliance. It was forced upon him by Jerry York and Kirk Kerkorian, his newest and most irksome board member and shareowner. How to evade the alliance? Loudly proclaim that a non-sales, non-customer-based, one-time financial cost reduction is, in reality, the much-heralded "turnaround," and then use that "fact" in order to make an unacceptable demand as a condition of any alliance with Nissan and Renault.
Yesterday's Wall Street Journal front-page piece, and this morning's coverage of the situation by CNBC, both cast doubt on the likelihood of any alliance being consummated. The most recent word is that the two parties have agreed to go away and reconsider terms, etc, for the weeks remaining in their 90-day alliance evaluation period which ends on October 15.
So Rick Wagoner is now "all in" with his shareholders' money. The Nissan/Renault alliance probably marks the last refueling stop on GM's uncertain road to recovery. If Wagoner successfully derails the alliance, then his shareholders better pray he has more up his sleeve than more job and cost cuts. And maybe Wagoner better check his own liability insurance for coverage from gigantic shareholder lawsuits for fiduciary breach.
Back to Toyota, though. Because that company figures in the GM alliance talks, too. According to Ghosn, Toyota is the company to beat, and he wants this alliance in order to have a decent chance of surviving that juggernaut's impending rise to global automotive dominance. Being a game of momentum and scale, Ghosn realizes that his companies have to be able to stay the course with enough capacity and design capability to match the Japanese giant, stride for stride, going forward.
Clearly, Ghosn isn't sure he has enough resources to do it presently. But GM may be demanding too high a price, and for an alliance that Ghosn doesn't even seem, based on his comments this summer, will even work effectively.
Once again, we see Schumpeter's theories in action. Wagoner is playing in his little Detroit fishbowl, and just wants Nissan/Renault, and Ghosn, to go away. Maybe to Dearborn, maybe back to Tennessee. Yet, GM can't really demonstrate a full-fledged, customer-based resurgence in its own fortunes at this time, nor, really, a very highly-probable scenario in the near future, either.
Ghosn, on the other hand, is running scared. Which is a good thing. He's competent, tough, and now, scared. Just like Toyota, his main adversary for the coming, pre-Chinese automotive sector rise, decade. That kind of healthy fear transforms companies into nimble, fleet customer-needs-serving, consistently superior total return performers. Not always, but it helps.
So now we have the lay of the land, in the microcosm of two of this week's automotive sector stories. Toyota demonstrates why it's the company to fear in the sector. Nissan's Ghosn demonstrates why he's the best bet for challenging Toyota globally. GM's Wagoner demonstrates that he's more interested in being left alone, to the potential detriment of his shareholders. And Ford is desperately hoping that maybe Ghosn will come back to call on them, and let them at least fight on the number two team, rather than alone, against Toyota.
Wednesday, September 27, 2006
More on Media from the Goldman Conference: Old vs. New
Last week’s Goldman Sach’s media investors’ conference was the subject of a recent Charles Schwab daily market email, to which I subscribe.
In part, it read,
“Investors could be forgiven for wondering if they had stepped into the wrong conference on Tuesday. Old media executives talked up digital strategies even as YAHOO warned of an unforeseen advertising shortfall. It appeared that old and new media companies had swapped roles for a day. While many blue chips slipped on Tuesday, a handful of media stocks rose after top executives at WALT DISNEY CO., VIACOM INC. and TIME WARNER INC. declared at the conference commitments to exploit the Internet to serve viewers anywhere, on any device. Meanwhile, Yahoo Inc. watched its shares fall after disclosing that two key advertising segments, autos and financial services, were weaker than expected. The panic selling of Yahoo appeared to do little to shake the resolve of media executives, some of whom once considered the Internet little more than an interesting sideshow. What's up for one-time Internet-skeptic NEWS CORP. next year? "To continue to drive into the digital transformation," Chief Executive Rupert Murdoch told investors. Murdoch's own stock on Wall Street has surged after buying one of the fastest growing Internet properties, MySpace.com, last year. Disney CEO Bob Iger took the opportunity to reveal it had sold $1 million of movie downloads on APPLE COMPUTER INC.'s iTunes in just a week.”
It does seem ironic that the “old” media companies are scrambling pell-mell to secure outlets for their aging content libraries, while the “new” media Yahoo was visibly weakened during the conference.
However, I don’t think Yahoo’s experience holds any import for the clutch of old media firms. As I have written here recently, Yahoo is probably the weakest of the “new” media firms, if you can rightly call it that. It doesn’t really offer content, what it does offer is mostly for free, and it isn’t really distribution, either.
Rather, what does not surprise me is that TimeWarner, Disney, Viacom and News Corp are frantically trying to sell or lease their video and audio content before it becomes eclipsed by the potential all-online production and distribution model.
Consider the prospect, in the current online environment, of some hot TV producers and rising new stars on YouTube going directly to consumers online with new films. It’s not as far-fetched as it may at first seem. Right now, on YouTube, one can view smart, interesting videos with great production values, running to more than 10 minutes. From there, it’s not a huge step into feature-length films. All it will take is some promotion on a YouTube channel, a URL, provision to take payments using PayPal, and broadcast and theaters have become disintermediated. A few years of this, and the content libraries of those old media titans will begin to be barren of recent goods, and only have aging stock gathering cyberdust.
Of all the old media names, I would hypothesize TimeWarner may be in the most precarious situation, this week’s analysts’ upgrades notwithstanding. As an owner of significant distribution and content assets, nobody trusts it. Other distributors can’t be assured of continued access to TW content. Other content providers worry that they will be locked out of, or given inferior access/terms, on TW’s cable systems. No company has managed consistently superior total return performance as an integrated media distribution and content firm yet. I doubt TimeWarner’s going to be the exception.
Add to this Apple’s impending release of iTV, about which I wrote here, and the downfall of old media becomes more likely. With an easy method of downloading new, online-marketed content from URL to PC, then, wirelessly to the Apple-provided, or one of its competitor’s, servers, and then via wires to consumers’ living room TVs, broadcast’s weakness becomes more glaring.
It’s really…well…entertaining, to watch the media sector change almost quarterly, as old media hurries to extract some value for its content, while new media distribution races ahead by allowing anyone to produce and market content, bypassing traditional media.
Dare I write, “stay tuned?”
Tuesday, September 26, 2006
Immelt's Five Year Anniversary As GE CEO
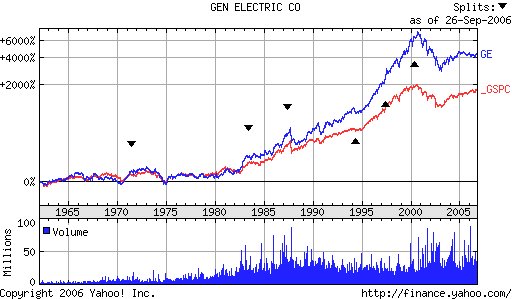
On September 11th, The Wall Street Journal ran a celebratory piece on Jeff Immelt's five-year anniversary as GE's CEO.
The Yahoo-sourced chart on the left depicts how Immelt's reign compares with those of prior CEOs of the company (Phillippe, Borch, Jones, Welch) going back to the early 1960s.
It's fair to say that long timeline charts such as this one can downplay earlier rough spots, since the end periods tend to have magnified appearances. For instance, the late-80s drop in stock price, coinciding with the 'crash' of 1987, is significant for its time, but pales in comparison to the absolute drop of the last few years.
 That being the case, here's a five-year view of the same information, corresponding to Immelt's tenure as CEO.
It seems to me that the WSJ is giving Immelt, and GE, the kid glove treatment. Maybe it's because of the fear of loss of GE's advertising revenues, and access to future stories.
However, looking at this Yahoo chart, it's difficult to understand how an industrial conglomerate can have underperformed the S&P500 through these particular last five years, and not be seen as needing to be led by someone else, or simply broken up.
Ask yourself this question:
If GE did not exist today, would someone create it as it currently exists?
I think the answer would almost certainly be, "no." What possible value would investors see in a TV network and movie studio buying: a jet engine business, a locomotive business, a financial services business, and power generation systems businesses, to name a few. There's absolutely no business synergies whatsoever that are unique to these businesses.
As I wrote here early last month, there is no longer any apparent value to the constituent business units of GE being assembled as GE.
Rather than observe the data I did in my earlier piece, the Journal contained quotes like this one, from Immelt's lieutenant, Bob Wright, vice chairman and head of GE's entertainment sector,
"He's in a good dynamic for a guy who has a lot of weight on his shoulders."
Does anybody reading this understand that sentence? Maybe Wright meant this,
"He's making a heckuva lot of money for a guy who has a lot of weight on his shoulders from not delivering for his shareholders."
Toward the end of the article, we perhaps get a clue as to why Immelt's GE is foundering so badly. The Journal relates that Immelt "urges employees to make bigger bets without fearing for their jobs if they fail." "Make it personal," the piece quotes GE's CEO as saying.
So now we have the 'kinder, gentler,' GE in evidence. Maybe Immelt figures, if he is kind to his employees, and forgives lack of performance, or consistently poor investment judgment, his board will do the same for him. Seems to be working, right?
In the end, all of Immelt's changes are not affecting the company's total returns. He can globalize the behemoth, ask his managers to take more risks, and even shuffle businesses in and out of the GE portfolio.
But in the end, over five years, Immelt simply has failed to lead GE to consistently superior performance, while raking in a royal compensation, as I noted here, back in March. In that post, I observed that Immelt has already received at least $21MM in cash compensation for failing to create consistently superior total returns for his shareholders. There's no way he needs to take the risks evidently necessary to make GE's long-term performance superior to the S&P's.
Furthermore, why give up this multi-million dollar gravy train and break the company up?
In this era of concern over "corporate governance," I'm frankly disappointed that the Wall Street Journal gave Immelt such an easy pass while reviewing his first five years at the helm of GE.
A year ago, I wrote, prior to almost any well-known pundit or industry analyst, that Ford and GM were in major trouble. Especially Ford. Back then, I opined that maybe the old media and investment banking giants weren't being candid, because the slowly-dying auto giants still paid a lot of bills for companies in those sectors.
I wonder if the same thing is occurring now, with GE. The truth would be very, perhaps too, costly to the media and financial service sectors, wouldn't it?
Monday, September 25, 2006
Retail Notes
I read two interesting pieces recently in the Wall Street Journal regarding retail commerce.
On Thursday, the paper's Marketplace section reported how widely flat-panel TV retailing has spread. Companies as diverse as Office Depot, Home Depot, Costco and Kohl's have jumped into the fray. Until now, conventional local TV retailers, and big box electronics outlets like Circuit City and BestBuy have been responsible for much of the sales volume of flat-panel TVs.
As prices for the new TVs fall, and larger models hit price points below $2,000, low-price retailers such as Wal-Mart and Costco are becoming a larger part of the retailing market.
It's not surprising that so many retailers are drawn to an almost-sure thing- the rise in popularity, as prices fall, of flat-panel television. Of course, if these companies do realize tremendous sales growth from the products, then, at some point, they face a dilemma in replacing that sales growth, or lapsing back into slower-growth modes. And that type of pattern typically keeps companies from earning consistently superior total returns over a number of years.
With so many retailers entering this product/market, it suggests that the production capacities for these TVs, probably in the Far East, must be very large. It doesn't require a lot of thought to envision some pretty vicious retail price competition, as a flood of flat-panel models pour into the US market in the next few years.
On another retail topic, today's Journal catalogued a number of states and municipalities which are passing, or have passed, anti-Wal-Mart legislation.
The Journal piece quotes Boston's Mayor, Thomas Menino, as saying,
"They don't pay wages that are sufficient. Their benefit structure is poor. I don't need employers like that in our city."
Interesting that a public official feels comfortable prohibiting citizens from choosing to work for Wal-Mart, or the company for risking its own capital in opening a store in the Boston area. So much for individual liberty in terms of choosing employment options in Boston.
However, a company that has engendered this type of reaction across the country can't be in great shape. Many municipalities seem to be restricting or prohibiting Wal-Mart's entry in order to protect their locally-owned businesses.
As I wrote here, and here, recently, Wal-Mart is already tampering with the branding and positioning strategies which brought it such success over the past two decades.
These cases of governmental hostility to the company's expansion plans would seem to add more challenges to Wal-Mart's already-full plate. According to the Journal's piece, the company's sales growth has slowed below double-digits recently, after decades in the that range. Same-store sales growth is a third of what it was in 1990.
The company is targeting urban areas, finally, for its next growth spurt. But it doesn't look like that's going to be happening.
Which corresponds with what I wrote here last fall. I just don't see the company continuing its past successes in terms of both fundamental growth and consistently superior total returns for its shareholders.
US Corporate Recruiting of MBAs: The WSJ's Survey
Last week's Wall Street Journal survey of corporate recruiters ranked the University of Michigan as the nation's #1 graduate school of business. In fact, the highest rank for one of the traditionally better-known schools was #7, for the University of Pennsylvania's Wharton School.
In a way, I believe it explains some of what we see in corporate America.The recruiters, according to the article accompanying the rankings, value 'communication and interpersonal skills,' 'ability to work within a team,' and 'personal ethics and integrity' all above more task-related dimensions like 'analytical and problem-solving skills,' and 'strategic thinking.'
It conjures up in my mind a group of nice, well-dressed, friendly but unimaginative young MBAs all gathered around a large conference table, 'teamworking' some issue for their new employer.
Perhaps the average returns of US business doesn't get 'better' because so many companies are so pragmatic when it comes to hiring management 'talent.' If they hire MBAs for teamwork and communication, maybe they miss getting problems solved, spotting opportunities for innovative products and services, or making the right strategic moves.
To me, this survey's results firmly indicate that the MBA has finally become a trade degree, along the lines of an electrician's or plumber's license. Not a toolkit for business value creation.
My partner discussed the survey results with his son, and they agreed that, given the choice between attending Michigan or, Penn, Chicago, MIT, etc, they'd both pass on Michigan for one of the other business schools with faculties more associated with the development and publication of new business thinking.
While I am not surprised with the survey's results, I believe it confirms a continuing use of business schools by companies as a rudimentary training ground for mundane business management needs, rather than a source of potential leadership and fresh thinking.
What I would be more interested in, from the survey's results, is which companies recruit more heavily at the more classically-highly-ranked schools, such as Wharton, Harvard, Yale, Sloan, Chicago, etc. Is there a difference in companies' long-term total return performance which is in any way explained or associated with the schools from which they primarily draw their new management hires?
Could we develop a profile of how the customers of some graduate schools of businesses are different than those of others? In a word, segment the customers of these schools?
Have the schools themselves done so, and, if so, what have they found?
Now, that would really interest me. Perhaps the WSJ should do this in the future, to provide some more interesting insights on what the trends in selection criteria imply for company performance over the long term. Summary statistics are nice, but the segment-specific insights would be very revealing.
Subscribe to:
Posts (Atom)


