Monday, January 15, 2007

EBay and StubHub

An article in last week's Wall Street Journal detailed the acquisition of StubHub by EBay. I wrote about StubHub in a post here, last September.


In my earlier piece, I asked why TicketMaster and its clients didn't accept the responsibility for doing a poor job of ticket pricing, in order to get guaranteed, although lower, upfront revenues across their many venues.


In this piece, discussing the upstart's acquisition by the online auction giant, the focus is missed opportunities. Doesn't EBay's purchase of the ticket reseller sort of indict their own business development model? StubHub is only six years old. If this doesn't demonstrate EBay's paucity of ideas now, what does?

As an online resale venture, EBay should have owned this market. Instead, it had to cough up $310MM for it. And we're not talking about buying a corporate titan. StubHub is a shoestring operation, compared to either TicketMaster or EBay.


As with many other businesses which have outgrown their initial, value-adding concept, EBay now seems to have to grow revenues at much lower margins than in the past. In this case, paying upfront to secure access to a business they missed starting themselves earlier in this decade.


Dell, Home Depot, Wal-Mart, Microsoft.....these are all companies whose core value-adding breakthrough eventually exhausted itself. As the Yahoo-sourced chart on the left demonstrates (please click on the chart to view the enlarged version), now EBay is joining them. The firm outperformed the S&P500 during 2002-04, and then began to slide. Since 2004, it has actually declined in value, while the index has continued its steady, gentle rise. So, while EBay has outperformed the S&P over the entire period, it has not consistently, nor recently, outperformed it.

It's not wrong, per se, for EBay to be buying StubHub. However, I think it's a sign that you won't be seeing the firm return to earning consistently superior total returns for its shareholders anytime soon. If they can't grow profitably and organically in their own product/market space, what do they possess with which to add superior value for their customers and, thus, indirectly, their shareholders?

More Business Holiday Wal-Mart Bashing on CNBC

Today is a Federal holiday, so the equity markets are closed. There is no Wall Street Journal. And CNBC has 'alternative' programming running.

As it so typically does on days like this, CNBC trotted out its apparently award-winning video piece, by on-air analyst and commentator David Faber, which spotlights Wal-Mart.

I admit to never having sat throught the whole production at one go. I've seen quite a bit of it in segments, though. It's fair to say that it highlights both good, and bad, facets of the company, and features extensive interview footage with the current CEO, Lee Scott, as well as some time with retired CEO David Glass.

However, my point in this brief post is to suggest that maybe CNBC is stoking the anti-Wal-Mart fires merely by running this thing every business holiday. I swear that this is at least the third time in twelve months that they have done this.

If you search this blog for the term "Wal-Mart," you'll recover 20 articles which mention the company. If you read this column regularly, then you know I am not exactly a fan of Wal-Mart's CEO, management team, or performance. But I bear absolutely no animosity toward the firm, per se. It's a matter of poor performance, not a personal grudge.

With CNBC, I am beginning to wonder if they simply want to hurt Wal-Mart as much as possible, until, I don't know....the company fires Lee Scott? Closes its last American store?

With so many thousands of hours of video footage, why must CNBC resort so frequently to just one, long video production about one harried company, nearly each business/Federal holiday?

Sunday, January 14, 2007

Validation and Echoes of My Video Distribution Prediction

The Wall Street Journal ran a piece detailing some of the new deals being cut to mainstream video content straight onto Internet TV. The Journal's article concludes, as I did last fall, here, and here, that these deals

"could undercut the role of cable and satellite companies."

Apparently, we now have Starz and Showtime distributing their content to the web for TV viewing. Nickelodeon is doing the same. Vehicles such as the Microsoft XBox 360 can be the terminus for the program, from which it will be fed to the user's television.

a Forrester Research source pronounced that,

"if you're a cable operator, this is very disturbing."

Indeed, it is. While, as the article points out, the move may not occur overnight, the die is definitely cast.

In a related article in the Journal, two days later, CBS is reported to be plunging headlong into this model, under the aegis of Leslie Moonves. As the owner of old media 'assets,' such as network television, print publishers, and outdoor media, CBS was more or less left holding the bag, when Sumner Redstone split Viacom from CBS.

Although Moonves denied that recent ratings softness was related to the also-recent, bold moves into the digital world, one cannot be so naive as to believe this. Moonves just saw his boss fire Tom Freston, at Viacom, for being too slow to move his businesses to the internet.

In fact, the title of the Journal piece about CBS is "CBS Ties Its Future to Internet Efforts."

Despite the reluctance of many, including my consulting friend, S, to believe that a video content disintermediation from network, via the internet, to television, could be so soon in coming, apparently I am not the only one who sees things this way. Not only are others seeing the implications, but major old-media companies are already throwing in the towel and heading for what they hope are choice pieces of 'real estate' in the new, online content world.

With Apple's recently-announced 'AppleTV' initiative, and Microsoft's XBox360, the wireless links from PC to TV accessory are now in place. All that remains is for prices to begin to slide, and consumers will be capable of controlling the when, from where, and how of their video content consumption, via the internet.

Look for broadcast networks to offer less new or premium content, and, as I wrote in some of the above-linked pieces, producers to vend their content directly from their own websites to consumers, completely bypassing anything but the iTunes "general store," or similar content aggregation websites.

Saturday, January 13, 2007

Innovation, Commoditization, and Steve Jobs

Thursday's Wall Street Journal yielded an interesting piece on innovation. The second section of the newspaper has a new feature, entitled "The Informed Reader."

Under the subtitle, "Strategy," we are told that Columbia Business School's Bruce Greenwald once stated,

"In the long run, everything is a toaster."

This piece of idiocy was meant to warn that any product is ultimately and eventually reduced to a commodity.

Whoever thinks this is true must not be a marketer, or not have studied marketing.

The article goes on to cite MIT's Media Lab researcher Michael Schrage as finding that "innovation has a continued role, even in such staid objects as toasters and vacuum cleaners."


Schrage cites Hoover in vacuum cleaners, and GE in toasters, to highlight how even seemingly-mundane products can be revitalized, technologically repositioned, and become a source of significant new revenue growth.

Yes, you worry because anyone can produce what you do, but not everyone can emulate the design of what you do, when you do it.


And this puts a premium, of course, on continuous innovation. Or, as I see the output, consistently superior revenue growth. The successful future of a company lies in innovating any or all of the 'four Ps' of marketing- product, place, price and promotion- in order to better serve customer needs. Surrendering to price competition is the first step along the road to commoditization.

Which brings me to Steve Jobs. Jobs has proven to be a genius in his later career. But this was not always the case. Recall his serious stumble in, first, mismanaging the early successes of Apple Computer, and then recruiting John Sculley to succeed him.

In retrospect, I believe this simply demonstrated that Jobs is at his worst in a slugging match of equals, i.e., commodities. When he attempted to go toe to toe with the other personal computer makers, and Microsoft, he ended up frustrated, bored, and out of a job.

Recall, if you will, that he took a few trusted aids and started Next, which was ultimately bought back by Apple, for its object-oriented code assets.


Jobs' attempt at pushing forward a little on communications needs resulted in the failure Apple called "Newton."

In contrast, Jobs hit grand slams with his work at Pixar, and the iPod line. He is clearly at his best inventing the future, far out in front of current solutions.

In this respect, is he not rather like Thomas Edison? Like Edison, Jobs is often hustling and marketing just as fast as he's developing product. Like Edison, Jobs is egotistical, a reportedly demanding taskmaster, and short on giving named credit for much of what comes out of his development teams.

However, if anyone needs a clear example of how innovation can effect companies, look no further than Apple. With an impressario at the helm, someone who seems to simply love what he is doing, the firm has simply left Microsoft and Bill Gates in the dust when it comes to leading his firm into new, growth markets.

Yes, innovation is crucial for long-term growth in equities. One must not confuse the ability of virtually any product or service to be replicable, given time. The key is to realize that it does take time, and, in that time, the innovator can be, once again, steps ahead of the mere copiers.

For me, Frank Perdue's branding of chickens and chicken parts opened my eyes to this as a young marketing student in graduate school.

Looking back to the beginning of this piece, and the Greenwald quote, one wonders how a business school professor could be so short-sighted as to reduce innovation and marketing to a zero-sum game, confusing replication with innovative designs and solutions for customer needs.

Friday, January 12, 2007

Forecasting Economic Health with One Indicator: The Yield Curve

Monday's Wall Street Journal's Money and Investing section featured a piece on the analytical import of the prolonged yield curve inversion.

By now, everybody, even those who have not studied economics, knows that inverted yield curves have, historically, frequently been associated with recessions. The trouble is, the indicator sometimes gives false positives.

Then there is the criticism that, if forecasting a recession was that easy, why aren't these economists shorting equities already?

Those doubting the indicator allege that 'this time, it's different.' They point to global demands for a safe haven for cash. Or that 'markets have changed.'

I suppose this debate will continue until either a recession does, incontrovertibly, arrive, or the economy continues its low-inflationary growth phase for another year or so.

Perhaps the moral is that you need to use multiple forecasting methods, not just the inverted yield curve, to predict recessions. Any one tool is prone to being misled. A suite of tools, providing a sort of 'information theory' approach to the task, would be better.

In the meantime, I suppose everyone will continue to watch the yield curve and the GDP's quarterly growth numbers for the next six months with heightened 'interest,' as it were.

Thursday, January 11, 2007

GM's Bulging Inventory of 2006's "Hot" Cars

Monday's Wall Street Journal reported that GM's unsold finished goods inventories of cars have become enormous.

The article states that, at the end of December, GM

"had more than one million vehicles in stock in the U.S. That's equivalent to about 41,000 vehicles for every point of its 24.6% U.S. market share. By contrast, Toyota..., one of the world's most profitable auto makers, carried about 16,000 vehicles of inventory per point of its 15.4% market share.

Among the unsold vehicles, the piece later explains, are some of the models that GM's management felt were "hot" models for last year- the Chevrolet HHR, the Buick Lucerne, and the Saturn Aura. Some of these cars now have a 90+ day supply sitting on lots across America.

Apparently, we have yet to see the much-vaunted, newly-creative GM emerge. Because the products they evidently pinned much of their 2006 sales hopes on are sitting, unsold, in storage around the country.

GM finds itself in a vise of its own device, in that it must, on one hand, cut costs, such as inventory financing, and, yet, maintain production in order to generate cash flow to assist its 'turnaround.'

Failure to keep production levels up starves it of cash to pay its mountain of fixed liabilities relating to healthcare and pensions, but unsold inventory ties up much-needed liquidity, as well as spurs price cuts via low-interest rate sales programs.

Interestingly, GM's haphazard pricing tactics have contributed to its woes. With much car shopping initially done online now, the company's reliance on relatively higher sticker prices, coupled with the expectation of dealing on financing, causes many buyers to exclude the company's products from consideration.

Of the dilemma, GM's CFO, Fred Henderson was quoted as saying,

"This is the area where we have a lot of work to do in the future."

No kidding.

Having been in the auto business for, oh, nearly a century, with, at one time, the overwhelming market share in the American auto market, you would think GM's management would, by now, have its customers' buying behaviors down pretty well, wouldn't you?

Evidently not.

Yet another firm for which 2007 is starting out with a thud.

Tuesday, January 09, 2007

China's Dependence on Tobacco and Smoking

Last week, the Wall Street Journal ran a piece on China's dependence on tobacco as a centerpiece of its economic development.

The article focused initially on the province of Kunming, which has based much of its economic growth on the product. However, as the piece began to broaden to encompass all of China, the information began to look truly scary.

The Chinese death number is expected to double by 2005.

"One third of all Chinese men now age 29 or younger will die prematurely from tobacco-related diseases."

Allegedly, more Chinese people smoke than are in the US. One estimate of the cost to China last year from smoking was $5B, in medical expenses and lost productivity.


There are many details about the Chinese tobacco industry in the article, but I'm not really interested in recounting or commenting on them in this piece.

Rather, I have two major questions, as a result of reading the Journal piece.

First, can a country afford to either kill off its productive assets, i.e., its citizens, prematurely, and/or foot the immense medical costs for their smoking-related illnesses? Second, could tobacco become the achilles heel of the Chinese economy, in much the same way that a lack of focus on profitability and, then, borrowing in a foreign currency, were to the Japanese economy in the 1970s?

On the matter of the first question, I suggested to some friends that the Chinese economy would have to absorb a massive amount of healthcare-related costs, much as America's automakers have had to do for their retirees. My cynical friends opined that, 'no,' the Chinese would not be so burdened, because the Chinese government will simply let its smoking-induced ill citizens die without much medical care.

If that's true, then let's simply examine the consequences of that. How much premature loss of trained economic assets, in the form of a society's people, as workers, can a country sustain, before its productivity is affected? The ultra-low-wage jobs will soon migrate elsewhere, so, like all other developing economies, China will have to sustain its economic development upon creativity and productivity. How can it do that if it only gets 20-25 good years, on average, per worker, before they become ill? I don't know the exact life-expectancy loss from the Chinese smoking habit, but you get my point. It's surely a drag on the Chinese economy, if only as a simple ratio of reduced lifetime economic output per trained worker.

Thus, my second question. Could this seemingly incidental facet of Chinese society eventually torpedo its plans to dominate global economics? I guess, on one hand, premature deaths from smoking will lower the average age of the population, and reduce the pension cost problems. However, more seriously, is it possible that a significant loss of economic capacity, productivity, and skill, from premature worker deaths, could hamper China's ability to compete with healthier society's?

Will the health and producitivy penalties of tobacco in the long run offset its near-term boost to the Chinese economy? I recall that, in the late 1970s and early 1980s, the American business media was fixated on the coming economic domination of Japan. The country seemed unstoppable. Until, that is, its obsession with market share and growth, to the exclusion of profits, hollowed out its financial strength. Then, its dollar-denominated debt proved a crushing burden, because they had to service it with their own yen.

After all the loss of productivity, via healthcare and legal costs, that America has suffered from asbestos and tobacco, one would think the Chinese could build upon such lessons and avoid the same fate. Evidently, as a society, they aren't yet that smart.

Finally, for the moralists among readers of this blog, what, if anything, can other societies do, as they watch the Chinese promote the early death of their own people? Is there any appropriate action other societies can take? Or would that constitute unwanted, baseless interference in the civil affairs of another society?

McDonalds Resurgence


Last weekend's Wall Street Journal ran an article on McDonalds, the fastfood titan. Now that it's in my portfolio, the story caught my eye.

As the nearby Yahoo-sourced price chart indicates (please click on the chart to see a larger version), the company really has turned around in the last five years, and outperformed the S&P over the period.

The firm's CEO, Jim Skinner, was a part of the management team that began to improve McDonald's four years ago. He moved up to his current job when one CEO died suddenly, and the next resigned to wage a battle with cancer.

What I liked about Skinner's responses in the interview was how clear-thinking and sensible he is. For instance, he said,

"....we proved that we were getting bigger but not better. And we have to be better. Your experience today at McDonald's has to be a better experience than it was yesterday. People have limited time today. They don't want to get up and go, "Gee, I don't know. Do I think I can go to McDonald's?" "

Skinner has a clear focus on his customers' behaviors, which is always heartening in a CEO, especially in a retail business, where there are so many individual purchase decisions each day.

Later in the interview, he is quoted as saying, regarding the four-year old turnaround strategy,

"We had contributed $4B or $5B to capital expenditures and building new stores over four years, and yet we didn't have any corresponding incremental operating-income growth. So we decided to focus on our existing restaurants. Those of us that were hardcore restaurant people, which I was at the time, were saying, "Look, we've got to do a better job of delivering what we called quality, service and cleanliness on a daily basis in our restaurants." And value. Because value proposition's very important."

Skinner's remarks show how sharp this company's management team is. He related later that a considerable amount of time and effort of every senior manager is spent identifying and grooming their upcoming talent. He attributes the company's ability to 'accelerate our momentum' to 'selecting the high-potential people.'

When asked what his biggest remaining challenge is, Skinner replied,

"I worry about complacency. We're not satisfied. We have a lot of work to do."

That's what I love to read about from CEOs whose company's shares I own. Toyota's CEO says the same thing, whereas his faltering rival, Rick Wagoner of GM, feels he's on track.

I loved the things I read about Jim Skinner, and McDonald's, in the Journal piece. It impressed me so much, that, having just bought some of its shares, I had lunch there yesterday, on the way back from a midday errand.

It was everything Skinner contended. The food was well-prepared, and less expensive than I expected. The store was very clean. Though after the noon-time rush, one employee did nothing but circulate among the tables, wiping off food remnants and spraying, then wiping them clean with a disinfectant. My visit was fast, clean, and delivered familiar food. The menu even seemed simplified and easier to use than I recalled on my last visit to a McDonalds some years ago.

Needless to say, I hope the company continues to do well. At least for the next six months of my portfolio investment. Based upon Jim Skinner's interview in the Wall Street Journal, I'm confident that it will do so.

Monday, January 08, 2007

Wal-Mart's First Gaffe of 2007: Scheduling Part-Time Workers

It's 2007- a new year. Within only three days, we have the first significant Wal-Mart gaffe of the year.

Last week, the Wall Street Journal carried an article discussing Wal-Mart's latest productivity improvement approach. They are employing new, dynamic labor-scheduling software which more closely matches store staffing to customer volume, as well as observes various constraints, such as employee hours worked, overtime, etc.

These guys just don't get it, do they?

Sure, labor scheduling software can be a good thing, within limits. But in their zeal to become the most efficient retailer, Wal-Mart risks total alienation of even the few capitalists who can still defend them.

This is the type of corporate behavior that brought us unions in the first place. It's just not wise. Why would you want to go after your own employees' qualities of lives and abilities to earn reasonable livings?


To me, this is just an open invitation to be pilloried again by a now-Democratic House and Senate.

Do you wonder, as I do, if Lee Scott has any common sense at all? Perhaps these continuing gaffes are, in fact, emblematic of the core competencies, or incompetencies, of the company?


On the heels of last year's many problems- the mistaken upscale repositioning, the race-based store segmentation, the reversal on selection on an ad agency, and public relations "ambassador" Andrew Young's invectives against other minorities- we now have the world's largest retailer improving productivity seemingly on the backs of its workers.

I'm all for efficiency, but, in reality, there are advisable limits within which a company should stay, in order to not invite regulation and excess scrutiny from government. I think Wal-Mart is off to a phenomenally bad start to this new year.

Friday, January 05, 2007

Private Equity & Home Depot

Earlier this week, on Wednesday, the Wall Street Journal published an interview with Henry Kravis.

I've written posts about private equity before,
here, here, and here. Rather than restate all my thinking and points, you may read them there. Suffice to say, the last six months have not changed my findings regarding this topic.

Now, however, the media is all abuzz about Bob Nardelli, a reputed "operations guy," coming back for Home Depot as the CEO of a buyout group. Was Home Depot simply under leveraged? Would financial engineering have done the job? Certainly, one alternative was simply to dividend back to shareholders the cash that wasn't earning adequate returns at the firm.

What if all the mismanaged companies go private. What if all the good managers go private to run companies more simply? Would we not expect, if this happens, to see S&P average returns fall, as companies with promise leave the index? Or would they rise, because most private equity targets are actually performing below average. That's why they are targets.


Doesn't private equity get its big payday by taking these companies public again? So, isn't this private equity shift the on-shore effect of SarbOx, similar to the fewer IPOs on the American exchanges?

Is it not a sort of return to the 1890-1930s model of corporate chieftains who knew their boards, actually knew how to run companies? A few, wealthy, proficient owners who were largely unfettered by distractions like large numbers of small-scale shareholders? Then, when the juice is squeezed out of the company, the private equity groups will return their prize to the market.......at a premium, of course, to the price at which they took it private.

Let's suppose this does accelerate. Maybe that is the only way corporate boards will wake up and demand better performance, for appropriate compensation, from sitting CEOs. Might not CEOs, a la my post citing the example of VNU, demand higher buyout prices from the private equity groups, as they realize the 2x multiples the latter are reaping?


It should , in time, be self-correcting, should it not? Perhaps a new type of employee/group will arise: the "rental CEO & Co." Imagine a capable, smallish group of corporate troubleshooters willing to 'fix' a troubled company, letting shareholders remain in possession. Suppose they only ask for $20-40MM in fixed compensation for a 2-3 year period- enough to cover their operating risk. Then, they could agree to a fairly high valuation target which, if achieved, would compensate them lavishly, but still for far less opportunity cost than if shareholders had sold out to a private equity group at, effectively, the bottom.

In time, perhaps shareholders will demand that boards get the same performance out of their assets as private equity groups expect to realize after their overhaul of the same assets.

As for Nardelli, I'm not so sure, as I've read more pieces about his management style, that he's really going to fit into the collegial, results-oriented world of private equity. Many media pundits allege that Bob 'got the job done' at Home Depot, but simply failed to be recognized for it. I disagree. By several "operating" measures, such as sales and NIAT growth, he lagged his major competitor, Lowes. Plus, somebody has to be responsible for total return. Perhaps senior functional executives may be measured according to internal financials, or market share goals, but the CEO is paid lavishly to consistently earn superior total returns for the firm's investors. All else is superfluous.

Thursday, January 04, 2007

Dennis Kneale's Views on Nardelli, Fiorina, et al

Dennis Kneale, Forbes Magazine's managing editor, appeared as a guest host on CNBC this morning. He believes that Carly Fiorina and Bob Nardelli fixed, respectively, Hewlett-Packard and Home Depot, and then were fired, after which their successors have or will get the credit.

Don't you believe it.


Kneale's argument, taken to its extreme, is to return to allowing CEOs to escape accountability for their firms' total returns, unless, that is, the returns are healthy and rising. This will simply become another excuse for lack of board performance and vigilance.

My proprietary research shows that, when company performance is consistently superior, the market will contemporaneously reward the company and, thus, the CEO, with higher stock prices. Correspondingly, the market 'rewards' other performance patterns appropriately. Investors reward what they value, period.

If Fiorina and Nardelli chose the wrong strategies, and failed to deliver what the market wanted, then they failed their shareholders. Period.

It's not appropriate, nor consistent, to let CEOs pick and choose which investor behaviors to consider 'right.'

For instance, later this afternoon, CNBC replayed a tape of an interview Nardelli gave to one of its reporters, in which he admitted to having changed the bases on which he and his "leadership team" were compensated. Originally, upon being recruited to Home Depot, he was to be rewarded for increasing the stock price. After some three years as CEO, the basis was changed to various fundamental, internal operating measures, such as earnings, sales and margin growth, relative to other retail firms. He alleged that it was thought better to move to bases which were more 'controllable' by the "leadership team."

That Home Depot's board consented to this seems, to me, to be outrageous and pathetic. For the compensation Nardelli earned as CEO of Home Depot, he certainly should have been responsible for knowing what performance to effect in order to improve shareholders' wealth. Whether every member of his team was also responsible may be another matter. But someone in the firm has to take responsibility for operating the firm in a manner calculated to increase shareholder wealth, not to mention at a rate which makes owning the shares of the firm preferable to those of an S&P500 index fund.


Otherwise, the firm's senior management will happily focus on internal financial or market share performance, oblivious to whether or not any of these affect the total returns to shareholders.

It reminds me of something I saw years ago, in my managerial youth, at the Chase Manhattan Bank. My partner and I were conducting an assessment of the productivity and profitability of the various functions which composed the firm's Securities Trading group. The business head of the unit took credit for the profitable years' performance, but lamented that 'unavoidable market conditions' had led to some years of losses.

How convenient. The SVP in question got a bonus for the profitable years, but he didn't have to return any of it in the losing years. I suggested that we could replace him with a monkey and save the then-average compensation of a bank SVP, about $350K. With a monkey, his subordinates would probably still perform in a manner correlated with the market, but we'd only have to buy bananas for the 'new' SVP of Securities Trading.

Nardelli and his ilk need to take care that they do not become eligible for replacement by lower primates. Shirking responsibility for producing consistently superior total returns for shareholders essentially relegates a CEO to the status of chief apologist, rather than Chief Executive. Someone has to be responsible for steering the corporation in the direction of presumably higher total returns.

In exchange for several million dollars of annual compensation and a hefty severance package in excess of $200MM at Home Depot, it had better have been Bob Nardelli.

Wednesday, January 03, 2007

Bob Nardelli's Resignation as CEO at Home Depot

This morning's breaking news regarding Bob Nardelli's resignation as CEO of Home Depot, effectively immediately, is welcome news to me. Hopefully, it will be, as well, for investors at large.

As I have written recently
here, and this summer, here, and here, I think it is past due.

Nardelli's poor performance and imperial attitude, most explicitly apparent in the 'boardless' May, 2006 annual meeting in Delaware, finally outlasted their welcome with Home Depot's overly-patient board.

I am gratified for several reasons. First, it is good to see a board finally wake up and discipline its CEO for failure. Second, it reinforces my belief in my proprietary research-based view of business dynamics. Where others purportedly saw opportunity and "powerful numbers...powerful performance," I saw inadequate operational performance, and appropriate lackluster market price performance, as well.

As various analysts and pundits on CNBC babbled about Nardelli's arrogance as CEO and Chairman of Home Depot, they also tended to assert that this was not the major cause of his departure. I would agree. To me, style doesn't count anywhere near as much as performance. And Nardelli's performance during his tenure at the company was miserable.

Similarly to my recent post concerning CitiGroup CEO Chuck Prince's extraordinary good fortune,
here, I think Nardelli received several years' grace time from his board, as well. Would any of his subordinates receive such forgiving treatment?

Perhaps it's a fitting start to the new year, that an atrociously underperforming CEO gets the boot.

Happy New Year!

Tuesday, January 02, 2007

ATT: Forbes "Company of the Year" for 2006?

Forbes has chosen AT&T "company of the year" for 2006. The firm's chairman, Ed Whitacre, stares out from the magazines current cover edition.

Perhaps I'm in the minority here, but I don't see it. Posted on the left is the company's five-year stock price chart, courtesy of Yahoo, along with the S&P500 (please click on the chart to see a larger version).

It's probably a moot point to attempt to interpret revenue growth for the firm now, since it been affected by acquisitions. The annual sales growth rates are, for 2004-6, 0%, 1%, and 37%. There is by no means, yet, a clear record of sustained revenue growth in the combined firm.

NIAT is also a giant hockey stick, still negative in 2005, at -23%.

Regarding total returns, the company now known as "AT&T" has a total return which has only exceeded that of the S&P500 index twice in the past seven years: 2000, and 2006.

None of this indicates to me that AT&T is now a smoothly-functioning, world-class firm. In fact, unless I am mistaken, I am now, once again, a customer of their wireless business. I've had AT&T, then Cingular, and now, evidently, AT&T once again. So much for brand building. My usage of their long distance is now de minimis. The wireless business is apparently hoping for ad revenues to save them.

I confess to being a sceptic on this one. More power to Forbes if this is the "company of the year" for 2006- or any future year.

Monday, January 01, 2007

"Five Macroeconomic Myths"

This being New Year's day, and a slow last few business days, I want to discuss a "filler" topic which I've hung onto since mid-December.

In the December 11th Wall Street Journal, Edward C. Prescott, 2004 Nobel Prize-winner for economics, senior monetary advisor at the Minneapolis Fed, and professor of economics at University of Arizona Cary School of Business, wrote a piece thusly entitled.

The first thing I'd like to note is that I don't think I had heard of Mr. Prescott, or could identify him in unaided recall, prior to reading this incredibly lucid and important piece. I see a constant parade of lesser economic lights troop through the CNBC studios each day, but not Mr. Prescott. As I wrote in this post,
here, on June 11th of last year, there are a lot of economists who think they know more than, or as much as, Ben Bernanke. I begged to differ. However, Mr. Prescott is precisely the sort of economist to which I referred when I noted that the Fed staffs would probably be a better source of economic thought than some 'chief economist' of a second-rate US bank or brokerage firm.

Having established Mr. Prescott's credentials, let me summarize his five 'myths:'

1. Monetary policy causes booms and busts.
2. GDP growth was extraordinary in the 1990s.
3. Americans don't save.
4. The U.S. government debt is big.
5. Government debt is a burden on our grandchildren.

Suffice to say, Mr. Prescott provides some very illuminating evidence to eviscerate all of these myths.

My favorites are numbers 3-5. First, he assails national income accounting, writing,

"Our traditional measures of savings and investment, the national accounts, do not include savings associated with tangible investments made by businesses and funded by retained earning, government investments (like roads and schools) and business intangible investments."

He focuses on the relationship of wealth to income, and judges the US savings rate to be "the right amount."

Mr. Prescott observes that "privately held interest-bearing debt relative to income" is at levels comparable to those of the 1960s. So he also judges our governmental debt level to not be "too big."

Perhaps the most interesting myth is the fifth one. It's a sort of product of the third and fourth myths, with a little emotional zing tossed in about the next generation's inherited liabilities.

Here, Mr. Prescott refers to some prior research, stating,

"Theory and practice tell us that the optimal amount of public debt that maximizes the welfare of new generations of entrants into the workforce is two times gross national income, or GDP. This assumes 1% population growth, 2% productivity growth, 4% real after-tax return on investments, and that people work to age 63 and live to age 85. Currently, privately held public debt is about .3 times GDP, and if we include our Social Security obligations, it is 1.6 times GDP. In either case, we could argue that we have too little debt."


Mr. Prescott actually make the point, subsequently, that government debt is a necessity if one has a long-lived population that is not growing rapidly. In effect, the more older, non-working people a society has, the more productive assets it needs with which to generate wealth in order to pay for those retired people. It's the reverse of how most economists present this situation.

Rather than hand-wring about debt and retirement, Mr. Prescott implicitly assumes a preference for creating wealth, then assess whether the right debt levels are in place to most efficiently do that in the given context.

What I liked most about his piece is how, at a stroke, he removes most of the bases for those who assert we have a government debt problem, a savings problem, and a looming retirement-affordability problem.

Similarly to other economics topics upon which I have touched recently, he focuses on two things. First, he 'rehabilitates' national income accounting to bring it a point of usefulness in the debate. Second, he provides insightful measures and research in order to effectively debunk myths regarding the allegedly-perilous US economic condition.

After reading Mr. Prescott's article, I feel much better about our current economic productivity, debt and savings levels. Far better than I typically feel after listening, on CNBC, to some third-rate economic "chief" of some little-known financial institution.

Quality matters, and Mr. Prescott is the genuine article.

Saturday, December 30, 2006

Alan Mulally's Ford Initiatives

I read the Wall Street Journal's recent piece entitled, "Changing Gears.... Inside Mulally's 'War Room': A Radical Overhaul of Ford."

I am so glad that I have not been a Ford stockholder. It's a good news/bad news sort of thing. The good news is that Mulally is smart, experienced, determined and energetic. I think it's great for Ford that Mulally is so talented. He does seem like a very competent, capable guy.

The bad news is that his boss, Bill Ford, let things get this bad. Tolerated crony pals mismanaging the firm, and that the board let it happen on their watch.

Now they all want Alan Mulally to work magic and fix the mess.

For example, the article mentions that Mark Schulz,

"Ford's 54-year-old head of international operations...would be changing jobs to a different role, with direct business responsibility...Mr. Schulz, a longtime fly-fishing and ice-hockey buddy of Mr. Ford, retired instead....(and) couldn't be reached for comment."

Sounds too precious, doesn't it? You can almost see Schulz mugging it up with Bill Ford over eggnog at the proper Gros Pointe country club holiday parties, wearing pleated slacks festooned with little ice-hockey sticks poking through Christmas wreathes, or fly-fishing rods catching Christmas stockings. This sort of thing drives employee morale into the toilet, I kid you not. Nothing infuriates capable lieutenants more than seeing the Boss socializing off-premises with also-ran managers who clearly curry favor and retain their positions thanks to friendships with the CEO, rather than their own performance or talent.

Meanwhile, Bill Ford let this continue as part of his "management" and "leadership" of his family firm.

In another part of the piece, Mulally is quoted as saying that, when he asked Bill Ford

"why he hadn't integrated the company....every time Ford had considered forcing integration, a new hit product- such as the Explorer, Taurus or F-series truck- would come along and propel profitability without tough changes, explained the fourth-generation Ford leader."

So to cronyism we can add lack of focus and discipline. The board and Bill Ford are hoping to God that Alan Mulally can do the dirty, harsh, odious work of firing loyal, trusting employees, redesigning bloated, dysfunctional corporate processes, and identifying new, hit products. Because for five years, as CEO, and six as a board member, Bill Ford failed to do all of these.

In fact, the Journal article related this exchange between Chairman Bill (Ford, not Gates) and board member John Thornton, former President of Goldman Sachs,

Ford: "Alan's the perfect guy for our situation."

Thornton: "I couldn't agree more. Thank God for that, we don't have a second chance. This is it."

What is it with Detroit auto company CEOs? Must they wait until they teeter on the edge of bankruptcy before shifting gears (pun intended)?

Is there time for Mulally to save Ford? Who knows? Is he doing some right things? Unquestionably. For instance, he drives each model of the firm's product line, the better to give it a personal, objective going-over. His comment about the lack of a standard "feel" for Ford cars is absolutely true. My father was a "Ford man" when I was growing up. In models of similar years, the controls were typically located in the same place. You knew you were in a Ford, not a GM car, just by the layout of the dashboard and knobs.


The WSJ piece lavishes much print on Mulally's rather unremarkable, if very effective, use of colors and graphic displays to track product-management issues in his 'war room.' That this technique, and his insistence on the divulging by managers of complete and true performance data, is more than shocking. It's disgraceful. Consider what it says about the lack of respect these managers have had for Mulally's predecessor.

Oh, wait....that's the sitting chairman......Bill Ford!

Will Mulally's sensible initiatives matter? Truthfully, I doubt they have the time. Still, oddly, I can't but help root for the guy. Maybe in 3-4 years, Ford will make my equity portfolio selection list. Although, my hunch is, not as an independent company. Perhaps as part of an alliance with Nissan. If it merges with GM, I would lower the probabilities of its performing sufficiently well to make my selection list.


Either way, 2007 will be exciting for lots of reasons, and Mulally's activities at Ford are just one.

Happy New Year!

Friday, December 29, 2006

David Malpass on The US Trade Deficit

Bear Stearn's chief economist, David Malpass, wrote a wonderful piece in the Wall Street Journal last week. His topic was how the US deficit is misunderstood and misinterpreted by many observers. In this, he is but one of several to have authored op-ed pieces in the Journal to this effect over the last decade or so.

I won't go into detail about the many data items Malpass cites as he conditions his observations in the article. However, this passage is perhaps the piece's best distillation of his message,

"The common perception is that Americans drive the trade deficit in an unhealthy way by spending more than we produce. To make up the difference, foreigners ship us things on credit. This sounds bad, but should be evaluated in terms of our demographics, low unemployment rate, attractiveness to foreign investment and rising household savings (my bold)."

A little further, he continues,

"Growing corporations are expected to be cash hungry. This leverage is treated as a positive for companies, but a negative for countries, a key inconsistency in popular economics. Rather than paying back the debt back, the growing economy rolls the debt over and adds more, just as the U.S. has been doing throughout most of its prosperous economic history. Part of each additional bond offering puts the company and the U.S. in the position of investing more than we save, drawing in foreign investment and contributing to the trade deficit."

Together, these passages make Malpass' critical point, i.e., sovereign debt, and/or trade deficits, matter in the context of the country's economic trajectory. In our case, we have the largest, vibrant, resilient and attractive economy in the world. Despite what economic and political gloomsters would have you believe, we borrow at favorable rates because others wish to participate in our economic success. They hold dollars, or dollar-denominated debt, and invest in our country directly. We use that capital to grow. Malpass makes the point further in his article that American household net worth is growing faster than net foreign debt of the U.S.,

"meaning foreigners are investing in the U.S. too slowly and conservatively to keep up with our growth."

It's a nice problem that we have, actually. Our economy is the envy of the world, which is one reason why even The Economist has sounded like a broken record on this topic for as long as I can recall. Context matters. Context means everything in macroeconomic analysis. By the way, in one of the earlier Journal pieces on this topic, another author cited the late 1800s in the U.S. as a parallel economic period. We had significant growth and a large trade deficit, consistent with heavy imports to fuel our rapidly-industrializing young nation. While Abe Lincoln was right about a lot of things, he was wrong to worry about trade deficits.

It goes without saying that this type of nuanced analysis will go over the heads of most U.S. Senators and Congressmen, and probably most Presidential candidates as well.

It reminds me of something my father used to frequently say. When listening to yet another media criticism of low voter turnouts in some fall election, he would remark thusly,

'Son, you only get to vote once every four years for the President. But you vote each day with your dollars, and those have a much larger and frequent impact than your political vote.'

What I think this means, pursuant to this post, is that, despite most politicians, and even most economists, not understanding the real dynamics of our trade deficit, so long as our nation's citizens just continue to drive our economy as usual, the trade deficit will not be any more of a problem in the future than it has in the past.

Thursday, December 28, 2006

Flawed Analytics and "Training Programs"

I recently discussed my post of last week concerning Home Depot with my partner. In it, I contrasted Lee Cooperman's cheery view of the company, in which his hedge fund has a sizable position, with the rather downbeat view of the firm, based simply upon its sales and NIAT numbers for the past five years. My partner and I wondered how such basic, obvious quantitative evidence could simply be ignored, and/or swept aside, by both Cooperman and Bartiromo.

He asked me if I thought Cooperman or Bartiromo even looked at HD's overall numbers? Or if I thought Bartiromo did anything more than simply reinforce, agree with, and mouth assent to Cooperman's selective factoids? On both counts, I admitted that I doubt it.

It would be one thing for this to occur in the course of private investment determinations. But to air such a shallow attempt at "analysis" on a major business medium such as CNBC seems to both observe the commonality of, and countenance, such shoddy work.

How much of this, do you suppose, goes on? Partial views of company performance? Selective factoid presentations? Skewed, biased 'analysis' in place of a clear presentation of information known to have a significant statistical relationship to the consistent attainment of superior total returns?

As we discussed the Cooperman-Bartiromo interview, we segued into a related matter- the ever-popular Wall Street two year 'training programs.' He wonders how anyone can really learn much of value, when worked to death like his son. A close friend and business associate of long standing also has a son who is about to enter one of these two-year prison camps. His son referred to it as "two years of hell."

I ask a different question,

'How can something which can be learned by anyone, in two short years, be of much lasting and unique value?' If so many go through these programs, how valuable can they be?'

Personally, I don't even think most MBAs learn all that much in two years.

First, consider that many, if not most, MBA candidates enter from non-business fields. So they spend the first year catching up to what a business undergrad spends his or her first two years learning. Then they interview for jobs beginning in the fall of the second year. Having landed an offer, their academic focus typically wanes. From my experience at a Top Five business school, I would estimate that the average MBA candidate actually focuses on learning anything considered 'advanced,' as opposed to simply passing basic courses or studying in their concentration area, for about six months.


Does this sound like a recipe for churning out unique, creative, value-adding managers?

Some years ago, I considered returning to my alma mater for a PhD in Marketing, the field in which I studied for my two business degrees. My former mentor and advisor took me to lunch at the Penn faculty club to discuss the idea. While we chatted, I observed that, in the decade or so since I had graduated with my MBA, leveraged buyouts and corporate restructurings had eviscerated almost, if not every, function and sector in corporate America. How could this have been emblematic of a corps of well-trained, competent, creative business grads making their productive and successful mark on the American business world?

He replied that, finally, at that time, circa 1990, MBAs were "finally" having an effect in the business world. Really? Only then?

Take the top five business school programs for the twenty-year period from 1970-90, and assume 500 members for each class. You get roughly 50,000 MBAs being disgorged into the US management ranks just from the top five B-schools alone.


No, I think most "two-year" programs, even for intelligent people, don't do much more than provide a rather common, universal business background. The Wall Street programs are more about finance, and less about real "business." The MBA programs seem to be a sort of business "boot camp" to winnow out the less capable, in order to provide a corps of semi-trained people eligible for further managerial 'training.'

My proprietary research has shown a remarkably stable average total return for the S&P500 over time. It does not seem to be the case that this influx of business school graduates or Wall Street trainees has enabled companies to return more to their shareholders.

Rather, I suspect that it simply provides a large pool of average managers to take their places in mostly non-high-value-adding positions in corporate America. Most of these graduates don't challenge what they've been taught, or even think much about it.

Where's the font of uniquely-skilled, creative, motivated business leaders who will make a difference for their shareholders? My guess is, they are rarely cut from the normal B-school or "training program" cloth. It's people with inspiration and ideas, not trained bean-counters and "managers," who will likely invigorate a company and earn its shareholders consistently superior total returns.

The good news, I guess, is that, as these "trained" robots continue to flood the financial markets, I have a sustained flow of similarly-thinking, non-creative counterparties with which to 'trade.'

Tuesday, December 26, 2006

CNBC's Erin Burnett's Myopia

This morning, on CNBC, Erin Burnett observed that the US equity markets posted nearly the smallest gains among the world's exchanges.

For example, she cited India's and Vietnam's markets as rising significantly more than that of the US, with Vietnam's up something like 45%.

Let's get something clear. All markets are not equal. For instance, Burnett doesn't mention liquidity, depth, trading expenses, or listing requirements. Little details, you know?

I find that this sort of 'shoot from the hip,' unconditioned observation, passing as analysis, is all too common on the network. Exactly who did this story help?


Institutional investors presumably already know about various international equity markets and their risks. Retail investors are typically advised to participate in markets via country-oriented mutual funds. Even there, reporting on this year's gains doesn't say anything about next year's. While this is always true, I would think it's especially true in thinner, less-well capitalized and transparent markets like those of third-world countries.

Once again, the network seems to deliver more on entertainment and less on hard, analytical business or markets news and analysis.

Investor beware, alright. Beware of the 'advice' you hear on CNBC.

Thursday, December 21, 2006

Indian Pharma Scientists Return Home

Last Thursday, the Wall Street Journal featured a piece on Indian scientists now returning to India. As with Chinese engineers, many of the scientists have formerly been with large American firms- in this case, pharmaceuticals.

On the whole, though, I believe it's a good thing. India becomes more wired into global trade, as its scientists begin to develop new medicines and seek to export them. It will open India up, much as the evolving economy of China will for that country.

In time, Indian pharma wages will rise, and even it will gradually become less competitive, on a comparative basis. Of course, as more Indian professionals return and start competing firms in technology, pharmaceuticals, commodities, etc, their standards of living will rise, and they will consume more international goods and services. Many, no doubt, will be American in origin.

Perhaps, over the next decade, Western firms will begin to acquire some of these Indian startups, in the same way they often buy ideas and talent in the US that left the paralysis of large corporations, to start new businesses. We don't yet know what India will adopt as a policy involving this sort of acquisition activity, but it may well become more important for world trade in the coming years. Will Western countries and markets remain open to Indian and Chinese markets that constrict asset purchases, ownership, and economic participation by foreign companies?

How will a Democratic US Congress view the loss of higher-paying, management jobs to countries such as India? Especially if the latter maintains trade barriers, while attempting to export newly-developed products and services?

This is free trade. Isn't this what we, as Americans, ultimately want? Comparative advantage and mobility work. If this is what it takes to re-energize some sectors of large corporate America, as it sees an ethnic brain drain, so be it.


The migration of highly-educated talent back to home countries may, on one hand, look like a net loss for America. However, it may well result, as in China, in the accelerated Westernization of these formerly-third-world countries, so that their economic, social and political values and agendas begin to more closely resemble those of America and her Western allies. As we move further into what promises to be a long global war on terror, initiated by radical elements of Islam, can it be a bad thing to have the world's two most populous nations begin to adopt America's perspectives on economic growth, development, and living standards?

Rather than see a brain drain, perhaps we should view developments such as the Indian scientists returning home as a net loss to the US, perhaps we should see it as successful export of, and prostyletizing on behalf of, our values and socio-economic system. Much cheaper, and more effective, than military conquest of foreign lands. This way, our economic system becomes embedded into other cultures, and fosters nascent democratic political appetites, as well.

Wednesday, December 20, 2006

Home Depot, Again: Leon Cooperman's "Powerful Numbers"

Yesterday afternoon, Maria Bartiromo interviewed Omega Fund founder CEO, Leon Cooperman, by telephone, on CNBC. The "video," with Cooperman's audio, can be viewed here.

I must admit that I found the 'interview' to be rather unusual. Rather than have Cooperman interact, on camera or via microphones, with one Ralph Whitworth, another institutional investor who is assailing Home Depot's board and management for ineptitude, Bartiromo/CNBC chose to simply refer to Whitworth, show a video clip of an earlier interview with him, and then present Cooperman live, alone. She opened the piece by citing Omega's 5 1/4 B of assets under management, and its position of 2.5MM shares of HD. The nature of the introduction seemed calculated to confer some sort of infallibility on Cooperman and his investing choices.

Could Lee be 'pumping' Home Depot, with CNBC's help? Or, at the least, defending it?

Let me be very clear here. I am not saying that Cooperman, Bartiromo, or CNBC did anything illegal. Omega's beneficial interest in Home Depot was explicitly stated at the beginning of the interview. However, it is indisputable that CNBC had Cooperman appear in order to tout a stock in which his fund has a fairly large position. Further, they had him on after another investor who had made pointed allegations of board and managerial failures to perform.

Cooperman went on to list a set of reasons to risk your capital on HD. He gave testimonials on Nardelli, via Jack Welch, Nardelli's one-time manager at GE, on Welch himself, and on two directors of HD. Fine. But, where's the beef?

Maria said, in agreement with Cooperman, of Nardelli's operating record,

"the numbers are powerful....revenues, earnings.....powerful under Nardelli....no doubt about it."

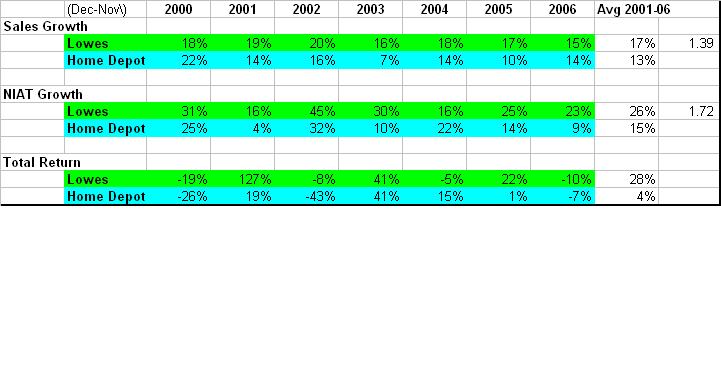
Really? Look at the chart on the left, displaying the performance of sales, NIAT, and total return for Home Depot and Lowes since 2000. You may click on the chart, and on the subsequent stock price charts, to view larger versions of all of them.

Sales growth has finally accelerated again at HD in the last twelve months, but it still lags that of its major competitor, Lowes. Net Income Available after Taxes, up 9% for the past twelve months, is the lowest increase since the first full year under Nardelli. And, again, it lags Lowes by more than twofold.

Powerful performance, eh, Bob...Maria....Lee? I just don't see it. I didn't see it,
here, or here, either, in my posts on this topic back in July of this year.

Cooperman went on to list a series of rapid-fire 'data' about Home Depot. Its real estate position has increased. Dividends and earnings up over a short period of time. The company bought stock back. So what? These are intermediate activities which are not having an effect on the firm's stock price. That Lee Cooperman thinks they should is beside the point, isn't it? Unless his personal opinion is supposed to be sufficient reason to buy the stock. Which would be nice for him, since his fund, remember, already owns 2.5MM shares of Home Depot.

Cooperman clearly believes, as a result of his fund's analytical team's meetings with HD's management, that the company's stock will eventually be appreciated, even though, now, it's "undervalued." His reeling off of the many operating statistics, mostly rather abstruse numbers, sounded like he was reading from a list his analysts had prepared for him.


Specifically, it reminds me of my own experiences in corporate America. The staffers build a set of numbers and talking points so that the senior executive, who is not as well-versed on the topic, can rattle off seemingly-unassailable numbers. Do you think any of the carefully-selected data presented by Cooperman, on behalf of his analysts, will be negative or cast doubt on Home Depot's 'powerful' operating results? Unlikely.


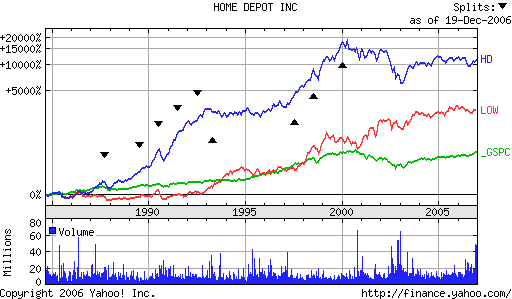
To get a better picture, here's a Yahoo-sourced chart of stock prices for Home Depot and Lowes, plus the S&P500 Index, for the past five years. Lowes is clearly superior, and HD can't even outperform the S&P. Despite Cooperman's plea that the firm is simply misunderstood, the market


For a little more perspective, here's a chart of the same data for a much longer timeframe. It's clear that, since 2000, things have never been as good for Home Depot as they were before then. Nothing that Nardelli has done for six years has succeeded in improving the company's total return to beat that of the S&P500.

Meanwhile, Lowes' stock price has continued to rise steadily, though not, apparently, much faster than the index since around 2001.


The only basis on which I saw improvement in HD's stock was in the last three months. Blogger is not cooperating with my attempts to paste a stock price chart. However, Yahoo's charts shows that, over the past 90 days, HD has outperformed Lowes, roughly 9% vs. flat, but still underperformed the S&P.

Of course, if Cooperman's premise is that you have to catch the right 3-6 month period in order to earn superior returns in Home Depot, I don't think that's going to help most investors. It sounds more like investing on technical indicators, and hopes of a short-term "pop" from some transitory fundamentals in the near future, then correctly timing your exit from the position.

However, in terms of long-term, consistent performance, Home Depot does not appear to have improved since my analysis in July of this year. And, on a comparative basis, it does not seem to be performing "powerfully" at all, Maria Bartiromo's and Leon Cooperman's contentions to the contrary. I attempt to present the data on which I base my assessments whenever I critique a company's performance. For me, the Cooperman interview on CNBC, and Bartiromo's and Cooperman's statements claiming great fundamental performance for Home Depot, seem empty without clear, written or graphic evidence to substantiate them.

Tuesday, December 19, 2006

Income Inequality

Alan Reynolds wrote a fabulous piece in the Wall Street Journal last Thursday concerning America's alleged income inequality. It is a masterpiece in demonstrating that attention to details, and knowledge of data sources, can make all the difference between a valid conclusion, and useless speculation.

Specifically, Reynolds, who is a senior fellow at the Cato Institute, and co-founder of Polyconomics, identifies the source of Senatorial candidate Jim Webb's statement that,

"the top 1% now takes in an astounding 16% of national income, up from 8% in 1980."

The researchers responsible for these numbers, Thomas Piketty, of Ecole Normale Superieure in Paris, and Emmanuel Saez, of the University of California at Berkeley, used tax returns for their denominator, rather than total income. Major income sources which they omitted, according to Reynolds, were Social Security and other transfer payments. Of course, we would expect these types of payments to go to lower income earners, thus further skewing the findings of the two researchers.


Other sources of error include the non-filing of some income earners, municipal bond and other tax-exempt income sources, and the inclusion of two, joint filers on single tax returns at the higher end of the tax-reported income spectrum. Reynolds estimates that total personal incomes, the denominator for the inequality statistics, was roughly $3.3B in 2004, or slightly more than 1/3 larger than Piketty and Saez estimated.

Another source of error which Reynolds discusses is the tax-policy-driven shift of small, formerly conventionally-filing corporations, to Subchapter S corporations. These are often higher income sources taking advantage of a different reporting structure, thus improperly appearing to inflate upper incomes, when, in reality, they were simply measured as business income sources in prior years.

Reynolds' fine, detailed and sensible work demonstrates how easily such inflammatory statistics as the ones Senator-elect Webb (D-Va) used can become commonly held "wisdom," or "fact."

In reality, it appears that the work on which those statistics are based was very flawed, and has generated suspect results. As time-consuming, dry and tedious as it may be, doing the fundamental work of investigating definitions and research methodologies can often shed valuable, and, occasionally, disconfirming light on apparently important and troubling results. Such is the case with the now-well-publicized 'increasing income inequality' in America, as demonstrated by Alan Reynold's good work and articulate explanations.

Monday, December 18, 2006

Toyota's Awesome Drive To Dominance

Last (December 10th) weekend's Wall Street Journal featured an article about Toyota. Having a series of more timely pieces which occurred last week, I elected to wait until now to accord this post the attention it deserves. There are several important insights to be gleaned from the Journal article concerning my research and thoughts about consistently superior performance. Toyota is showing both the good and the bad effects of consistently superior performance- how to do it, what it returns, how fragile and fleeting it can be.

What initially struck me from the Journal piece is how Toyota CEO Katsuaki Watanbe's incredible insecurity fuels his company's continued excellent performance.

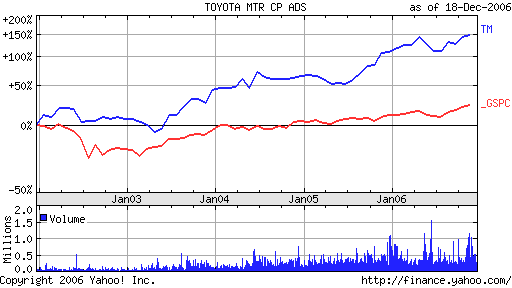
As the nearby, Yahoo-sourced chart of Toyota's stock price, versus the S&P500 Index, indicates, the company has performed consistently better than the latter for most of the past five years. It's cumulative total return far surpasses that of the index over the entire period. Toyota isn't among the companies in the S&P500, so I don't own it. How I wish I could, and did.

As my proprietary research warns, however, cost-cutting is a relatively limited weapon in the quest for long-term, consistently superior total returns. Toyota's are already nearing an end as a competitive weapon. The rate of cost reductions is slowing, and product design flaws have recently spurred recalls of more vehicles than it sold last year.

I was very impressed with the attention to detail by the CEO. The Journal article discusses his observant manner as he walks the floor of his plants. His questioning of the traditional, long paint shop river, is what recently has led to Toyota's secret new process, which takes far less space and resources. Watanabe is ceaselessly exploring new ways to drive costs down and extend Toyota's lead in this area. To this end, he has commissioned a total re-evaluation of the production of the company's vehicles, with an audacious objective of cutting the number of parts required by 50%.


While, on one hand, Toyota is bumping up against some cost-cutting limits of current production methods, Watanabe is wisely opening up the company's managers to exploring entirely new ways of designing and producing their vehicles, thus, effectively, in microeconomics terms, putting the firm's operations on a new, longer-term, declining cost curve. They have redesigned their machines to be smaller, and their plants as well.

What amazes me about Toyota is that, while GM is catching up to them in some production efficiency measures in some plants, Toyota is already moving to tackle new production challenges that I cannot even imagine GM being ready to address. The production plant challenge is one, as is the paint line. Thus, Toyota is working on changing the very methods by which they will more efficiently pump out vehicles, while GM, and, presumably, Ford, are still working on making existing methods merely more efficient. It's clear that the two American auto giants are not even remotely in the same class as Toyota when it comes to conceiving and implementing continuous methods of improving operating efficiencies, and, thus, value-added.

Will Toyota succeed in these operational changes? Their diminishing lead in current efficiencies demonstrates how cost leadership can shrink, and, thus, lead to a loss of sustained superior performance. However, they are attempting new initiatives to retain this consistently superior total return performance. Either way, they are at risk.

And this, I believe, is one of the most enlightening elements of the Journal's Toyota story. Even a detail- and big-picture-obsessed, experienced and successful CEO, like Watanable, with a willing workforce, and strong competitive position, cannot count on continued superior total return performance. He's betting the company's continued performance every year, with each new initiative.

Sooner or later, Toyota will run into more difficulties in one of its programs for new production methods, or design flaws, that will derail its superb performance of the past few years. The truth is, with each additional year of excellent performance, their odds of another one diminish. It's simply how performance patterns are among large numbers of large corporations.

However, I will take great interest in seeing for how long this impressive auto producer can maintain its record of consistently outperforming the S&P500's total return.

Wal-Mart Employee Attacks Customer

It's true that sometimes, only one rotten apple is necessary to spoil the whole barrel. As rational adults, on one level, we know this to mean that we shouldn't judge an entire organization by the actions of a single member.

Still, with all the outrage and angst Wal-Mart has generated this year, much of it self-inflicted, this episode, occurring at a Wal-Mart store in Gainesville, Florida, is hardly what Lee Scott needed to read about on this pre-Christmas holiday weekend. My consulting friend S sent me this link to the following story.......

Woman Slashed At Gainesville Wal-Mart 12/17/2006 By Michael Maurino
WCJB TV-20 News
One local teen went to a store to go shopping and ended up taking a trip to the hospital after a fight with an employee.
Now the store employee is facing jail time after slashing her across the neck.
Gainesville Police say the 17-year-old teenage girl was visiting the Wal-Mart on Northwest 13th Street.
She had walked out of the store, but went back when she thought she left her cell phone in a shopping cart.
Detectives say she approached 18-year-old Wal-Mart employee Darius stacy, who was retreving the carts, and asked if he had the phone.
The two started arguing, and then shoving each other before Stacy pulled out a weapon.
"The employee had a box cutter and he cut the 17 year old in the throat," said GPD Sgt. Keith Kameg. "Fortunately, they were non life threatening injures."
The young woman was treated at Shands U-F for a cut that extended from her left ear to her windpipe.
Stacy is being charged with attempted murder.


Need we mention something about every employee being a 'goodwill' ambassador? It's pretty rough when you now have to worry about contact with even the cart handlers at the nation's largest retailer.

Certainly it argues for online shopping, does it not?