skip to main |
skip to sidebar
Yesterday afternoon, Maria Bartiromo interviewed Omega Fund founder CEO, Leon Cooperman, by telephone, on CNBC. The "video," with Cooperman's audio, can be viewed here.
I must admit that I found the 'interview' to be rather unusual. Rather than have Cooperman interact, on camera or via microphones, with one Ralph Whitworth, another institutional investor who is assailing Home Depot's board and management for ineptitude, Bartiromo/CNBC chose to simply refer to Whitworth, show a video clip of an earlier interview with him, and then present Cooperman live, alone. She opened the piece by citing Omega's 5 1/4 B of assets under management, and its position of 2.5MM shares of HD. The nature of the introduction seemed calculated to confer some sort of infallibility on Cooperman and his investing choices.
Could Lee be 'pumping' Home Depot, with CNBC's help? Or, at the least, defending it?
Let me be very clear here. I am not saying that Cooperman, Bartiromo, or CNBC did anything illegal. Omega's beneficial interest in Home Depot was explicitly stated at the beginning of the interview. However, it is indisputable that CNBC had Cooperman appear in order to tout a stock in which his fund has a fairly large position. Further, they had him on after another investor who had made pointed allegations of board and managerial failures to perform.
Cooperman went on to list a set of reasons to risk your capital on HD. He gave testimonials on Nardelli, via Jack Welch, Nardelli's one-time manager at GE, on Welch himself, and on two directors of HD. Fine. But, where's the beef?
Maria said, in agreement with Cooperman, of Nardelli's operating record,
"the numbers are powerful....revenues, earnings.....powerful under Nardelli....no doubt about it."
 Really? Look at the chart on the left, displaying the performance of sales, NIAT, and total return for Home Depot and Lowes since 2000. You may click on the chart, and on the subsequent stock price charts, to view larger versions of all of them.
Sales growth has finally accelerated again at HD in the last twelve months, but it still lags that of its major competitor, Lowes. Net Income Available after Taxes, up 9% for the past twelve months, is the lowest increase since the first full year under Nardelli. And, again, it lags Lowes by more than twofold.
Powerful performance, eh, Bob...Maria....Lee? I just don't see it. I didn't see it, here, or here, either, in my posts on this topic back in July of this year.
Cooperman went on to list a series of rapid-fire 'data' about Home Depot. Its real estate position has increased. Dividends and earnings up over a short period of time. The company bought stock back. So what? These are intermediate activities which are not having an effect on the firm's stock price. That Lee Cooperman thinks they should is beside the point, isn't it? Unless his personal opinion is supposed to be sufficient reason to buy the stock. Which would be nice for him, since his fund, remember, already owns 2.5MM shares of Home Depot.
Cooperman clearly believes, as a result of his fund's analytical team's meetings with HD's management, that the company's stock will eventually be appreciated, even though, now, it's "undervalued." His reeling off of the many operating statistics, mostly rather abstruse numbers, sounded like he was reading from a list his analysts had prepared for him.Specifically, it reminds me of my own experiences in corporate America. The staffers build a set of numbers and talking points so that the senior executive, who is not as well-versed on the topic, can rattle off seemingly-unassailable numbers. Do you think any of the carefully-selected data presented by Cooperman, on behalf of his analysts, will be negative or cast doubt on Home Depot's 'powerful' operating results? Unlikely.
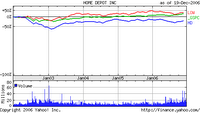 To get a better picture, here's a Yahoo-sourced chart of stock prices for Home Depot and Lowes, plus the S&P500 Index, for the past five years. Lowes is clearly superior, and HD can't even outperform the S&P. Despite Cooperman's plea that the firm is simply misunderstood, the market
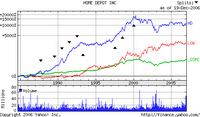 For a little more perspective, here's a chart of the same data for a much longer timeframe. It's clear that, since 2000, things have never been as good for Home Depot as they were before then. Nothing that Nardelli has done for six years has succeeded in improving the company's total return to beat that of the S&P500.
Meanwhile, Lowes' stock price has continued to rise steadily, though not, apparently, much faster than the index since around 2001.The only basis on which I saw improvement in HD's stock was in the last three months. Blogger is not cooperating with my attempts to paste a stock price chart. However, Yahoo's charts shows that, over the past 90 days, HD has outperformed Lowes, roughly 9% vs. flat, but still underperformed the S&P.Of course, if Cooperman's premise is that you have to catch the right 3-6 month period in order to earn superior returns in Home Depot, I don't think that's going to help most investors. It sounds more like investing on technical indicators, and hopes of a short-term "pop" from some transitory fundamentals in the near future, then correctly timing your exit from the position.However, in terms of long-term, consistent performance, Home Depot does not appear to have improved since my analysis in July of this year. And, on a comparative basis, it does not seem to be performing "powerfully" at all, Maria Bartiromo's and Leon Cooperman's contentions to the contrary. I attempt to present the data on which I base my assessments whenever I critique a company's performance. For me, the Cooperman interview on CNBC, and Bartiromo's and Cooperman's statements claiming great fundamental performance for Home Depot, seem empty without clear, written or graphic evidence to substantiate them.
Alan Reynolds wrote a fabulous piece in the Wall Street Journal last Thursday concerning America's alleged income inequality. It is a masterpiece in demonstrating that attention to details, and knowledge of data sources, can make all the difference between a valid conclusion, and useless speculation.
Specifically, Reynolds, who is a senior fellow at the Cato Institute, and co-founder of Polyconomics, identifies the source of Senatorial candidate Jim Webb's statement that,
"the top 1% now takes in an astounding 16% of national income, up from 8% in 1980."
The researchers responsible for these numbers, Thomas Piketty, of Ecole Normale Superieure in Paris, and Emmanuel Saez, of the University of California at Berkeley, used tax returns for their denominator, rather than total income. Major income sources which they omitted, according to Reynolds, were Social Security and other transfer payments. Of course, we would expect these types of payments to go to lower income earners, thus further skewing the findings of the two researchers.Other sources of error include the non-filing of some income earners, municipal bond and other tax-exempt income sources, and the inclusion of two, joint filers on single tax returns at the higher end of the tax-reported income spectrum. Reynolds estimates that total personal incomes, the denominator for the inequality statistics, was roughly $3.3B in 2004, or slightly more than 1/3 larger than Piketty and Saez estimated.Another source of error which Reynolds discusses is the tax-policy-driven shift of small, formerly conventionally-filing corporations, to Subchapter S corporations. These are often higher income sources taking advantage of a different reporting structure, thus improperly appearing to inflate upper incomes, when, in reality, they were simply measured as business income sources in prior years.Reynolds' fine, detailed and sensible work demonstrates how easily such inflammatory statistics as the ones Senator-elect Webb (D-Va) used can become commonly held "wisdom," or "fact."In reality, it appears that the work on which those statistics are based was very flawed, and has generated suspect results. As time-consuming, dry and tedious as it may be, doing the fundamental work of investigating definitions and research methodologies can often shed valuable, and, occasionally, disconfirming light on apparently important and troubling results. Such is the case with the now-well-publicized 'increasing income inequality' in America, as demonstrated by Alan Reynold's good work and articulate explanations.
Last (December 10th) weekend's Wall Street Journal featured an article about Toyota. Having a series of more timely pieces which occurred last week, I elected to wait until now to accord this post the attention it deserves. There are several important insights to be gleaned from the Journal article concerning my research and thoughts about consistently superior performance. Toyota is showing both the good and the bad effects of consistently superior performance- how to do it, what it returns, how fragile and fleeting it can be.
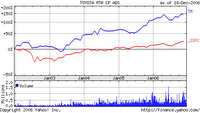 What initially struck me from the Journal piece is how Toyota CEO Katsuaki Watanbe's incredible insecurity fuels his company's continued excellent performance.
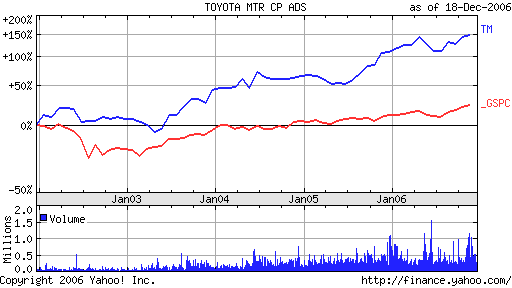
As the nearby, Yahoo-sourced chart of Toyota's stock price, versus the S&P500 Index, indicates, the company has performed consistently better than the latter for most of the past five years. It's cumulative total return far surpasses that of the index over the entire period. Toyota isn't among the companies in the S&P500, so I don't own it. How I wish I could, and did.
As my proprietary research warns, however, cost-cutting is a relatively limited weapon in the quest for long-term, consistently superior total returns. Toyota's are already nearing an end as a competitive weapon. The rate of cost reductions is slowing, and product design flaws have recently spurred recalls of more vehicles than it sold last year.
I was very impressed with the attention to detail by the CEO. The Journal article discusses his observant manner as he walks the floor of his plants. His questioning of the traditional, long paint shop river, is what recently has led to Toyota's secret new process, which takes far less space and resources. Watanabe is ceaselessly exploring new ways to drive costs down and extend Toyota's lead in this area. To this end, he has commissioned a total re-evaluation of the production of the company's vehicles, with an audacious objective of cutting the number of parts required by 50%.While, on one hand, Toyota is bumping up against some cost-cutting limits of current production methods, Watanabe is wisely opening up the company's managers to exploring entirely new ways of designing and producing their vehicles, thus, effectively, in microeconomics terms, putting the firm's operations on a new, longer-term, declining cost curve. They have redesigned their machines to be smaller, and their plants as well.What amazes me about Toyota is that, while GM is catching up to them in some production efficiency measures in some plants, Toyota is already moving to tackle new production challenges that I cannot even imagine GM being ready to address. The production plant challenge is one, as is the paint line. Thus, Toyota is working on changing the very methods by which they will more efficiently pump out vehicles, while GM, and, presumably, Ford, are still working on making existing methods merely more efficient. It's clear that the two American auto giants are not even remotely in the same class as Toyota when it comes to conceiving and implementing continuous methods of improving operating efficiencies, and, thus, value-added.Will Toyota succeed in these operational changes? Their diminishing lead in current efficiencies demonstrates how cost leadership can shrink, and, thus, lead to a loss of sustained superior performance. However, they are attempting new initiatives to retain this consistently superior total return performance. Either way, they are at risk.And this, I believe, is one of the most enlightening elements of the Journal's Toyota story. Even a detail- and big-picture-obsessed, experienced and successful CEO, like Watanable, with a willing workforce, and strong competitive position, cannot count on continued superior total return performance. He's betting the company's continued performance every year, with each new initiative.Sooner or later, Toyota will run into more difficulties in one of its programs for new production methods, or design flaws, that will derail its superb performance of the past few years. The truth is, with each additional year of excellent performance, their odds of another one diminish. It's simply how performance patterns are among large numbers of large corporations.However, I will take great interest in seeing for how long this impressive auto producer can maintain its record of consistently outperforming the S&P500's total return.
It's true that sometimes, only one rotten apple is necessary to spoil the whole barrel. As rational adults, on one level, we know this to mean that we shouldn't judge an entire organization by the actions of a single member.Still, with all the outrage and angst Wal-Mart has generated this year, much of it self-inflicted, this episode, occurring at a Wal-Mart store in Gainesville, Florida, is hardly what Lee Scott needed to read about on this pre-Christmas holiday weekend. My consulting friend S sent me this link to the following story.......Woman Slashed At Gainesville Wal-Mart 12/17/2006 By Michael Maurino
WCJB TV-20 News
One local teen went to a store to go shopping and ended up taking a trip to the hospital after a fight with an employee.
Now the store employee is facing jail time after slashing her across the neck.
Gainesville Police say the 17-year-old teenage girl was visiting the Wal-Mart on Northwest 13th Street.
She had walked out of the store, but went back when she thought she left her cell phone in a shopping cart.
Detectives say she approached 18-year-old Wal-Mart employee Darius stacy, who was retreving the carts, and asked if he had the phone.
The two started arguing, and then shoving each other before Stacy pulled out a weapon.
"The employee had a box cutter and he cut the 17 year old in the throat," said GPD Sgt. Keith Kameg. "Fortunately, they were non life threatening injures."
The young woman was treated at Shands U-F for a cut that extended from her left ear to her windpipe.
Stacy is being charged with attempted murder.Need we mention something about every employee being a 'goodwill' ambassador? It's pretty rough when you now have to worry about contact with even the cart handlers at the nation's largest retailer.Certainly it argues for online shopping, does it not?
Lest you think corporate America has become too hard on employees....too unforgiving and impatient......consider its treatment of one Charles Prince. I'm referring to CitiGroup CEO/Chairman Chuck Prince, of course.
In this post, late last month, I discussed CitiGroup's situation vis a vis BofA. Many media pundits were all a-twitter that the latter was about, and apparently did, overtake the former in terms of market value.
However, as I pointed out in that piece, the important measure to observe is consistent total return. In the charts contained in that post, you will see how Prince has steered CitiGroup into a dead-calm pool of a virtually flat, that is to say, zero, total return for his tenure as the firm's CEO and Chairman.
Now, such dismal performance might, you would think, merit dismissal. How many line VPs or SVPs of a major money-center bank would still be in their jobs, if they failed, for three straight years, to achieve their objectives? While their competitors outperformed them?Not many, I'd wager. But, it's different for CEOs. First, they get paid a lot more, regardless of their inadequate performance for years at a time.
Mr. Prince's FY2005 compensation is detailed here, courtesy of Forbes Magazine. According to Forbes, with confirming information from Reuters, here, Prince was paid roughly $13MM in 'direct,' cash-like compensation last year, and an additional $10MM in various options and longer-term compensation.Second, CEOs get a lot more time to perform. Prince has been CEO at CitiGroup for three years, and COO for two years prior to that. Word was, after the company's recent analysts meeting this week, that Prince has 'only another year' to 'fix things.'Wow, that's pressure, eh? Only four years, at something north of $13MM cash compensation per year, to mismanage one of the nation's largest banks.Where does the line form to replace him, come next January?The way I figure it, with Prince's lack of operating background, and four-year record of failure, the requirements for the job should be pretty minimal. Nearly anyone, apparently, can satisfy Citi's board as competent to lead the banking firm.Wouldn't you volunteer to risk your career in order to get a shot at $50-100MM in total compensation over four years, knowing termination after year four is the penalty?Life at the top is tough, friends.....very, very tough indeed.NOT!
Two weeks ago, I wrote this post regarding Hank Greenberg's activity in pursuit of the New York Times Company. In that piece, I noted Jack Welch's pursuit, with a group of other investors, of the Boston Globe.Now comes some bad news from a seriously creative, wealthy businessman. In last Friday's Wall Street Journal's article about him, Geffen admitted to wanting to build "a pre-eminent newspaper."Further, he is quoted in the article as saying,"It's difficult starting a business from scratch....The next thing I do, I want to buy rather than start from scratch....As a guy who is committed to, certainly by the time I die, giving everything I have a way, that gives me an awful lot of latitude about what I can and can't do."According to Forbes' 2005 survey, Mr. Geffen is ranked #117 on the list of the world's richest people, with a net worth of approximately $4.4B. Hank Greenberg was #170, with an estimated net worth of $3.2B. That may now overstate Greenberg's net worth, as his resignation from AIG in mid-2005 may have resulted in his loss of significant assets. Jack Welch was #376, with an estimated net worth of $680MM, as of the Forbes 2001 survey, but is no longer on the list in 2005. Perhaps the result of his expensive, very public divorce from his second wife earlier in this decade.Viewed from this perspective, Geffen has the deepest pockets, with Greenberg coming next. While Welch and his syndicate can doubtless borrow to buy the Boston Globe from the New York Times, Greenberg's interest in the parent may complicate, or may simplify, their pursuit of the ailing newspaper.It's perhaps noteworthy that Geffen, somewhat an impressario of artistic talent, created the largest economic fortune of the three. Less of a classic businessman than the other two, his objective of building a "pre-eminent" newspaper should probably be chilling news to Greenberg and Welch. Geffen clearly has no compunction about pouring as much of his net worth into the effort as necessary.I doubt Welch is that altruistic. Given Greenberg's maneuvering vis a vis his financial interests in AIG, I think he's more like Welch than he is like Geffen. For either of these former corporate types, with their smaller kitties, to engage in new-era newspaper-building combat with Geffen might well lead to their financial ruin.Geffen's comments can't be good news for Welch. What will the lenders at (JP Morgan) Chase, to whom Welch has gone for financing, now think about bankrolling the least-well-funded entrant in a game in which the best-funded player has already announced he's willing to lose it all to reach his objective? Given Geffen's rather iconoclastic approaches to his work, he may well have some innovative ideas for reviving newspapers that the other two ex-CEOs can't even imagine.This will be an interesting area to watch in 2007.
The video of this morning's appearance by GE Chairman and CEO Jeff Immelt on CNBC can be viewed here .
It runs about 8+ minutes. However, of particular interest to me was the segment at roughly minute 4:30 into the interview. This is where Joe Kernen of CNBC's Squawk Box program, asks Immelt, his ultimate boss, about why GE, as a conglomerate, is valuable.
Immelt rather brazenly says that GE exists 'because the market lets it exist,' or something like that. You can hear the exact quote for yourself at the video link. In defending the conglomeration, Immelt mentions, "performance" and 'common culture, goals....'
Then, to deflect attention from his own failure as CEO to beat the S&P, he now espouses '10-15-20 year' timeframes for the company, insisting that this is how "we view the company."
In other words, Immelt in effect pleads,
'let's all hail the golden past era of Jack Welch, and please overlook the sub-S&P500 performance over the entire tenure of my CEO- and Chairmanship of GE.'
To see what GE's total return performance has been under Immelt, take a look at the table in this blog post which I wrote earlier today.Then Immelt plays the 'oughta, shoulda' game. He says that GE stock "should" go up with oil. Darn those stupid investors, eh? Why can't they price his stock right. It's soooo embarrassing!
As if this theatre isn't comic enough, you have to step back and see what CNBC is asking veteran reporters Becky Quick and Joe Kernen to do. They must, with straight faces, lob softballs at their Chairman in a live interview.
Am I the only person who thinks this is ludicrous and demeaning to Quick and Kernen? Does anyone seriously believe either veteran, capable, sane CNBC/GE online anchor will risk her/his career by being candid and hardnosed with their employer's Chairman and CEO on live network TV?
Does anyone seriously believe either will engage in the following hypothetical Q&A?
Quick: Hey, Jeff.....about our total return since you took over from Jack Welch. Why haven't you been able to beat the S&P500 in 4 out of 5 years? And why has our stock underperformed for the period during which you've been CEO?
Immelt: Good point, Becky. I'm recommending to the board today that they fire me and find someone to run the firm who can actually outperform the returns that my shareholders could get from simply buying a passively-managed S&P500 index fund. I can't, in good conscience, recommend that anybody assume the risk inherent in holding GE as a specific equity, when I've failed to return to shareholders what they could get with such an index fund holding.
Kernen: Hey, Jeff.....about this conglomerate we fondly call "GE." With the annual revenues and asset sizes of our disparate and unrelated businesses, don't you think the corporate function is essentially exacting a non-value-adding tax to pay your enormous salary, benefits and bonuses? Wouldn't investors benefit from spinning GE into its five separate businesses, each with its own listed stock, free of the financial yoke of your corporate functions?
Immelt: I'm glad you pointed that out, Joe. Yes, I think you are right. On second thought, I'll recommend to the board that they dismiss me as soon as I've split the firm into its trimmer, more enterprising separate components. I think I've demonstrated, over the five years I've been CEO, that my staff and I have actually destroyed value, not added any, for shareholders. Please help to stop me before I grab even more shareholder value for myself by underperforming the S&P and getting paid many tens of millions of dollars for it.
Quick: Wow, Jeff. Thanks for that breaking news on GE splitting itself up. You heard it first, here, on CNBC. America's Business News Network.
Immelt: Thank you, Becky and Joe. I'm just glad I can finally confess to being unable to create any consistently superior total returns for my shareholders after five years of being paid tens of millions of dollars to attempt the task. Now, I can retire and join Jack Welch in bidding for an old newspaper up Boston way. Nobody expects it to earn good returns for the shareholders, and it'll be a private equity buyout, so there won't really even be a publicly-available total return to worry about- so I think I'll be well-suited to that......
Well, I can dream, can't I? CNBC is more about entertainment than truth or news. This hypothetical exchange will never occur. However, you can vist my prior posts here, here, and here, to read more material supporting the comments in the hypothetical Q&A above.
As I've written before, though, if such an exchange did occur, now.....that would be news. Not to mention real hardball financial business reporting.
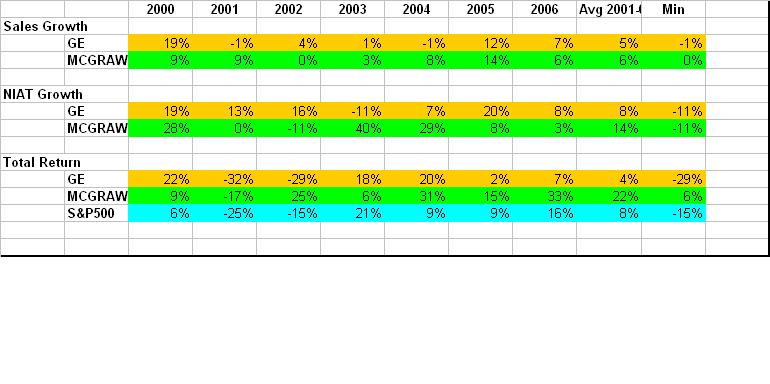
I'm pleased to note that McGraw-Hill is in my (Performance Research Associates) equity portfolio selections this month. As I wrote here, recently, I found that the company's total return performance would merit inclusion, but, ironically, I thought it's occasional bursts of accelerating revenue growth would make it too inconsistent for my portfolio.It just goes to show that you should trust the numbers, not subjective judgment. When my December selections were completed, McGraw-Hill was among the low-growth component of the portfolio.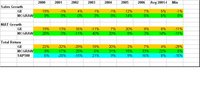 I remain impressed with Terry McGraw's feat. I've repasted my analysis of McGraw-Hill and GE from last month nearby (please click on the table to see a larger version), to provide the reader with recent revenue and NIAT growth, and total return data, for the former.Managing to wring such consistent revenue and profit growth out of this collection of rather modest businesses is noteworthy.
Yesterday's Wall Street Journal carried a feature story describing, in more detail, the events leading up to the dismissal of Julie Roehm, Wal-Mart's recently hired SVP of Marketing Communications.
Without repeating the details of that piece, nor the one preceding it over the weekend in the Journal, I'll just state that Ms. Roehm seems to be the latest victim of the giant retailer's management ineptitude.From the article's recounting of her product development and marketing background, Ms. Roehm seems to be the genuine article, when it comes to getting results with fresh marketing communications approaches. Wal-Mart hired her to support their ill-fated entry into upscale retail merchandise earlier this year.As my partner suggests, and I agree, it looks like Lee Scott is trying to eliminate any trace of the personnel who remind him of the mistaken strategy. Not that Roehm was its architect. She simply came in to execute according to the product strategy playbook they gave her. Julie Roehm may have helped, but, frankly, I've never felt that good promotional efforts can overcome weak product and marketing strategies.The entire ad agency firing flap seems to be a smokescreen as well. More effort to erase all external traces of the retailer's attempted dalliance with upscale consumers.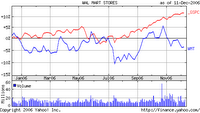 More than anything, sadly, I think this episodes reinforces the strategic mismanagement of Wal-Mart over the past few years. The accompanying stock price chart for Wal-Mart and the S&P500, from Yahoo's site, indicates how badly the firm has stalled this past year.Wal-Mart is simply striking out as it attempts to cope with the limits to its revenue and profit growth. It had a successful model, before saturating the appropriate areas of the US with its stores. Perhaps it will find more success overseas, although it recently retrenched in at least one foreign country. But I don't think the source of Wal-Mart's stock's return to a path of consistently superior total returns lies with its current product and marketing strategies.
Friday's Wall Street Journal's Money section featured an article about how some fund managements are changing the manner in which they compensate brokers for so-called "research." In the wake of the notorious Spitzer settlement years ago, after the dot-com bust, research is now supposed to be independent beyond question.Thus, soft dollar arrangements are becoming more heavily scrutinized. This practice involves the fund agreeing to trade with a broker in payment for 'research.' The effect may be to charge clients more for the trades, while the management gets 'free' research. Nice trick, eh?Fidelity Investments is mentioned at the end of the piece as departing significantly from all other firms in fixing this situation. They have begun to sign deals"in which Fidelity Management & Research- which oversees the funds- pays for research instead of fund investors. Fidelity negotiated flat rates for the research and for the commission rates on the trading- a move known as "unbundling." "I love this. Of course, no other major fund management firms are joining this practice. It would reduce their profits by shifting the costs of 'research' to them from the customers' trading expenses.To me, the Fidelity move makes perfect sense. Despite Spitzer's "best" efforts, research can never really be 'independent.' There is always the potential for an asset manager to somehow compensate an 'independent researcher' to provide beneficial reports on companies whose equity or debt the manager holds in funds. Moving the source of conflict of interest a little further down the food chain will never remove it entirely.However, research properly belongs as an expense of the fund management in providing asset management services to clients. To the extent that it really has any material benefit in the first place. If it had, don't you think investment banks would have charged their other functions, and customers, for the product of the research departments?As one of my investment banking colleagues puts it, 'why not just call it "marketing," since that's what "research" really is.' That is, it becomes a crutch which managers use to justify their selections, if they are not sufficiently confident to simply accept responsibility for them in the first place.Still, Fidelity's move at least puts the customer first, and makes Fidelity sure it wants the research it uses, because it's paying cash for the service.
My friend and sometimes-colleague, B, emailed me today regarding this recent post about the market values of BofA and CitiGroup.
I failed, in that post, to reiterate that B had predicted this state of events as long ago as 1996- ten years ago. In a phone conversation at the time, so vivid in my mind that I can still recall where I was sitting during it, B foresaw the merger of the major US banks into no more than three super-sized financial utilities. He predicted that they would re-integrate all of the business lines previously spun off or weakened by decades of mediocrity- mortgage banking, credit cards, investment banking, etc.
In that respect, he is the clearest-seeing and perhaps best strategic mind with which I am acquainted.
He further opined, once again correctly, that they would not fare well in terms of total returns. He has mused, and we discussed, how much better it might be for the banks to simply cede simple deposit business to some governmental agency, in order to remove the safety of that business from association with the riskiness of the modern, integrated financial utilities.
Specifically, he wrote to me this morning (because his identity is concealed, and the passage is not unduly specific, I doubt he will mind my quoting from it),
"Remember my model projected that the huge financial supermarkets would resemble large government organizations lacking innovative spirits and laden with beaureaucratic activities. Their size and lack of a usable collective gray matter harnessed to the business is rapidly assuring that this will happen. Ultimately, perhaps the behemoth banks will become government regulated utilities, with at least the benefit of not compensating their senior executives as though they were being rewarded for taking the business-required personal risks that goes with productive innovation."
Now, as if things aren't sufficiently mediocre, we have this rumor concerning BofA and Barclays merging. Talk about cultural clashes!
I'm sure the pundits and investment bankers are all salivating at the prospect of two large, non-overlapping financial institutions being wedded for enormous attendant transaction and advisory fees. To what end? Does anyone truly think that such a combination is likely to earn consistently superior returns for the integrated entity?
As I write this, I am listening to CNBC's coverage of Citigroup's ineffectual solution to its performance problems. A new COO has been named, but Chairman Chuck Prince is being left "in charge," if that is the right term for describing his tenure.Blogger is, once again, being uncooperative in pasting in stock price charts. However, if you look at Barclays, Chase, BofA, CitiGroup, and the S&P for the past 2 and 5 years, you will see that the pack of financial supertankers move together, with Citi being the worst-performing. I note this by way of refuting what Larry Kudlow just proclaimed, which is that BofA and Chase are now 'coming on strong.' In truth, as my friend B prophesied, they all move pretty much in lockstep, because they are all pretty much identically-structured and managed companies now.Another merger? Sure, why not. The year 2006 is going down in history as a mega-deal sort of year. Why not end it with another one?
Last Thursday's Wall Street Journal recounted the saga of an ex-Fannie Mae manager, Thomas Inman. He believes he is a 'whistle-blower,' reporting his former employer's failure to acknowledge his findings of accounting inaccuracies.The company, however, has a different story. Several other employees explained that Inman 'uncovered' some items which were already known. Furthermore, it appears that these other items were the focus of other teams, not the one to which Inman was tasked.It's impossible to tell from the article who is right, Fannie Mae or Inman. However, Inman was dismissed from the company after just six months. Again, it's hard to tell who is telling the truth, or, perhaps, the truth as they see it, even from this.What struck me about this story was how familiar it is. Haven't we all known someone in a company in which we worked who seemed to be a bit too passionate and concerned about areas with which they were only tangentially involved? People who seemed to be on a crusade about something, even if it wasn't their actual job? Maybe even losing focus on their assigned responsibilities?That's always the case, it seems, with whistleblowers. They might be telling the truth, and publicizing something their employer would rather conceal. Then again, they might be the occasional O/C employee who simply will not listen to reason, accept reality, and focus on their own job.It's probably Fannie Mae's problems which occurred under the shameful watch of Frank Raines, that have brought this story to the Journal's pages. Anything hinting of further coverup at the image-impaired mortgage lender now gets attention.Still, to me, something seems odd about Inman's tale. With several other Fannie Mae employees, including the General Counsel, going on record to assert that Inman is wrong, I am inclined to doubt the ex-employee. It's not just a faceless spokesperson stonewalling questions about Inman's allegation. Some fairly detailed counterpoints were mentioned in the article.It ought to remind us that sometimes, the lone employee crying "wolf" is, in fact, one of those we have met elsewhere, continually seeing conspiracy and fraud in other corporate functions and processes.
Monday's Wall Street Journal's "Theory & Practice" column featured a concept known as "net promoter." According to columnist Scott Thurm, the concept is "advocated by consulting firm Bain & Co., market researcher Satmetrix Systems, and author Fred Reichheld." Reichheld is a director emeritus at Bain & Co.
Apparently, the essence of the concept is to assess, on a 0-10 scale, customer responses to the question,
"How likely is it that you would recommend us to a friend or colleague?"
The high values (9-10) are "promoters," middle values (7-8) are deemed "passives," while the lower values (0-6) are considered "detractors." A "net-promoter score" is determined by "subtracting detractors from promoters." Whether that is in aggegrate, then taking an average, or by some other method, is not specified in the article.
In his column, Thurm discusses an emerging debate regarding whether or not the net promoter concept is effective for predicting revenue growth and "other customer satisfaction measures." A Neil Morgan, assistant professor of Marketing at Indiana University, is quoted as saying,"Does this thing predict business performance (my bold) or not?....There is no evidence that it does."Without an explicit and defensible definition of "business performance," I'd say Mr. Morgan's comment is rather obvious, wouldn't you? The article goes on to state that Reichheld claimed, in a book, that, "on average, a 12-point increase in a company's net-promoter score doubles its growth rate." Apparently, Bain has now backed away from the claim. Not a good sign, eh?Among the measure's supporters is, we are told, no less than Jeff Immelt, the continually-underperforming CEO of GE. This alone would make me suspect of the concept. Foundering large companies are not the best place to look for testimonials on a new management concept. When combined with the Bain backpedaling, I'd take this concept's value as a quantitative, or explanatory variable, with a grain of salt.What I find curious is why nobody has thought to study the relationship between promoter scores, net-promoter scores, and total returns. I'd have to know more about the time dimension over which one can apply the promoter scores before associating it with a company's consistency of superior total return over time, but the question interests me greatly.As a marketer by training and initial business experience, I find the basic idea interesting, and potentially useful. However, even after Googling the term "net promoter concept," and reading through this Bain webpage, I am at a loss as to know precisely how one "subtracts" the promoter scores from the detractor scores. Are they averaged? Normalized? Over what sample size? Time period?The Phelon Group, mentioned in the Journal column, describes its own proprietary approach to operationalizing the concept here.To simply measure a sort of 'recommended buy/rebuy' rate, at the extremes, where really passionate advocates or detractors will operate, makes intuitive sense. But, to quantify the effect, I would think you'd need to relate it, once you understand how to actually work with the measure, to a company's overall success in creating shareholder value over time, i.e., consistently superior total returns. It seems, though, at this point in time, that the mechanics and interpretations of the basic measure still constitute what might be termed an "art form."Regardless of which method one uses to operationalize this concept, I would reserve judgment on its being anything more than another passing fad, until I see some solid research relating it to a company's ability to consistently earn superior total returns for its shareholders.
Today's Wall Street Journal contains an article reporting on the Yahoo reorganization announced yesterday. For what it's worth, the story didn't make any of the three major columns on page one. Nor the top half of the stories listed in the center columns "What's News." Nor any editorial regarding the major shake-up.
Late last month, I wrote a piece commenting on the recently-publicized internal strife regarding Yahoo's lackluster performance. Back in August, I wrote this one, which highlighted the firm's strategic malaise. In that light, I would have to say that this reorganization looks bad. Gender notwithstanding, I think it's rare that having a CFO become a major operating executive is a good thing for a growth business. Yet, this is what Semel is doing, by adding line responsibilities to CFO Susan Decker's plate. Most CFOs, if they are good at what they do, don't really have a growth or creative mindset. If they do, then what the heck are they doing in a sombre suit (or dress/skirt) as CFO?
Further, the mass exodus of top managers notwithstanding, Terry Semel, who brought you these past years of wayward performance, is still running the show. This looks very, very bad.
The best that the Journal could come up with about Decker is a Yahoo spokeswoman's remark,
"If anyone can do it, I'm sure it's Sue Decker."
Well, what else would you expect a company spokeswoman to say- "We're not expecting much, but she's already here, so, what the heck?"
Rather, the WSJ piece is decidedly guarded on its review of Decker's career. As I contended last year, regarding GM and Ford, and, on an ongoing basis, GE, I smell the whiff of 'careful what you write about this person, she may soon be CEO of a large, if mediocre, online corporation from whom we'll want advertising, and to whom we'll want access.' The report is full of pulled punches about Decker's lack of any past operating success, much less experience. And that she is, basically, a one-time equity analyst cum corporate finance functionary.
In her new position, Ms. Decker will be responsible for Yahoo's "main revenue-generating activities, including its sales of online advertising for Yahoo and partner sites." The move is reported to be, in some observers' opinions, "a test of her fitness to succeed Chief Executive Terry Semel, 63 years old, upon his retirement."Blogger is not cooperating with my attempt to paste a Yahoo-sourced (ironic, yes?) chart of stock price performance for Yahoo, Google and the S&P500 for an extended time period. It shows that, for the five years since Semel took over the firm, it has not actually outperformed the index, thanks to a precipitous fall in the stock price back in 2001. Since Google went public, it has easily outperformed Yahoo.Thus, one might question whether any parts of the Semel-led team are capable of fixing what is wrong with Yahoo. As the 'peanut-butter manifesto' alleged, supporting my earlier observations, the firm has a mediocre presence in many online areas, but a commanding one nowhere.Will Susan Decker and Jeff Weiner be fixing this shortcoming?With problems of the scope and duration that Yahoo has, it's telling that the board did not intervene to replace Semel and his team with a new, more creative crew which is not wedded to the firm's past errors.As it stands now, this reorganization, with Semel still in place, looks like rearranging the deck chairs on the Titanic.As always, time will tell. Glad I'm not a passenger on this voyage.....
Last week, the Wall Street Journal ran a feature article concerning the private research coordination business founded and managed by Mark Gerson.It reminded me of a one-time analyst and money manager I knew years ago who broke into the business in a similar way. Though his network of contacts among retail packaged goods salesmen, he had access to what was, at that time, essentially instantaneous field sales reports. By offering his analytical services free for a few months, he secured a prized research post at a mid-sized broker.Gerson's business does this on a larger scale, by brokering purveyors of such private intelligence, with those who would like to have it, but don't know the right people. Among his clientele on the buying side are, apparently, legions of hedge funds, who want up to date information on grass roots sales results and field performance of various products and services.Some way into the piece, the author quotes a private investment firm's partner as saying,"What's in the public domain is worthless in terms of making money."Strong words, indeed. And, as it turns out, wrong.My own experience, using only Compustat data, is that an effectively constructed equity strategy can consistently outperform the S&P500 without using 'private' data. The equity strategy that I have built, refined and managed over many years has consistently outperformed the index, using only Compustat-sourced data. A look at some of the information on the companion website to this blog will give you some idea of what I mean.My guess is, the investment firm partner who was quoted in the article focuses on very short time periods, and is primarily involved in trading, as opposed to investing. It never fails to amaze me that so many institutional 'investors' feel they must have 'non-public' information, in order to outperform the market.Rarely, it seems, do investment managers consider building more potent selection processes, which incorporate understandings of the investors' behaviors, as filtered through market outcomes. Perhaps because, as author and fund manager James O'Shaughnessy points out, so few people are disciplined, the concept of consistently using an approach which is carefully developed to take investors' behaviors into account is simply unworkable. Their animal passions and emotions take over, negating whatever value there is in allowing a well-developed selection and management strategy to operate as intended.It has continally surprised me that one can outperform a major market index simply by carefully, consistently observing and processing regularly-recurring public data. You'd think that anything so widely available would necessarily have no value, as the quote's author seems to think.However, the reality seems to be that, with so much data about companies and markets available, knowing just 'which' data may provide key insights is less obvious than you may think. And knowing how to evaluate, or analyze it, appears to be more arcane than you might think, as well.
In this weekend's article on Kirk Kerkorian, the Wall Street Journal quoted him on the topic of diversification as saying,
"Diversification is for people who aren't sure about what they are doing."
This caught my attention, because my portfolio periodically becomes concentrated in companies in certain sectors, causing consternation among potential investors.
For example, several years ago, as the housing market was in a healthy growth mode, I held a significant percentage of the portfolio in several home builders and financing institutions. While discussing the strategy with several representatives of investing institutions, I was criticized for this concentration. My explanation that was unlikely to earn above-market returns simply through diversification fell on deaf ears. As Kerkorian observes, these people, not being investors themselves, but merely analysts, were more interested in risk avoidance than actually earning returns.
A similar situation exists when hedge funds engage in long/short allocations. That is, they may only be 70% long, and 30% short, in order to, they believe, mitigate risks of extreme losses. I have had discussions with people at such funds, who have told me that any all-long or all-short positions add no value over that of a mutual fund. To them, apparently, the value of a 'hedge' fund is in the hedging.
In reality, though, the proof is in the performance. If one is confident that a market environment is supportive of an all-long position for one's strategy, then one should be long. In that respect, I feel that Kerkorian's view is correct. Managers often hedge because they are simply unsure whether to be long, or short.I think that sometimes, people can make a situation far more complicated than it need be. Kerkorian's remark reminds us that it's not always necessary to diversify. There are times when you have a specific objective, knowledge of a situation, and are able to reap profits because of your concentrated efforts, rather than diluting them via diversification.
Friday's exit by Kirk Kerkorian from GM stock should really worry and frustrate shareholders. It isn't often that an investor of such pedigree becomes so disenchanted with management that he simply walks away from his investment.
I was particularly struck by a quote in one of the Wall Street Journal's articles. It had GM director Armando Codina asking,
"Who does this guy from Las Vegas think he is, telling us what to do?"
 This is simply incredible. Perhaps a more important question is,
"Who does Armando Codina think he is, and what does he think he's accomplished as a GM director to create value for the shareholders he represents?"
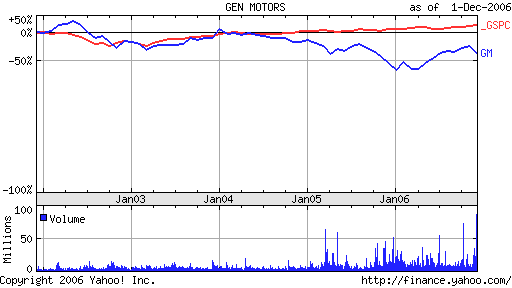
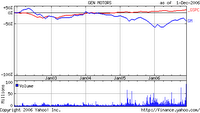
As the nearby Yahoo-sourced five-year price chart for GM and the S&P500 shows (click on the chart to view a larger version), GM was going nowhere for years before Kerkorian showed an interest in the firm. The only significant uptick the company's stock has shown was after the billionaire showed signs of sustained interest in contributing to GM's long-term "turnaround."
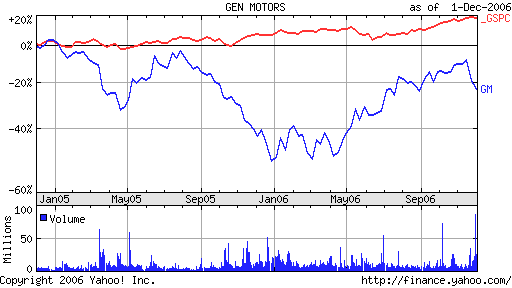
 If I were a GM shareholder, I'd be bolting too, now. The stock was down significantly as Kerkorian pulled the last of his money out of the troubled auto maker. This six-month price chart shows how the stock lost twenty percentage points of gain in November, ending the month even with the index for its six-month performance.
To answer Codina's question, though, Kerkorian, and his sometime-lieutenant, Jerry York, significantly contributed to the rescue of Chrysler by restructuring it and selling it to Daimler-Benz, profiting roughly $3B in the process. So, just on past performance, one would tend to bet on Kerkorian over Wagoner and his board.
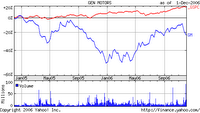 Over the last two years, the company's stock price has behaved like a roller coaster. Rather than listen to York, who was given a seat on the GM board, and Kerkorian, Wagoner played a game of "chicken" with the savvy investor. Now, the shareholders have lost. An investor with a legendary touch for making money, and a genuine interest in the company, and its sector, is gone.To me, Kerkorian has behaved as a sort of modern-day J.P. Morgan. I mean that in the best sense, as a compliment. He has seen industry restructuring potential where the current CEOs have seen only discomforting change. By considering broad-scale integration of GM and Nissan/Renault, Kerkorian offered shareholders a chance to have a stake in an auto maker which would have had the management talent and market share size to survive, and maybe prosper, in a long-term slugging match with Toyota.Now, all shareholders have is Wagoner's tired, conventional attempts to stave off disaster. Last week, ironically, the company completed the sale of its controlling interest in its financing arm, GMAC, thus selling the last of the family jewels. With this cash, and the loss of the continuing profit stream from the finance unit, GM has more than mortgaged its future- it simply sold it to for continued short-term survival.According to various media pundits, Kerkorian may return when GM has suffered sufficient losses for the directors to come to their collective senses. But, given their rebuff of York's suggestions this past fall, one wonders if there will be enough time and money left, whenever that moment comes, for even Kerkorian & Co. to wring value out of what will be a then much-weakened GM.For now, though, Rick Wagoner is in possession of the field, having seen off both Carlos Ghosn's and Kirk Kerkorian's attempts to help GM shareholders survive the next few years of difficulty.
Wednesday's Wall Street Journal carried an article on Hormel's attempt to "Add Upscale Foods Without Alienating Lovers of Its Spam." In short, to broaden its product line and stoke growth without screwing up its brand identity.
What struck me about this was a quote by Hormel's lawyer-turned-CEO, Jeffrey Ettinger,
"Hormel stands for canned ham, bacon and more traditional products. We don't want to harm these items with the target consumers."
Well, score one for Mr. Ettinger getting half of the concept of branding right. Unfortunately, the article begins by describing the company's failed attempt to market ethnic foods of restaurant quality.
The piece also lists the components of Spam, and how it is actually made. I won't go into the details here- if you're interested in them, wait a couple hours after eating, then go read the Journal article. Suffice to say, it is hard to see how a company which has staked its brand on a product like that can actually believe anyone would also buy haute cuisine from the same kitchens.
As I wrote here in September of last year, about Les Wexner's Limited Brands strategy, Hormel could simply create a new brand identity for these upscale offerings. For example, Frito-Lay acquired Stacy's Pita Chips last year, as described here. The announcement states,
"Stacy's, which will continue to be based in Randolph, MA, with more than 100 employees, is planned to operate as a separate unit and report to Frito-Lay North America chairman and chief executive officer Irene Rosenfeld."
I Googled Stacy's Pita Chips and had to search through two screens to learn who the acquirer was. I was aware some large food company had acquired it, but could recall which one. It is nowhere to be seen on the Stacy's packages.
Why can't Hormel do likewise?
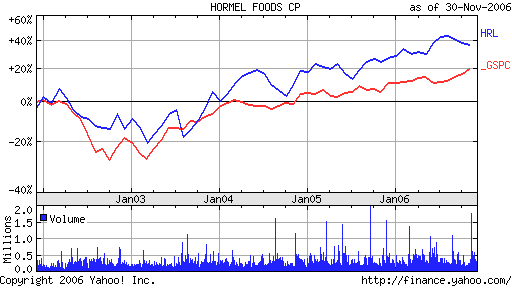
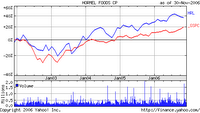 As the nearby Yahoo-sourced, five-year price chart of Hormel and the S&P500 shows (click on the chart to view a larger version), the company has actually done rather well over the period. Most of its outperformance seems to have come from its sagging far less than the index when the technology bubble burst at the beginning of this decade. However, it has at least kept pace with the S&P, which is no mean feat.I think the WSJ piece illustrates the pitfalls of listening to CEOs on media venues such as CNBC, and presuming each of them knows what he is doing. Ettinger has had the job only one year, with no external candidates being considered. Taking Hormel into more 'natural' processed food niches would not seem to be a brand-enhancing strategy. Witness Wal-Mart's floundering with its new upscale fashion merchandising strategy this year.Instead, Hormel should probably stick to more brand extensions for Spam, as it has been doing. The company seems to know this consumer segment of older males well, so mining it further is more likely to bring profitable sales than going after young ethnic mothers.Why is the fundamental concept of branding seemingly so difficult for companies tounderstandd? Why do CEOs and group managers attempt to make a successful brand straddle multiple segments which have differing buyer values? How do managers who do this wind up as CEOs?Now there's a question for those interested in shareholder democracy and corporate governance.
There seems to be a lot of media-generated hoopla this week over the increase in Bank of American's market capitalization to exceed that of CitiGroup.
The Money and Investing section of the Wall Street Journal even carried an article yesterday with a chart box headline reading, "There's a new No. 1." CNBC had a special segment featuring Jim Cramer opining on which bank to buy. The network covered the mock "choice" with great fanfare.
To me, this is a silly contest of size between two financial utilities with more similarities than differences. Size of this sort can, and was, purchased. Especially by BofA, which is, in truth, NCNB (which became NationsBank) of Charlotte, which bought the right to rebrand itself with the storied name and logo of the San Francisco takeover victim.
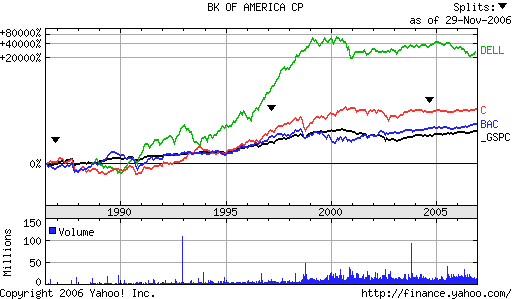
 First, let me go on record as stating that the only measure that matters is a longish-term total return for shareholders. As a quick approximation of this, here's a Yahoo-sourced price chart (please click on the chart to see a larger version) of BofA, Citi and the S&P500 for nearly 20 years.
I thought it would be interesting to look at how similar the change in stock prices have been throughout the long period. Since 2000, there hasn't been all that much difference in the slopes of the curves for the two banks. It's clear that whatever outperformance Citi has enjoyed came in the 1998-2000 timeframe.
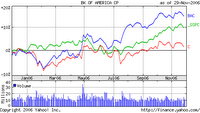 For clarity, though, here's the same chart, for just the last five years. BofA is clearly superior at having generated superior total returns. It confirms, in greater detail, that Citi's best performance period was more than five years ago.
All this is somewhat interesting, but perhaps misses the point. In five years, the better performing bank of the two only returned roughly 15%, total. Plus dividends. CitiGroup is a little better than flat, and worse than the S&P.
With a performance like this, maybe something should change at Citi.
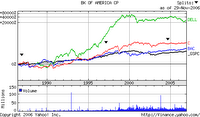 To put this in perspective, let's look at how a fallen growth stock stacks up against these two "large" banks.In this chart, I've added Dell to the earlier long-term comparison of Citi, BofA, and the S&P500.It sort of puts things in perspective for me. All this hue and cry over which bank is larger seems, for me, to rapidly fade into the background, as I see the much larger gain in stock price in Dell over the period. The two banks are literally not even in the same league. Not even after Dell plateaued six years ago.As an investor, I can't say I even care which bank has which market cap. Both have such anemic returns over the last half decade that I doubt my strategy's selection process would include either company in my equity portfolio.Yet another case of entertainment trumping news. The 'news' being, no matter which firm is larger, or how large they get, they still can't deliver consistently superior total returns for their shareholders. If one of them could? Now that would be news to me.
There seems to be a run on the New York Times group, or parts thereof, by retired or 'removed' CEOs.
First Jack Welch & Co. want to pry the Boston Globe away from the company.
Now we learn that AIG former-CEO Hank Greenberg is building a position in the parent company.
What gives with these ex-CEOs going after the NYTimes?
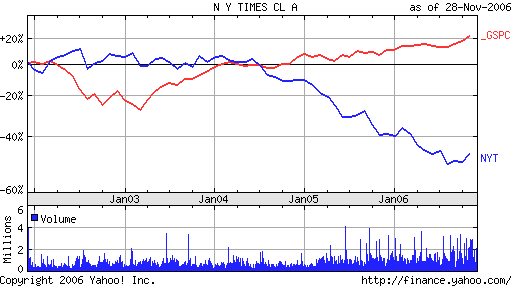
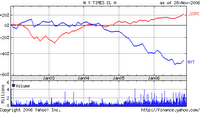
I've pasted a Yahoo-sourced price chart of the NYT vs. the S&P500 Index for the past five years (click on the chart to view the enlarged version). It isn't pretty. The newpaper group is down more than 40% over the period, while the index has risen roughly 20%, for a 60 percentage point difference.
Revenues are shrinking, as are profits. Over the five year period, revenues have oscillated, but finished essentially flat, while profits did about the same. Except for a recent, severe dip.So, why the sudden interest by Greenberg and Welch in these basket case newspapers? Has nobody told them what Google, eBay and Yahoo are doing to the classified ad business of newspapers, as well as general print advertising? Are they unaware that many people receive their news online now, rather than reading a daily paper?What would have to happen to turn these papers around? What is it Welch and Greenberg bring to the table that is missing from current management, or anyone else?I am genuinely curious about why the sudden rush to either buy or dismember the NY Times group. Is it all charity and philanthrophy, to save the jobs of pressmen and beat reporters? Or do Greenberg and Welch see profits where nobody else does?
Yesterday's Wall Street Journal featured a special section on home entertainment. The lead piece focused on Apple's dominance of digital music distribution.According to the article, iPod/iTunes holds a 71% share of the market, while EMusic is second, with only 10%.I can't recall that last time I bought a full-priced CD in a retail store. The last time I bought large numbers of CDs was over six years ago, from the now defunct website, CDNow. That's how much Apple has changed the experience of buying, and playing music.The main point of the Journal's piece on digital music was that none of the also-rans to Apple are trying to take it on directly. Through various approaches involving monthly fees, limited play of free copies of songs, most competitors hope to attract users willing to adopt a different music purchase and/or listening system.Only Microsoft's Zune is configured to be just like the Apple iPods. That is, the pricing and general content acquisition models are similar. However, the Zune is much bulkier than the iPods, looking as if it had been rushed out prematurely for this Christmas season. The article quotes an analyst as believing that Microsoft is the only company capable of taking on Apple directly with a nearly-identical system for music distribution and playing.Looking at the 'music leasing' model of several iPod competitors, I wonder how many of those users feel like I do, and want to own their content? I've never personally been interested in paying to lease music I like for a few months. So, realistically, with such high market penetration by Apple already, I doubt any of them have much long-term potential to earn consistently superior returns with their strategies.As for Microsoft, I see their Zune offering as similar, in a corporate sense, to their XBox division. Microsoft is slowly creating standalone product groups to create new hardware which will pull software along with it. As such, these new groups could just as easily have had different logos and corporate names, even if funded by Microsoft.This is very close to my earlier recommendations for just such a split among the company's disparate units.However, since they remain as Microsoft groups, I can't help but wonder if their potential to earn total returns is lost among the still-huge revenue streams from conventional PC software sales. For all the hype about new directions at Microsoft, and new blood, their corporate form pretty much guarantees that most new initiatives won't be sufficiently large to move the share price, and, thus, total return, needle.Apple by contrast, has a 70% total return just from July. Their nimbleness and focus on growth-oriented product markets is resulting in a much better experience for their shareholders.From what I read in the WSJ yesterday concerning digital music, I don't see any competitors dethroning Apple any time soon. So many consumers have already bought and stored music in the firm's proprietary format, that I just don't expect they will have compelling reasons to switch brands in the near future.
The Saturday/Sunday edition of the Wall Street Journal is typically rather lightweight in content. My partner is of the opinion that much of the edition is filler that wouldn't make the weekday paper.
However, this weekend's "Breaking Views/Insights on Investing" discussed the recent Blackstone private takeover of Equity Office Properties from the perspective of bubble investing.
I admit to having forgotten how the Federated/Campeau fiasco drove then-independent First Boston into the arms of Credit Suisse. The American investment bank had funded Campeau's takeover of Federated stores with a bridge loan which it held, anticipating syndicating the loan among other institutions. First Boston proved unable to do this, and, thus, took the loss as Federated went bankrupt in 1990.
Sixteen years is a long time. Now, Blackstone Group is paying $36B in the largest private equity takeover of all time. According to the WSJ piece, Goldman Sachs and Bank of America are risking some $3.5B of their shareholder's capital by holding a block of the deals equity.
I'm not familiar with the economics of the underlying transaction. Perhaps Blackstone feels that commercial property has bottomed, and now is the time to buy. Or perhaps it just feels that the outlook for commercial property rents and appreciation are more attractive than the market does. Either way, it's a very large move.
Leaving two publicly-held banks, Goldman and BofA, with 10% of the deal's financing of which to dispose, seems peculiarly risky. This is the sort of thing, as the Journal article reminds us, that goes bad in an instant, with no way to recoup the losses. The reason the authors give for this funding move is simply that the fee income from funding this deal is enormous.
That this is an attractive alternative for the two firms suggests the extent to which they now feel they must take capital risks in order to generate income.
And, of course, it probably won't take much of a shadow of uncertainty to cloud the deal's fortunes such that the 'equity block' that these two companies hold declines by far more than the amount of the fees they're booking.
As always, time will tell.......
The recent USAirways bid for Delta has sparked quite a bit of business media comment. Holman Jenkins wrote a good piece on Wednesday in the Wall Street Journal.
Essentially, he notes that US Airways CEO Doug Parker's proposed acquisition "might have been inspired by the old joke about two hunters trying to outrun a bear."
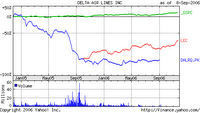
Just so. As the Yahoo-sourced chart of US Airways', Delta's, and the S&P500's prices for the past two years (click on chart to see an enlarged version) illustrates, It is not a merger of two strong competitors.
Delta is in bankruptcy. US Airways is somewhat difficult to track prior to a year or so ago, when, thru a merger, the price trail was more or less obliterated, as America West took US Airways' name.However, in the past year, US Airways has clearly outperformed the S&P, while Delta languishes. Contrary to the pundits who declare that most desirable airline mergers combine non-overlapping airlines, this one promises to help remove excess capacity in similar markets. Which, of course, should firm up pricing for US Airways. Additionally, as Jenkins noted in his piece, it leaves the merged airline with slots at Kennedy and O'Hare, where new entrants have difficulty obtaining gates.So much for the value of the merger.However, the larger issue, to me, is competition in an industry in which so much of the business model is either shared and in common with competitors, or easily obtainable, thus lowering barriers to entry.Specifically, all airlines must, of necessity, use the same airports. Thus, they rely on shared airport management, the FAA, baggage systems, and, in some cases, reservation systems. Anyone with money can start and airline and lease planes from the usual suspects, including GE Capital.Thus, little is left in the control of an airline's management to actually make a sustained difference to customers, for which the latter will pay revenues that drive a consistently superior total return in the market.I've pondered this sector for some time, as Southwest Air is, to my knowledge, the only airline ever to be selected, using my quantitative, disciplined process, for my equity portfolio.This proposed merger does not alter my view. I think in the current market structure, a focus on building a regional strength, with low costs due to common equipment, for maximum use of crews and low training and maintenance costs, are key. The hub and spoke system probably means there are regional physical barriers to airline growth, if the company wishes to enjoy any significant period of consistently superior total returns.Moving beyond that typically sees an airline struggle with expensive logistical issues and traffic feeder/load factor issues.It could well be, thanks to the structure of this sector, that its players are simply unlikely to earn many years of consistently superior total returns.
Yesterday's Wall Street Journal announced the pending deal between Comcast and Disney, in which the former would distribute the latter's video content.
In this prior post, I've opined that Comcast is aiming for a very narrow window with this online content distribution strategy. Overall, I think it's a mistake.
Now, with my recent posts about Yahoo, management buyouts and pension plans recently echoed and supported by major media pundits, and my year-old warnings about GM and Ford now routinely substantiated, perhaps Comcast is my one forecasting mistake. It's too early to tell yet.
In discussing this with my partner, I asked, what would have to happen for Comcast's move to be correct, profitable, and lead to consistently superior total returns over the next few years. Blogger is not cooperating with my attempt to paste a stock price chart for the past 5 years for Comcast and the S&P500. It would show that Comcast has been up and down, with a net performance that is essentially flat, and below the S&P.
My guess is that viewers would not look directly to content producers on the web, and content producers, or the various existing 'channels' on cable, would not open up shop with URLS on the web to sell programming directly to viewers.
Comcast does seem to have scored a coup in getting Disney content for its on demand services. But isn't some of that already available, 'on demand,' on Disney's own site, or iTunes? Note that no part of this deal with Disney is "exclusive." And it is purported to be worth $1B to Disney.
For just a moment, let's stop and give Bob Iger yet more credit for being a very astute CEO. I think I am hoping Disney enters my portfolio selections soon. Iger just got a cable company to pay him for content that, when it appears on a cable channel, he has to pay them to take. And he didn't even have to agree to anything exclusive.
OK, back to Comcast. With iTV scheduled to arrive in the late Spring, it should be technically feasible for viewers and content producers to use the internet as it is best used- a direct, totally-disintermediating approach that allows the viewer and content producer to do business with each other. There will probably also be software vendors offering easy-to-use, web-based products which coordinate the viewer's preference, online availability of content, and the programming of iTV and whatever competitor products meet it in the marketplace.
The question is, how many people will be very late adopters, even with such tools available, and look to Comcast for their total viewing needs? And, moreover, switch to Comcast digital on-demand to get these programs?
Would it not seem reasonable to assume that most people for whom this would be attractive either already have digital on-demand, or buy premium channels from Comcast? Doesn't this new supply of Disney content in some sense constitute free new offerings for existing digital customers? How many people will actually buy Comcast digital just for these new Disney offerings?
If this were an exclusive distribution deal, I'd be a whole lot more inclined to believe it will make a huge difference for Comcast. As it is, I believe there are enough other distribution outlets from which to view much of this content, as to make this Comcast deal far less than one which will materially contribute to its ability to earn consistently superior returns for its shareholders.
It seems to be the week for the business media reporting stories that I wrote about far in advance.This time, it's a leaked memo from a Yahoo SVP regarding the company's inability to dominate any of the many areas in which it has invested over time. I wrote about that in several posts, most notably here. I wrote, "Yahoo blasted onto the scene with a dizzying variety of services, but no clear focus. It seems to offer a bit of everything, and the best of nothing."This is essentially the thrust of the now-famous "Peanut Butter Manifesto," written by Brad Garlinghouse, and reported in Saturday's edition of the Wall Street Journal. It echoes almost exactly my sentiments in the linked post.There's not a lot new to say about the issue, except that Google's stock price broke above $500/share today, which marks a significant P/e multiple for that company.Suffice to say, reading the WSJ story gave me renewed confidence in my strategic diagnostic skills and instincts.A third story ran today, though, in the Journal, that is a bit different, and the subject of the next post.
In prior posts, here and here, I have written about the mistakes unions made years ago with pensions, and the conflicts of interest of managements as they lead buyouts of public companies. Recently, the New York Times has published pieces echoing my thoughts from months ago- September of 2005 for healthcare, which is similar to the pension debacle, and August of this year for buyouts.It gives me a very good feeling to know I called these issues far in advance of one of the nation's leading newspapers. It's even better to know I have an even simpler solution than the one proposed by the NYTimes writer concerning buyouts.Joe Nocera wrote "Resolving to Reimagine Health Costs," which focuses on the third-party payer health care mess. My contention is that pensions are essentially the same thing, in terms of accepting promises to pay from a company which is, typically, an adversary of the worker's union. Similar to accepting non-cash value from a company for health care, accepting promises in lieu of cash for pensions also makes for distorted decision-making.Two days ago, Andrew Ross Sorkin wrote "Rewriting the Rules for Buyouts," recommending a complicated process by which a majority of minority shareholders should have final say in the approval of a management-led buyout. I believe my idea, expressed in the second linked piece above, is both simpler and allows for greater shareholder choice. Simply allow any shareholders to be part of the buyout, if they so choose, on the terms of the offer. This would insulated them from any supposed bad effects of being forced to sell out to the going-private group.Given this past week's flurry of ever-increasingly large buyouts, such as Clear Channel and a large REIT, the issue is still relevant.Since I hope to identify trends and challenges which are developing in business, and affect companies' abilities to earn consistently superior total returns, it's very gratifying to know I identified these issues long before a major news and opinion organization like the Times got around to them.
Saturday's Wall Street Journal featured an article on the current generation of online banking. It brought back memories from my days at Chase Manhattan Bank in the 1980s.
To be sure, twenty years is a virtual eternity in a technology area like this. When I arrived at Chase, Citibank had recently discontinued its own home banking project, which included script that one would print out as "money" on a home printer. Back then, the biggest obstacle to "home banking," as it was then known, was the inability to simply use a personal computer as an ATM.
Chase had two separate electronic banking groups operating in the mid-1980s. Believe it or not, we lost money on every customer in the "online bill paying" product. That was because the customer entered the electronic bill payment, but Chase had a roomful of low-level employees writing checks on a Chase account to physically send, for the customer, to the payee.
Oh, how times have changed!
The WSJ piece rightly points out that online, home or electronic banking- choose your preferred name for the service- tends to wrap you up in the bank's clutches in a rather irreversible manner. As such, by making you captive, their economic propositions, in terms of loan rates, terms, deposit rates, etc., will tend to get a little worse, since you can't easily leave the relationship.
This is one reason I don't personally participate in online banking. Although, I admit, the potential to manage cash disbursements to the day is vaguely appealing. Then again, I have worked at a bank, and am aware of the culture of finger-pointing and unaccountability when an error is made. Heaven help the poor customer who tries to manage cash flow by timing payments closely, and ends up late on the mortgage or utility accounts, thanks to uncontrollable network problems.
I was also struck by the popularity of third-party, omnibus account aggregator services, which allow all ones disparate financial institutional relationships to be presented, online, in one place. On the plus side, this keeps each institution at arms length. On the minus side, you risk a lot of security with an essentially unregulated, reporting and processing vendor.
According to the article, electronic customers are 27% more profitable, and online bill paying has now risen to a 15% market share, from just 4.8% in 2001. As many as 40% of US households now do some online banking.Which brings me to the point of this post. As the piece suggested, online banking is now moving into the phase of differentiation. Banks need to provide distinctive assortments of offerings online, in order to gain some advantage from it.Does this not begin to resemble the earlier eras? More technology expenditures to gain new users and share, moving the user base from early adopters to late adopters? Will these later users, perhaps including me, open more accounts and provide more profits due to online usage?It's an interesting intellectual and business question. Investments are made on the profitability and usage data of current online banking customers, but the eventual drivers of such numbers will be the masses of customers which banks hope will migrate out of branches and onto cyber connections.Granted, there is a likely cost saving in servicing accounts online. With ATMs probably accounting for most cash transactions, online banking offers the promise of dispensing with an avalanche of paper check processing for large banks. But will these profits be offset by communications and technology expenditures? Will the online services be free? My guess is, eventually, "yes."All of which confirms my continuing view of these mega-banks as the financial super-utilities that my friend, B, foresaw in 1996. I would not bet that any one bank will see its total returns rise over time on the back of online banking. They might not fall too far, due to the cost savings, but I'm guessing that significant revenue gains won't come from this area. And, in the end, the easiest way to earn consistently superior total returns is to engineer consistently superior revenue growth.
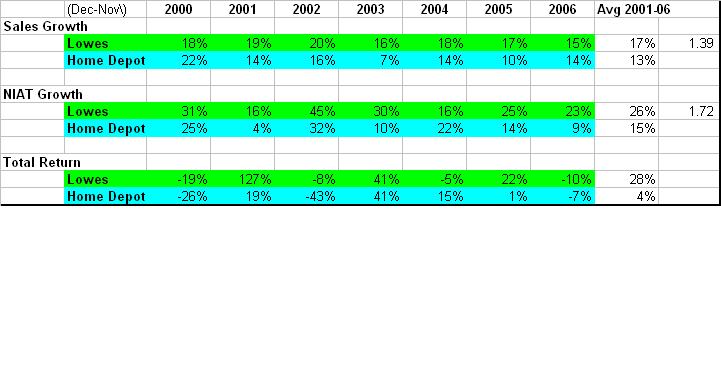 Really? Look at the chart on the left, displaying the performance of sales, NIAT, and total return for Home Depot and Lowes since 2000. You may click on the chart, and on the subsequent stock price charts, to view larger versions of all of them.
 To get a better picture, here's a Yahoo-sourced chart of stock prices for Home Depot and Lowes, plus the S&P500 Index, for the past five years. Lowes is clearly superior, and HD can't even outperform the S&P. Despite Cooperman's plea that the firm is simply misunderstood, the market
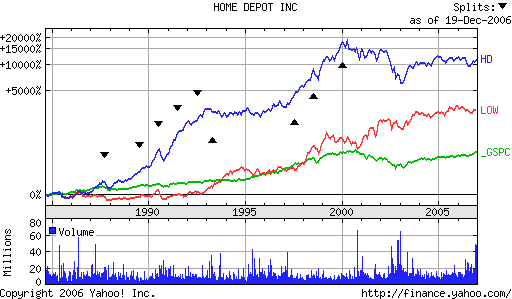 For a little more perspective, here's a chart of the same data for a much longer timeframe. It's clear that, since 2000, things have never been as good for Home Depot as they were before then. Nothing that Nardelli has done for six years has succeeded in improving the company's total return to beat that of the S&P500.